EUR/USD Weekly Forecast: US President Donald Trump judgment day has come
- The Federal Reserve and the European Central Bank kept rates unchanged in their October meetings.
- US mid-term elections are a referendum on President Donald Trump’s performance.
- EUR/USD approaches yearly low with a firm bearish bias.
The EUR/USD pair settled around 1.1160, down for the week and closing October with losses. The US Dollar (USD) advanced through the first half of the week but changed course after the Federal Reserve (Fed) monetary policy announcement, then fell further after the European Central Bank (ECB) reported the same decision. The Greenback regained some poise on Friday, as risk aversion took the lead.
Federal Reserve worried, but in no rush
The Fed kept the Fed Funds Target Range (FFTR) unchanged at 3.75%–4.00%, as widely anticipated. The accompanying statement showed that two voting members preferred a rate hike, and that, in general, policymakers remain worried about inflation, while acknowledging the economy is growing at a “strong pace.”
Chair Kevin Warsh noted that the interest rate hike delivered in September is already showing its impact in slightly tighter credit conditions, adding that he still does not think the economy is "too hot" or generating demand-side inflation that needs to be curbed, which cooled down hopes for an aggressive 50 basis points (bps) hike in December and took the USD lower.
Warsh added they prefer to have more data, but the upcoming United States (US) midterm elections are likely another reason to stay pat.
As a note of color, the Federal Open Market Committee (FOMC) announced it will change its schedule next autumn, stating that eight meetings per year is “the right number,” while adding that one of such meetings will not include a vote on the policy rate, but will focus on strategy. For 2028, the FOMC expects to have six policy-setting meetings.
Meanwhile, US data supported the Fed's assessment. Preliminary estimates of Gross Domestic Product (GDP) showed the economy grew at an annualized pace of 3.4% in the three months to September, up from 2.2% and beating the 3.2% expected. Also, the September Personal Consumption Expenditures (PCE) Price Index, the Fed’s preferred inflation gauge, rose 3.6% YoY, as anticipated, while the core annual reading also matched expectations at 3.1%. The figures, while not a surprise, still indicated persistently high inflationary pressures.
ECB on hold, reshuffle at sight
The ECB announced on Thursday that it left key rates unchanged, as expected. With this decision, the interest rate on the main refinancing operations, the interest rates on the marginal lending facility and the deposit facility stood at 2.65%, 2.9% and 2.5%, respectively.
The accompanying statement repeated well-known concepts: decisions will be taken meeting by meeting, but officials believe they are well positioned to “navigate current elevated uncertainty.”
The ECB acknowledged that energy prices had risen beyond its baseline assumptions, and expects inflation to remain well above target over the coming quarters, conditioning inflation decline on easing energy prices. On growth, policymakers noted the risks are tilted to the downside, as, despite some positive news such as AI investment and government spending, demand remains subdued amid higher energy prices, fiscal uncertainty and tighter financial conditions, among other reasons.
Nevertheless, the Euro (EUR) managed to advance vs the USD as a December interest rate hike in Europe is firmly in place, while the Fed seems to be in no rush to hike rates, despite inflation holding well above the central bank’s goal of 2%.
The ECB had also a note of color: President Christine Lagarde will leave in February 2027 rather than in October as it should be. Isabel Schnabel, Executive Board member, and Philip Lane, Chief Economist, are also set to depart in early 2027, in January and May respectively, meaning significant changes could be coming to the ECB.
Data-wise, Germany reported that the economy grew at an annualized pace of 1.2% in the third quarter, according to the preliminary GDP estimate. The Eurozone economic advance came in at 1.3%, both slightly above the previous 1% and 1.2%, respectively. Other than that, the German Harmonized Index of Consumer Prices (HICP) rose less than anticipated in October, up 2.8% from a year earlier vs the previous 3.3% and the expected 3.1%. The EUR turned lower with the headlines.
US mid-term elections
US citizens will go to the polls on Tuesday to decide which party will control Congress. All 435 seats in the House of Representatives and 35 of the Senate’s 100 seats are up for grabs. Additionally, special elections in Florida and Ohio will be held to fill the seats vacated by US Secretary of State Marco Rubin and Vice President JD Vance.
Ahead of the election, US President Donald Trump’s Republican Party holds a majority in both chambers, but not by much, as the Democratic Party needs to gain three seats in the House and four in the Senate to take control.
Some states are considered battlegrounds, meaning chances of any winning are pretty much even. When it comes to the Senate, the focus will be on Michigan, Georgia, Maine, Ohio and Texas, while regarding the House race, it seems far more spread this time: investors will be looking at results coming from California, Florida, New York, Texas, Michigan, Ohio and Pennsylvania, among other states.
Mid-term elections are, in fact, a referendum on the President’s performance, and Trump has it tough. His approval rating has dropped to roughly 30%, a record low for a sitting president since World War II. US citizens are unhappy with the economic performance, as the cost of living due to Trump’s foreign policy decisions has impacted households.
Still, President Trump plans to maintain its aggressive foreign policy, particularly in the Middle East after the elections, as the change in Congress will take place in early January. Afterward, Democrats will push to end the war to bring down energy prices and will also vow against tariffs, another inflation-related trigger.
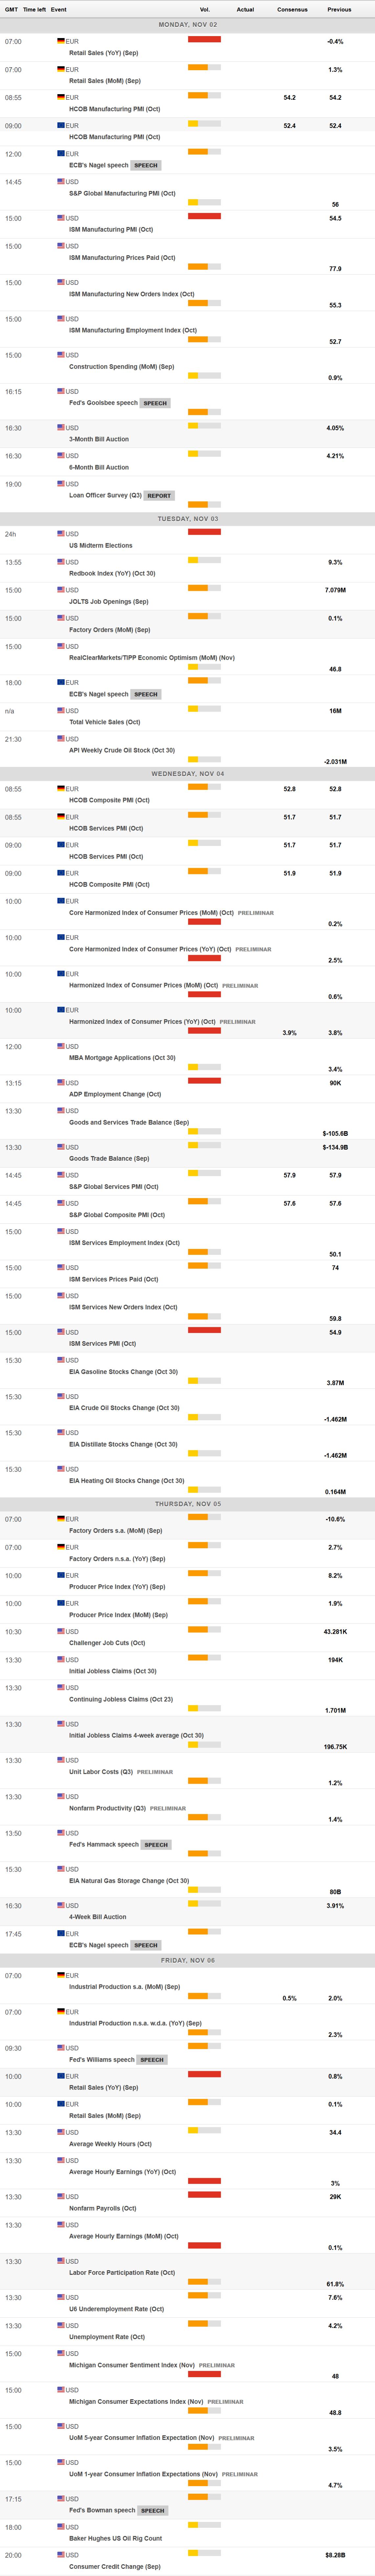
Beyond US midterm elections, the focus will be on US employment data, with the October Nonfarm Payrolls (NFP) report scheduled for Friday. The country will also publish the ISM Services and Manufacturing Purchasing Managers’ Indexes (PMIs) and the preliminary estimate of the November Michigan Consumer Sentiment Index.
Across the pond, Germany will offer September Retail Sales, while the EU will publish the preliminary estimate of the October HICP and September Retail Sales.
EUR/USD Technical Outlook:
As the week ends, the EUR/USD pair trades near a recent 2026 low of 1.1104. Technical readings favor a continued decline, with speculative interest now looking at the next critical threshold at 1.1000.
On the daily chart, EUR/USD trades below the short- and medium-term moving averages and keeping the near-term bias bearish. The 20-day Simple Moving Average (SMA) at 1.1196 is the nearest overhead barrier, while the 100-day SMA at 1.1431 and the 200-day SMA at 1.1559 reinforce a broader topside cap. The Momentum indicator has nearly flattened around its midline, while the Relative Strength Index (RSI) indicator, which aims south at 35, in line with further slides ahead.
According to the weekly chart, EUR/USD is poised to extend its slump. The pair is trading below the 100-week SMA at 1.1385 and the 20-week SMA at 1.1428, while bouncing off the 200-week SMA around 1.1100. Technical indicators in the chart head south within negative territory with uneven strength, yet still point to another leg south ahead.
On the topside, immediate resistance is clustered around the 20-day SMA at 1.1196, where any corrective bounce would likely stall initially. Above it, the pair could extend its recovery toward 1.1300, while further advances will meet resistance at the 100-week SMA at 1.1385. The bearish case will gain strength once the pair breaks below the 200-week SMA at 1.1100, with investors then looking for a test of the psychological 1.1000 mark.
(The technical analysis of this story was written with the help of an AI tool. Know more.)
Author

Valeria Bednarik
FXStreet
Valeria Bednarik was born and lives in Buenos Aires, Argentina. Her passion for math and numbers pushed her into studying economics in her younger years.

















