EUR/USD Weekly Forecast: Middle East ceasefire hangs by a thread
- A ceasefire in the Middle East boosted the mood and kept the US Dollar under selling pressure.
- The United States reported tepid growth and soaring inflation, but data did not surprise.
- EUR/USD is mildly bullish, but buyers remain cautious amid the uncertainty surrounding the Iran war.
The EUR/USD pair came back to life this week, settling a handful of pips above the 1.1700 mark. Risk-on flows began late Tuesday, when United States (US) President Donald Trump withdrew his threat to destroy Iran.
Fragile truce, weekend negotiations
Financial markets were on edge at the beginning of the week as President Trump announced Tuesday was going to be “power plant and bridges day,” announcing he would destroy Iran’s infrastructure should the country maintain the Strait of Hormuz closed. Even further, Trump stated that “a whole civilization will die tonight,” early on Tuesday.
A couple of hours ahead of the deadline, however, Trump TACOED. With the intervention of Pakistan, a ceasefire, subject to the reopening of the Hormuz Strait, was announced:
Based on conversations with Prime Minister Shehbaz Sharif and Field Marshal Asim Munir, of Pakistan, and wherein they requested that I hold off the destructive force being sent tonight to Iran, and subject to the Islamic Republic of Iran agreeing to the COMPLETE, IMMEDIATE, and SAFE OPENING of the Strait of Hormuz, I agree to suspend the bombing and attack of Iran for a period of two weeks. This will be a double-sided CEASEFIRE!”
Trump further added that Iran offered a 10-point proposal that is “ a workable basis on which to negotiate.” The fragile truce included Israel, but not Lebanon. Attacks between Tel-Aviv and Beirut continued, making market players hesitate about a sustained agreement.
By the end of the week, Trump’s mood deteriorated: “Iran is doing a very poor job, dishonorable, some would say, of allowing Oil to go through the Strait of Hormuz. That is not the agreement we have! President DONALD J. TRUMP,” he wrote in Truth Social on Thursday.
Nevertheless, the market sentiment remained optimistic, ahead of negotiations in Islamabad scheduled for the weekend. The White House negotiating team would be led by Vice President JD Vance and would include envoys Steve Witkoff and Jared Kushner. Iran will be represented by Foreign Minister Abbas Araghchi and parliament speaker Mohammad Bagher Ghalibaf, while senior figures from Iran’s Revolutionary Guard are also expected to attend.
As said, the truce seems extremely fragile, given that back-and-forth attacks in some Persian Gulf countries continue, while the Strait of Hormuz is nowhere near open as previously to the war. Iran is letting some ships go through, but navigation remains restricted.
FOMC meeting minutes
The Federal Open Market Committee (FOMC) released the minutes of their March monetary policy meeting on Wednesday, and leaned dovish, as officials still see an interest rate cut in 2026, if inflation declines as projected. However, policymakers also acknowledged that upside risks to inflation and downside risks to employment are elevated. Regarding the Middle East war, officials understand that the conflict could soften the labor market enough to warrant additional cuts, but noted that higher Oil prices could call for rate increases. Regarding the war’s, it is too early to know, according to policymakers.
The document provided near-term support to the Greenback, although the American currency remained on the back foot and resumed its decline after the dust settled.
US data fuels Fed-hike odds
US data showed some setbacks in growth and accelerating inflation, which backs the case for a Federal Reserve (Fed) rate hike, or at least diminishes the odds of a cut.
The ISM Services Purchasing Managers’ Index (PMI) printed at 54 in March, easing from the 56.1 posted in February. The sub-components of the report showed easing employment levels and much higher inflation. Durable Goods Orders shrank 1.4% in February, vs a 0.5% decline anticipated.
Even worse, the final estimate of the Q4 Gross Domestic Product (GDP) showed real GDP expanded at an annual rate of 0.5%, down from the preliminary estimate of 0.7% and the 4.4% posted in Q3. Weekly unemployment claims, in the meantime, increased to 219K for the week ending April 4, worse than the 210K expected and higher than the previous week's print of 203K. The dismal numbers added to the broad USD weakness.
Finally, the Consumer Price Index (CPI) rose to 3.3% in March, following the 2.4% posted in February and in line with market expectations. The core annual CPI was up 2.6% after posting 2.5% in the previous month and below the 2.7% anticipated. The worrisome figures were, anyway, anticipated by market participants, having no impact on the USD but maintaining it on the losing side.
What about Europe?
German macroeconomic figures showed the economy remains resilient, although the impact of the Middle East war is yet to be seen. Factory Orders were up 0.9% MoM and 3.5% YoY in February, much better than anticipated. The country’s Trade Balance posted a surplus of €19.8 billion in the same month, beating expectations. The Eurozone published the Producer Price Index (PPI), which declined by 0.7% on a monthly basis in February, as expected, while Retail Sales in the same month were down 0.2%, as expected.
Regarding the European Central Bank (ECB), and as President Christine Lagarde noted by the end of March, the central bank stands ready to hike interest rates, even in the case of “not-too-persistent” rise in inflation. Still, market players expect the ECB to hold steady this year, with bets on a rate hike contingent on the war-driven energy shock.
What’s next in the docket
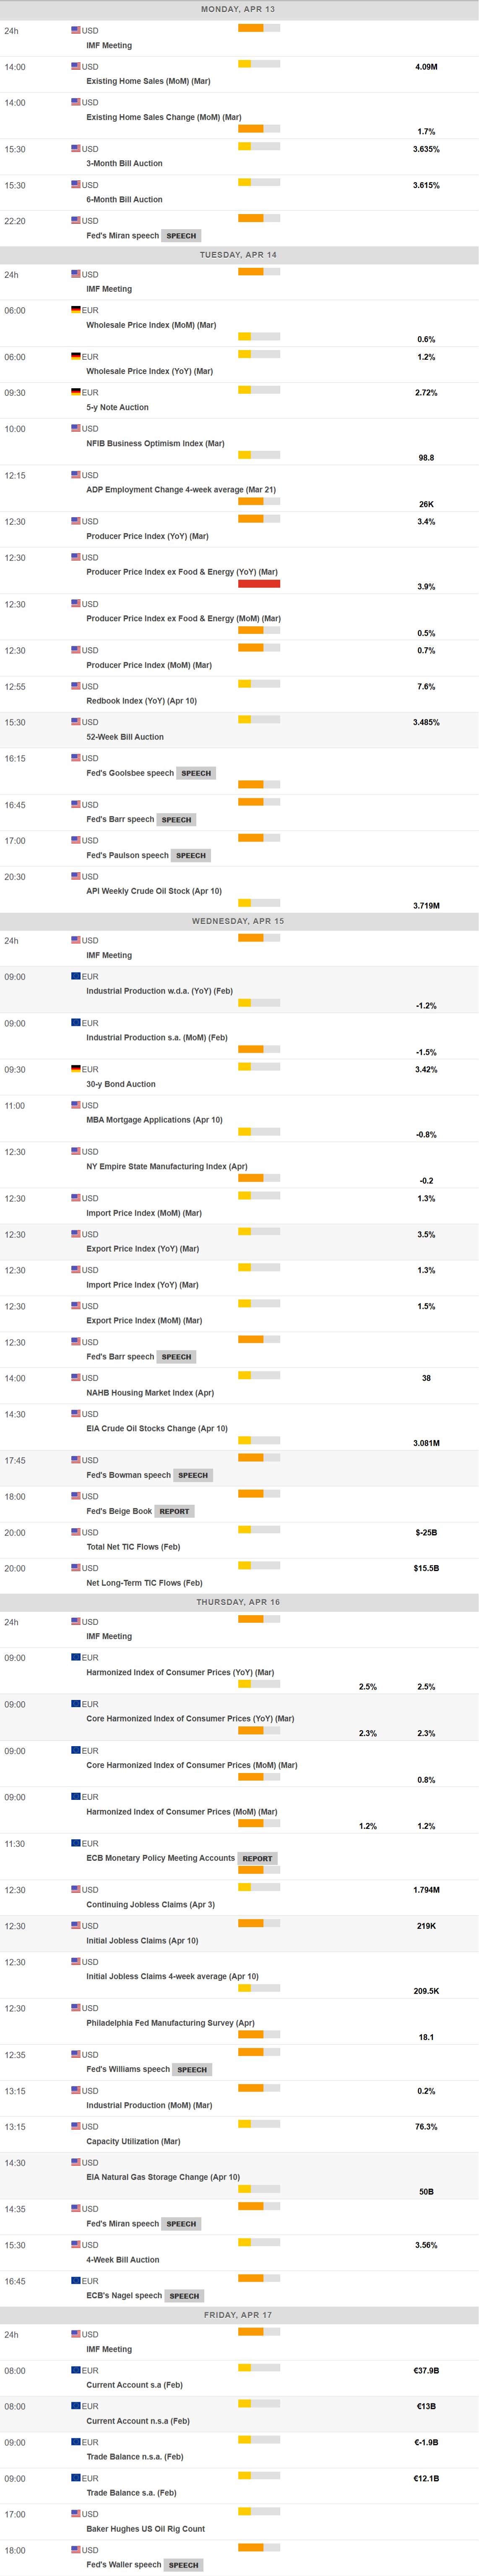
The macroeconomic calendar features few relevant figures these days: The US will publish the March PPI on Tuesday, with a slew of Fed and ECB speakers scheduled on the same day. Thursday will bring the final estimate of the March Eurozone Harmonized Index of Consumer Prices (HICP), US weekly unemployment data, and March Industrial Production and Capacity Utilization.
Progress, or the lack of it in the Middle East front, is likely to set the tone.
EUR/USD technical outlook
From a technical point of view, the daily chart shows that EUR/USD is extending its recovery above the main moving averages and keeping a constructive near-term bias. The pair now holds over the 100-day simple moving average (SMA) at 1.1694 and the 200-day SMA at 1.1672, while the 20-day SMA lags further below at 1.1568, a configuration that hints at an improving underlying trend. The Momentum indicator backs the bullish bias, although with limited upward strength. Finally, the 14-day Relative Strength Index (RSI) indicator is trending northward around 61, suggesting buyers retain control for now, even if the move is not yet overextended.
The longer-term perspective is also positive, although additional confirmations are required. The EUR/USD pair is comfortably above the 20-week SMA, now flat at 1.1687, while the longer-term 100- and 200-week SMAs at 1.1202 and 1.0917 continue to underpin the broader uptrend from below. Weekly Relative Strength Index around 54 signals balanced momentum after recent gains, and the mildly positive 14-week Momentum reading hints that upside pressure is present, albeit still unable to confirm a sustained advance ahead.
Initial support is located at the 100-day SMA around 1.1694, followed by the 200-day SMA near 1.1672, where a deeper pullback would be expected to attract dip-buying interest. A more pronounced correction could see the pair revisiting the 20-day SMA at 1.1568, which marks a more distant but still relevant demand area within the broader constructive backdrop. Resistance, on the other hand, lies at 1.1750, followed by the 1.1820 region. A clear advance beyond the latter opens the door for a test of the 1.2000 psychological threshold.
(The technical analysis of this story was written with the help of an AI tool.)
Economic Indicator
FOMC Minutes
FOMC stands for The Federal Open Market Committee that organizes 8 meetings in a year and reviews economic and financial conditions, determines the appropriate stance of monetary policy and assesses the risks to its long-run goals of price stability and sustainable economic growth. FOMC Minutes are released by the Board of Governors of the Federal Reserve and are a clear guide to the future US interest rate policy.
Last release: Wed Apr 08, 2026 18:00
Frequency: Irregular
Actual: -
Consensus: -
Previous: -
Source: Federal Reserve
Minutes of the Federal Open Market Committee (FOMC) is usually published three weeks after the day of the policy decision. Investors look for clues regarding the policy outlook in this publication alongside the vote split. A bullish tone is likely to provide a boost to the greenback while a dovish stance is seen as USD-negative. It needs to be noted that the market reaction to FOMC Minutes could be delayed as news outlets don’t have access to the publication before the release, unlike the FOMC’s Policy Statement.
Author

Valeria Bednarik
FXStreet
Valeria Bednarik was born and lives in Buenos Aires, Argentina. Her passion for math and numbers pushed her into studying economics in her younger years.

















