EUR/USD Weekly Forecast: All eyes on the December Federal Reserve decision
- Recent US data and Federal Reserve officials’ comments revive hopes of a December cut.
- European macroeconomic data keep hinting at torturous economic progress in the Old Continent.
- EUR/USD keeps trading within familiar levels, with a modest bearish technical tilt.
The EUR/USD pair held within familiar levels in the last trading day of November, settling below the 1.1600 mark. The pair had made little progress throughout the month and even clinched a fresh three-month low of 1.1468, despite broad US Dollar (USD) weakness.
The American currency found some footing in the first two weeks of November amid speculation that the Federal Reserve (Fed) could refrain from cutting rates in the upcoming December meeting. However, the USD lost steam as days went by, as speculative interest slowly resumed bets on an interest rate trim.
It is all about the Federal Reserve
Initial speculation on an on-hold Fed was triggered by Chairman Jerome Powell, who said a December rate cut should not be taken for granted following the October Federal Open Market Committee (FOMC) decision to cut interest rates by 25 basis points (bps). However, the tide began turning after some Fed officials hinted at still room for an interest rate cut at the last meeting of the year considering the current modestly restrictive monetary policy stance. The odds for a December cut stand at roughly 85%, well above the 39% in the previous week, according to the CME FedWatch Tool.
Meanwhile, the United States (US) data flow continued to be irregular in the aftermath of the government shutdown. The country published September Retail Sales, which rose a modest 0.2% in the month, following a 0.6% increase in August. Also, Durable Goods Orders were up 0.5%, slightly better than the 0.3% anticipated, yet below the August reading of 3.0%. The Producer Price Index (PPI) for the same month rose by 2.7% from a year earlier, meeting expectations, while the core annual reading printed at 2.6%, slightly below the 2.7% expected. Overall, inflation at wholesale levels remained stable at non-concerning levels.
Employment-related figures, however, painted a different story: The ADP Employment Change 4-week average showed that the US private sector lost job positions for a third consecutive week. For the four weeks ending November 8, private employers shed an average of 13,500 jobs a week, according to the report. This is the third consecutive negative reading. On a positive note, Initial Jobless Claims increased by 216K, improving from a revised 222K in the previous week.
Finally, Consumer Confidence plummeted in November, according to the Conference Board’s monthly report. The index printed at 88.7, following the 95.5 posted in October, also missing expectations of 93.4 and the lowest reading since April.
Euro can’t find its footing
Across the pond, the Euro (EUR) remains among the less attractive high-yielding currencies. The EUR has been unable to attract speculative interest for quite some time as market participants lost interest once the European Central Bank (ECB) completed the monetary easing cycle and President Christine Lagarde announced the monetary stance is in a “good place.”
Additionally, EU data remains generally unimpressive, hinting at slow economic progress. Germany released the final estimate of the Q3 Gross Domestic Product (GDP), confirming it at 0%. Also, the November IFO survey showed that the Business Climate index deteriorated to 88.1 from the previous 88.4, while Consumer Confidence in December improved slightly from -24.1 to -23.2, according to the GfK survey.
Finally, the country reported on Friday that Retail Sales fell by 0.3% in October, worse than the 0.2% advance anticipated, while the preliminary estimate of the November Harmonized Index of Consumer Prices (HICP) printed at 2.6% YoY, higher than the 2.4% anticipated and the previous 2.3%. Every month, the HICP was 0.5% down after surging by 0.3% in the previous month.
What’s next?
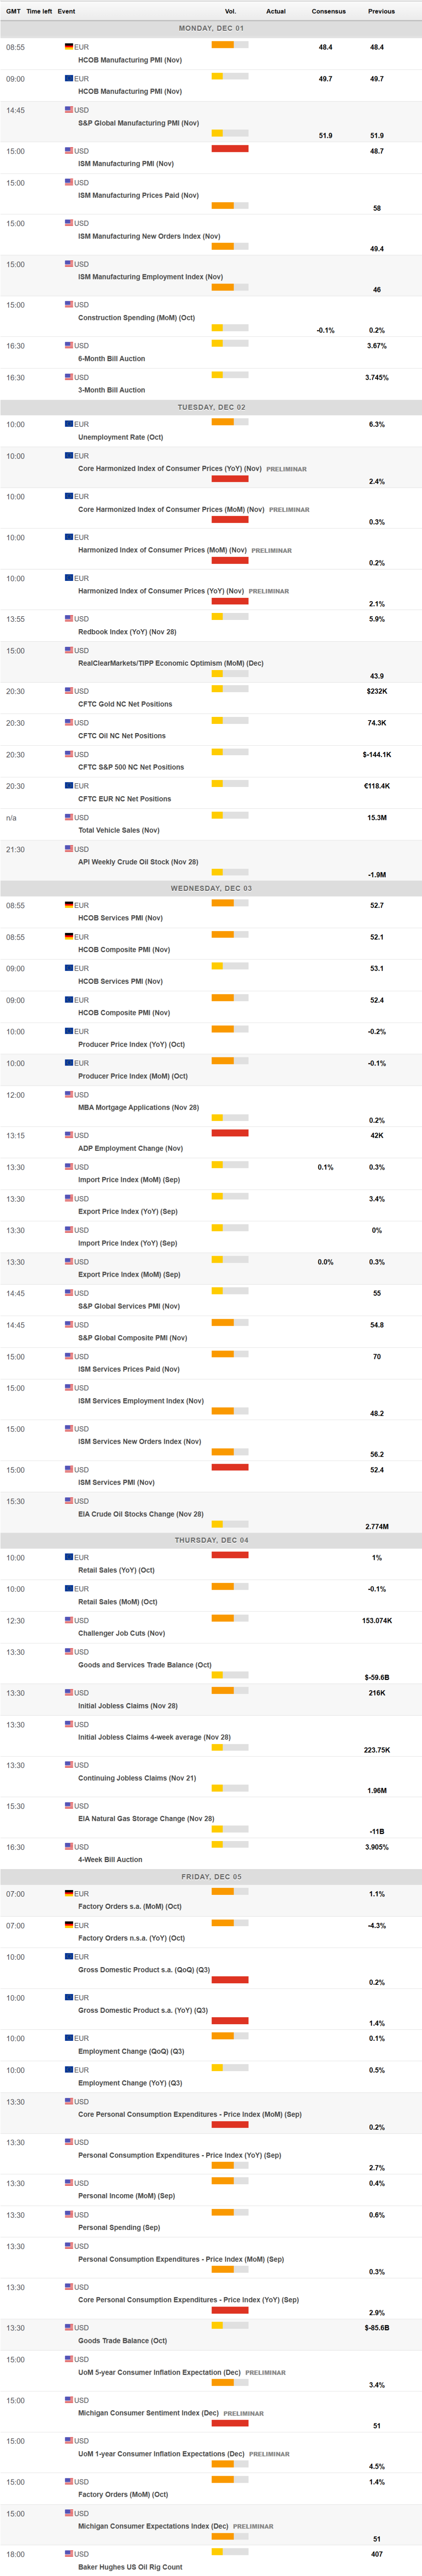
The macroeconomic calendar will kick start December with the release of the November US ISM Manufacturing Purchasing Manager’s Index (PMI) on Monday. The Hamburg Commercial Bank (HCOB) and S&P Global will release the final version of their own Manufacturing PMIs for the EU and the US, respectively, on the same day. Services PMIs will be out on Wednesday.
In the meantime, the EU will release the preliminary estimate of the November HICP, and the October Producer Price Index (PPI). October Retail Sales will be out on Thursday, while a Q3 GDP revision will be out on Friday.
By the end of the week, the US will publish Challenger Job Cuts and the September Personal Consumption Expenditures (PCE) Price Index, the Fed’s favorite inflation gauge. Finally, the country will unveil October Factory Orders and the December Michigan Consumer Sentiment Index.
Market participants will continue to assess data to try to anticipate whatever the Federal Reserve could do when it meets in December.
EUR/USD technical outlook
The daily chart for the EUR/USD pair shows it trades around 1.1570. The pair rests above a flat 20-day Simple Moving Average (SMA) while beneath the 100-day SMA, the latter providing resistance at around 1.1645. The 200-day SMA, in the meantime, rises, currently in the 1.1430 price zone. At the same time, the Momentum indicator stands just above its midline and eases, signaling waning buying pressure. Finally, the Relative Strength Index (RSI) indicator prints 48, posting a neutral-to-bearish stance.
In the weekly chart, the risk for EUR/USD is also skewed to the downside. The Momentum indicator consolidates below its midline, edging marginally higher, yet not enough to hint at an upcoming recovery, while the Relative Strength Index (RSI) indicator paints a similar picture at 52. The 20-week Simple Moving Average (SMA) has flattened above the current level, providing resistance in the 1.1650 price zone. The longer moving averages, on the other hand, maintain modest upward slopes well below the current level, with the 100-week SMA at 1.1035.
The bearish case will become firmer once the pair breaks below the 1.1460/70 price zone, while a recovery needs to extend beyond 1.1700 to make sellers hesitate.
(The technical analysis of this story was written with the help of an AI tool)
Author

Valeria Bednarik
FXStreet
Valeria Bednarik was born and lives in Buenos Aires, Argentina. Her passion for math and numbers pushed her into studying economics in her younger years.

















