Don‘t fear risk-off

Not confirmed by bonds, the S&P 500 advances regardless – the daily yields retreat is powering tech while value goes nowhere. Higher beta sectors such as financials are sputtering, revealing the defensive nature of the stock market advance – at least to this degree, stocks and bonds are in tune. Yes, risk-off is winning these days, and it would be only up to VIX to join the fray, but the key volatility measure is likely to keep complacently trading around the 17 level. In other words, not too far from the bottom of its recent range, and not indicating imminent change of the bull market character.
While we have seen much better market breadth readings in the years gone by (the narrow leadership is reminiscent perhaps of the late 1990s), there‘s no chart proof of the behemoths being in kind of getting really serious trouble (with the possible exception of Facebook). True, smallcaps have largely gone sideways over the many months, but midcaps are already breaking higher, and that won‘t be unnoticed by the Russell 2000 (soon to follow).
The bears haven‘t thus far made any serious appearance, and 4,550s held with ease in spite of the dollar reversing Thursday‘s losses. All the more encouraging is the relative strength of both gold and silver when faced with one more daily decline in inflation expectations – as if balancing before the Fed act changes anything.
I ask, how serious can they be about delivering on taper promises when prices increase relentlessly (look at Europe too), these are being blamed on supply chain bottlenecks without acknowledging their persistent and not transitory nature, and the real economy is markedly slowing down (not in a recession territory, but still)?
Looking at commodities, we‘re reliving the 1970s, and cryptos are still the key beneficiary of monetary largesse – precious metals aren‘t a dead asset class in the least, they just frontrunned it all and peaked in August 2020 as I alerted you to back then. Fresh upswing is in the making.
Let‘s move right into the charts.
S&P 500 and Nasdaq outlook
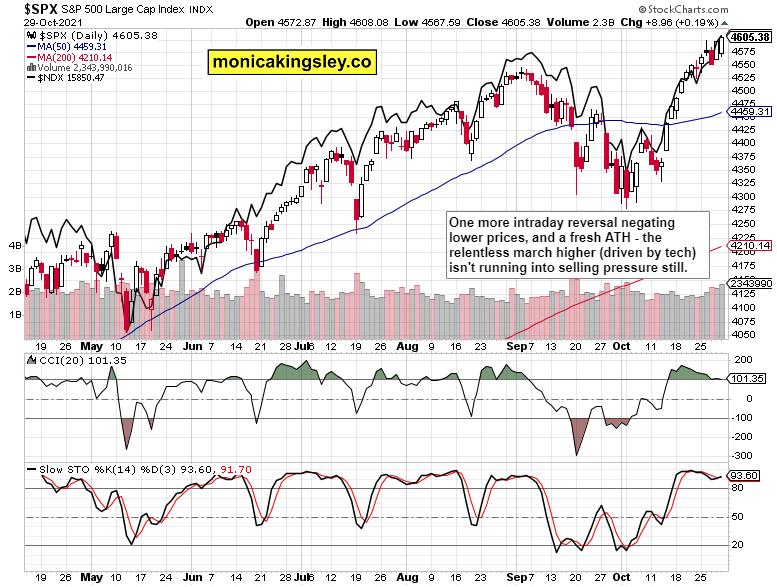
S&P 500 once again decisively reversed upwards, and even though the daily indicators are weakening, the rally can easily go on. Dips are to be bought.
Credit markets
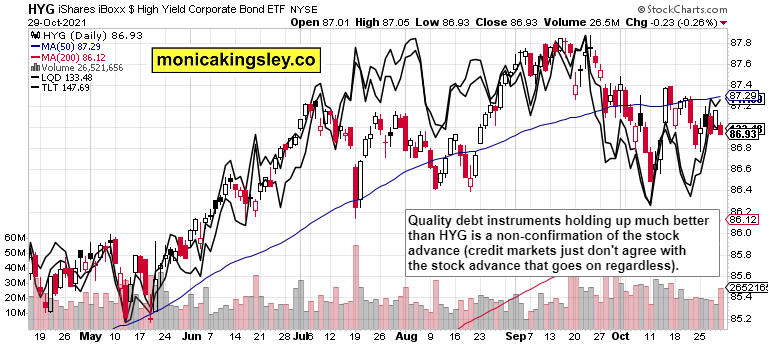
HYG keeps acting weak, but this is being overlooked by stocks as tech remains driven by NYFANG.
Gold, Silver and Miners
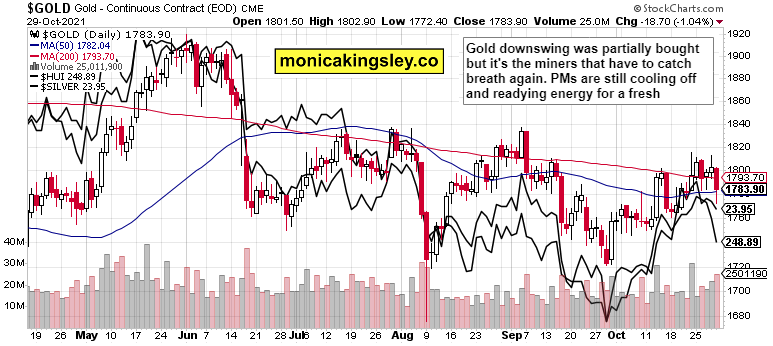
Gold‘s lower knot indicates accumulation, and miners reversing higher would be a great confirmation. Regardless, such a result when dollar rose steeply and yields with inflation expectations retreated, is encouraging.
Crude oil
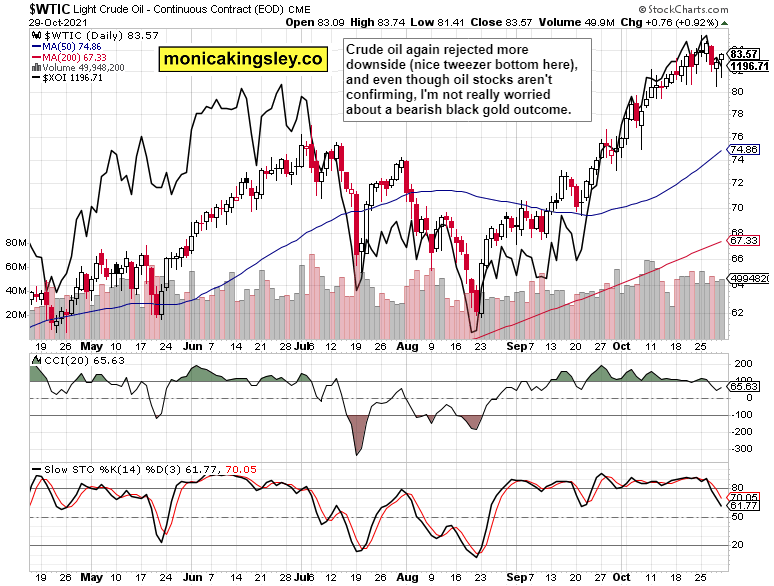
Crude oil again held $81, looks set to return above $84 again. XOI and XLE weakness has to be understood in terms of the challenged VTV, and isn‘t here to stay.
Copper
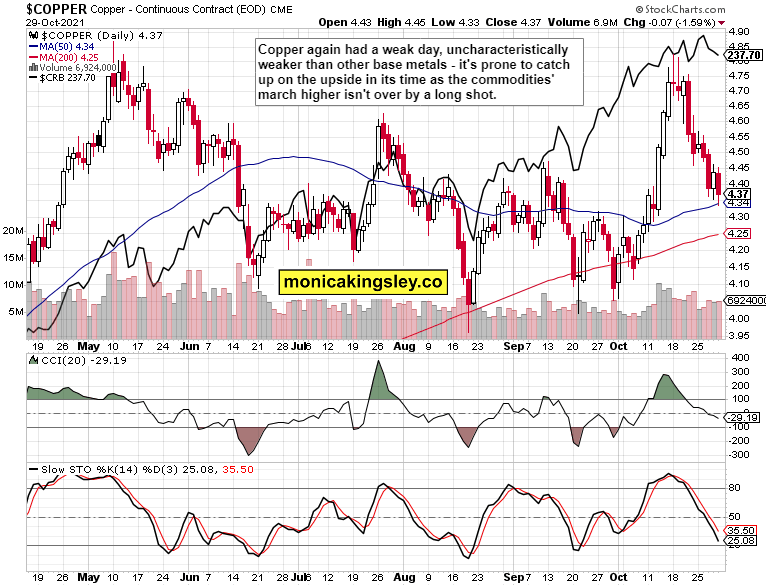
Copper is providing a buying opportunity, and looks likely to join other base metals (especially alluminum) and broader commodity index strength as agrifoods wake up too.
Bitcoin and Ethereum
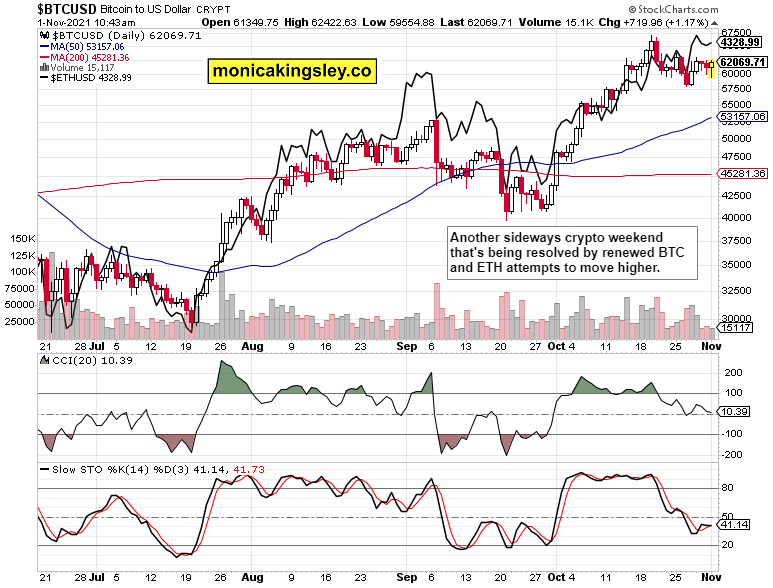
The Bitcoin and Ethereum upswings can go on – it looks to be a question of a relatively short time when cryptos are done with the sideways correction.
Summary
S&P 500 indeed got at 4,610s instead of suffering setbacks, and the same holds true for real assets next. Across the board, these have performed well in spite of the USD upswing and decreasing inflation expectations, which I chalk down to pre-Wednesday positioning. Therefore, I‘m taking the high beta weakness with a pinch of salt, and the same goes for precious metals or the economic cycle sensitive copper. As for oil, the U.S. economy can (and will have to) withstand prices higher than $90 as 2022 arrives.
Author

Monica Kingsley
Monicakingsley
Monica Kingsley is a trader and financial analyst serving countless investors and traders since Feb 2020.