|

The resilience of 50bp cutting odds yesterday didn‘t send the Yen rising

Powell delivered 50bp as I predicted he would – those trial balloons were not ordinary. Also the „no one left to sell to“ reaction to the bullish (bullish as it is inflating asset prices) reaction arrived iduring the conference.

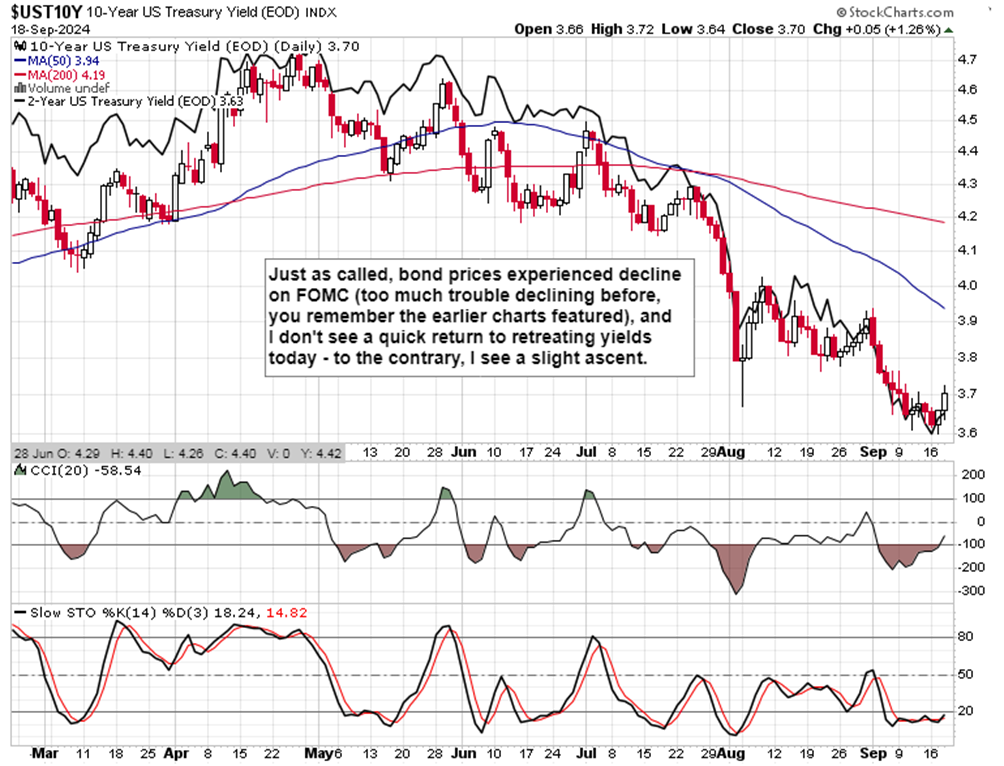
Bonds declined as predicted, and the strong reaction in commodities (except oil) confirms the above take as much as Russell 2000 performance – it‘s that silver outperformed gold – now as the dust is settling.

So, what led me to the successful prediction, how did I arrive at such a conclusion for clients yesterday well before the opening bell? Quoting the article‘s premium part:

(…)  There is upswing rejection with mixed sectoral leadership picture, but I take markets being prepped for 50bp cut quite at last minute seriously – Timiraos with Dudley, and then there is Williams and Goolsbee that had already been pushing for a Jul rate cut (yes, I called it a policy mistake not to cut then). Now, they sound like trying to get ahead of the curve (market craving more cuts) byt starting the easing cycle with 50bp, and I consider yesterday‘s statements as tests of whether 50bp wouldn‘t spook markets anymore.

Yes, it looks like it would nt, and that fostered even greater put to call ratio complacency yesterday, making me consider at least an intraday setback as likely – and it would be steeper than the one called yesterday.

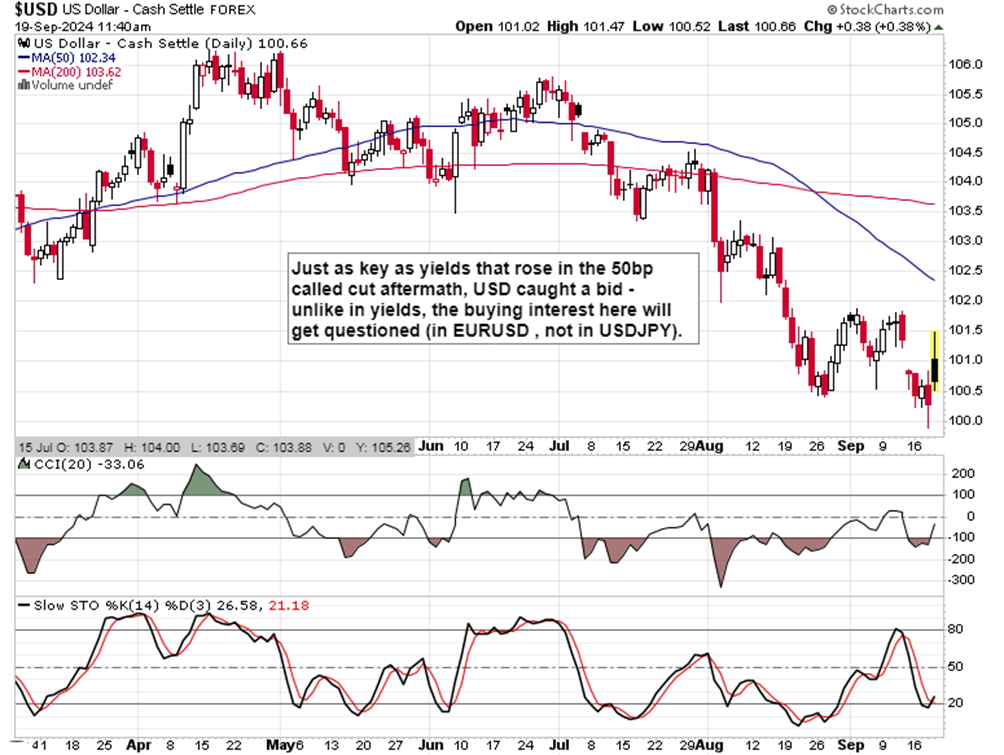
The resilience of 50bp cutting odds yesterday didn‘t send the yen rising, which is the key factor (yen carry trade unwind in progress) that would discourage the Fed from decreasing the yields differential – it isn‘t happening, so even if I lean towards Powell not making a cautious starting 25bp cut only (which doesn‘t „admit“ convey failure to cut earlier), but to take the risk of 50bp cut (listening to the calls to cut by this much) as it is too great to simply ignore.

It all illustrates extreme uncertainty of the moment. Yes, I lean towards Powell trying to solve the conundrum via dovish conference and dot plot if he doesn‘t deliver on the 50bp – and thanks to the excessively bullish positioning supported by job market weakness, I favor the „there is no one left to sell to“ reaction (25bp would make interest rate and income plays being hit, and it also increases general uncertainty about future cuts vs. if it were done now to make up for lost Jul).

Being ready for him delivering on 50bp would only accentuate the reaction of „sell the news“, because most are positioned for that outcome precisely.

See also bonds already declining premarket, which only adds to the mechanics described above – and the necessity of 50bp cut positioning actually, and room for disappointment.
Chart
Chart

Author

Monica Kingsley

Monica Kingsley

Monicakingsley

Monica Kingsley is a trader and financial analyst serving countless investors and traders since Feb 2020.


More from Monica Kingsley
Share:

Editor's Picks

AUD/USD holds steady above 0.7000 as traders await RBA rate decision

AUD/USD extends its consolidative price move through the Asian session on Tuesday, trading just above 0.7000 ahead of the RBA rate decision. Meanwhile, the US Dollar sits near a two-month high as oil-driven inflation fears reaffirm Fed hike bets and continue to push US bond yields to multi-year highs. Moreover, the US-Iran standoff underpins the safe-haven buck and caps the currency pair.

USD/JPY consolidates near 157.50 as a bullish USD counters intervention risks

USD/JPY struggles to capitalize on the overnight bounce from a one-week low, consolidating around mid-157.00s during the Asian session on Tuesday. Trump's concerns about the Japanese Yen's weakness fueled speculation about another US-Japan joint intervention. This, along with the hawkish BoJ, underpins the JPY and caps the currency pair. Meanwhile, rising Fed rate-hike bets and oil-driven inflation fears continue to push US bond yields to multi-year highs, keeping the US Dollar pinned near a two-month high and supporting spot prices.

Gold bears await $4,100 break amid Fed hike bets and surging US bond yields

Gold consolidates the previous day's heavy losses to its lowest level since August 5, awaiting a break below $4,100 before the next leg down. Oil-driven inflation fears reaffirm bets of another Fed rate hike in October and continue to push US bond yields to multi-year highs, undermining the non-yielding bullion. Moreover, geopolitical risks help the US Dollar stand firm near a two-month high, which, in turn, favors XAU/USD bears.

RBA set to hike interest rate to 4.60% in September as inflation remains elevated
The Reserve Bank of Australia (RBA) is widely expected to raise the Official Cash Rate (OCR) by 25 basis points (bps) to 4.60% from 4.35% on Tuesday, after keeping rates unchanged at its previous two meetings The decision will be announced at 04:30 GMT, accompanied by the Monetary Policy Statement (MPS), and followed by RBA Governor Michele Bullock’s press conference at 05:30 GMT.
NEAR intents blocks more than $50M in attempted laundering linked to Bitget exploit

NEAR Intents, a cross-chain trading protocol, has blocked more than $50 million in attempted laundering flows linked to the recent Bitget exploit, while freezing $503,000 during the execution process. The intervention was carried out through SHIELD, the protocol’s risk-intelligence system, which monitors transactions for links to hacks and other illicit activity, according to a Monday report.

Fed vs BoJ: Both hiked. The market only believes one of them – and the chart shows which

The Fed and the BoJ have just done something remarkably similar. Both central banks raised interest rates by 25 bps last week, both are confronting inflation risks, and both signal that future decisions will depend on incoming economic data.