Bond markets still in focus, as Iran war heats up
- Gilts take the brunt of the selling
- How can oil prices retreat?
- Middle East war heats up
- Western welfare models struggle to operate in current environment
- Why the UK is in a worse position than elsewhere
- Is a political risk premium building in the UK?
- Can Broadcom boost the Nasdaq?
The bond market sell off is once again the main driver of price action on Wednesday. Stocks are broadly lower across Europe, with tech and industrials taking the brunt of the sell off. However, the decline in stocks is milder than it was on Tuesday. US futures are also pointing to a lower open, after a third straight losing day.
Gilts take the brunt of the selling
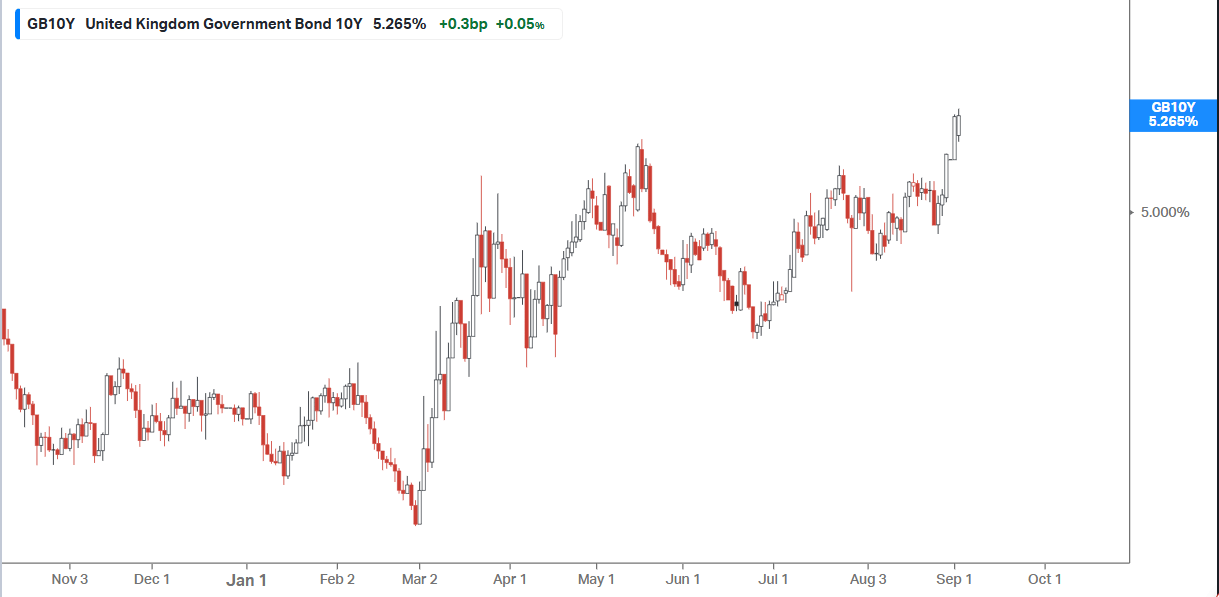
The bond market sell off continues on Wednesday, and the UK is leading the charge once more. The 2-year yield is higher by 7bps, while the 10-year is up by 5bps. The sell off is not as severe as Tuesday, but with the 10-year Gilt yield approaching 5.3%, a rise of 24bps in a month, this is a deeply uncomfortable fiscal position for the UK.
Added to this, the interest rate futures market is pricing in more than 3 rate hikes between now and July, which could add significant pain to households. The first hike could be in November, with UK interest rates expected to reach 4.26% by February next year.
Bonds are also selling off in Europe and Japan, but interestingly, the rise in US Treasuries has been moderate so far. The two year yield is higher by nearly 1bp and the 10-year yield is up only slightly this morning.
How can Oil prices retreat?
Brent crude oil has backed away from the highs of the morning above $96 per barrel, but is still trading around $95 per barrel. Oil prices are far too close to $100 per barrel for comfort, however, if this puts pressure on President Trump to end active hostilities with Iran, then the bond market sell off could calm down.
At this stage it is hard to see how the oil price can fall substantially from here. While there is plentiful oil supply right now, production in the US is near record highs, and although oil transit through the Strait of Hormuz is about 50% of pre-war levels about 8-9mn barrels are still getting through each day, the conflict is heating up.
Added to this, the US’s oil deal with Venezuela is not having a meaningful dampening effect on the oil price. Even though the deal could diversify the oil price in the long term.
Middle East war heats up
Iran has launched missiles on US bases in the region, and the US is attacking Iranian ‘targets’ in the Strait of Hormuz, according to US officials. President Trump has also backed away from reaching a deal with Iran, saying that an agreement with them ‘is not worth the paper it is written on’. This suggests a large escalation in the war, which may take time to resolve.
Western welfare models struggle to operate in current environment
This backdrop has played havoc with the oil market, and is the main driver of upheaval in the global bond market. In a month, we have gone from the Brent crude oil price trading in the $70’s to the $90’s in a matter of weeks, which is a rare occurrence. This justifies the sell off in the bond market. While it is a global phenomenon, the reality for highly indebted western nations is that their welfare models cannot operate in the current environment. The bond market is a reflection of the painful adjustment ahead.
Why the UK is in a worse position than elsewhere
The UK selling off worse than elsewhere may seem unfair, however, the government clearly needs to get a handle on how to operate in the current constrained environment. The UK’s fiscal fortunes are closely tied to the oil price. The reason is that oil price spikes push up inflation, which pushes up interest rates and bond yields, and this makes government borrowing more expensive.
Bond investors charge more to borrow from the UK because of its budget deficit, which is one of the highest in the G7. Although the budget deficit is expected to fall back to a more sustainable 3.6% of GDP in the current fiscal year, investors will believe it when they see it, as public sector borrowing has been above expectations in recent months. A rising risk premium that keeps Gilt yields elevated as we move towards the Budget is something worth watching.
Is a political risk premium building in the UK?
With a contentious budget coming up, and fractious Labour backbenchers, the political backdrop is adding a political risk premium onto UK debt. Even Andy Burnham’s former economic advisor, said that Burnham needs to get real about rising debt interest costs by scaling back welfare and reconsidering the triple lock.
Burnham may have come into power on a wave of optimism, but the 10-year Gilt yield chart below, could sour his mood, and add fuel to Kemi Badenoch’s fire as they face off in PMQs for the first time later today.
Can Broadcom boost the Nasdaq?
Elsewhere today, the focus could shift to the US labour market, ADP private sector payrolls will be released at 1330 BST. Later tonight, Broadcom will report last quarter’s earnings, which are expected to rise 91% in a year, revenues are expected to top $29.43bn, up 84% in a year. We will see if another set of good AI chip stock results can neutralise fears about oil prices and bond yields. The Philadelphia semiconductor index fell more than 2% on Tuesday, and is still down 19% in the past 3-months, even though Nvidia results were stunning last week.
Dell is surging in the pre market, and is higher by more than 9% after releasing a good set of results last night. In Europe,, Nokia is making a comeback onto the Eurostoxx 50 index, with Volkswagen likely to fall out of the major Eurostoxx index later this year.
10-year UK Gilt yield has risen significantly this year
Source: Koyfin
Author

Kathleen Brooks
XTB UK
Kathleen has nearly 15 years’ experience working with some of the leading retail trading and investment companies in the City of London.