Australian Dollar Price Forecast: Everybody is looking at the RBA
- AUD/USD treads water just above the 0.7000 yardstick on Monday.
- The US Dollar keeps the bid tone in place amid rising geopolitical tensions.
- The RBA is widely expected to hike its OCR by 25 basis points on Tuesday.
The Australian Dollar (AUD) has started the new trading week in an inconclusive fashion, with AUD/USD hovering just above the key 0.7000 region on Monday.
The pair’s lack of clear direction comes on the back of the resurgence of the buying interest in the US Dollar (USD), as investors continue to assess the latest headlines from the US-Iran crisis, while the continuation of the march north in US treasury yields across the curve also adds to the firm demand for the buck.
Following the September tops near 0.7240, spot appears to have started a downward move that is now putting the key 200-day SMA around 0.7020 to the test.
However, the bar for a sustained and deeper retracement seems pretty high considering the Reserve Bank of Australia’s (RBA) hawkish policy bias and still elevated domestic inflation.
Australia’s economy is slowing but remains on solid footing
Australia’s economy continues to compare favourably with many of its G10 peers, supported by domestic demand and positive economic growth. Persistent inflation also supports the RBA’s cautious, data-dependent policy stance.
However, business activity seems to have lost some momentum after preliminary data showed the Purchasing Managers’ Index (PMI) for Manufacturing cooling to 49.3 in September and easing to 51.4 when it comes to Services, from 52.0 and 53.2, respectively.
Trade data provided another positive signal: Australia recorded an A$1.923 billion surplus in July, adding to the A$2.341 billion surplus registered in June.
Growth figures were less encouraging, however. Indeed, the Gross Domestic Product (GDP) expanded by 0.4% QoQ in the second quarter of 2026, up from 0.3%, while annual growth came in at 2.1%, down from the previous 2.5% yearly expansion.
The labour market also showed mixed signs in August, with the Unemployment Rate rising to 4.6% and Employment Change increasing by 39.5K, reversing July’s nearly 16K drop.
Inflation remains the main constraint after July data showed price pressures running well above the RBA’s 2%-3% target band, suggesting that the return to target could remain uneven and prolonged. That said, the headline inflation eased to 3.5% in July (from 3.8%), while underlying price pressures tracked by the Trimmed Mean held steady at 3.6%.
The Melbourne Institute’s Consumer Inflation Expectations measure reinforced that view, holding steady at 4.9% in September.
The figures leave the RBA’s inflation task incomplete. Policymakers expect inflation to return to target only in early 2028, keeping the emphasis on patience rather than an imminent policy pivot.
China is stabilising, but not driving the Aussie higher
China is providing stability for the Australian economy, but not the growth impulse that has supported the Australian Dollar during previous expansions.
The Chinese economy grew by 4.3% YoY in the April-June period, while Industrial Production growth regained traction, expanding by 5.2% YTD, and the trade surplus widened to $119.1 billion in July, supported by decent increases in both imports and exports. However, on the downside, consumer spending remained sluggish after Retail Sales rose by only 0.4 % from a year earlier.
In addition, business surveys presented a mixed picture: the National Bureau of Statistics reported that the Manufacturing PMI improved to 49.8 in August from 49.2, while the Services PMI remained unchanged at 49.0. On the other hand, private measures like RatingDog remain in expansionary territory, with Manufacturing at 51.5 (from 50.9) and Services at 51.4 (from 50.4).
Disinflationary pressures seem to have taken a breather in August, with the CPI gaining 0.8% YoY, up from 0.5%, while prices rose by 0.4% on a monthly basis. Producer Prices rose by 3.8% over the previous twelve months, down from the 3.5% increase recorded in the previous month.
The People’s Bank of China (PBoC) left its Loan Prime Rates unchanged early on Monday, maintaining the one-year rate at 3.00% and the five-year rate at 3.50%.
China is therefore neither providing a major boost nor creating a significant drag. Unless the data reveal a clearer acceleration or deterioration, its influence on AUD/USD is likely to remain limited.
The RBA is ready for another rate hike
The RBA delivered a unanimous hawkish hold at its meeting in August. However, above-target inflation and upside risks to the outlook appear to underpin the broader view of a quarter-point rate hike at the bank’s gathering on Tuesday.
Indeed, following the release of the latest Minutes, several officials warned that inflation risks could materialise on the back of increased investment in data centres, cost pass-through and higher energy prices.
Ahead of the upcoming RBA event, market participants see nearly 42 basis points of tightening by year-end.
AUD/USD needs to reclaim 0.7200 to regain momentum
Baseline outlook
The medium-term outlook has deteriorated in the last few weeks, as the pair remains unable to regain upside traction in a sustained manner. While above the 200-day SMA (0.7023), the pair should keep its constructive tone unchanged. Against this backdrop, some consolidation in the short-term horizon should not be ruled out. Of note, the daily Relative Strength Index (RSI) is approaching the oversold zone, which could eventually spark some “technical” correction.
The resumption of the bullish bias will likely require a strong catalyst, namely a sustained improvement in risk appetite trends or continued US Dollar weakness.
Upside scenario
A stronger risk-on environment and a convincing break above 0.7200 would bring the 2026 high near 0.7280 into view.
Beyond that level, resistance emerges at the 0.7300 round level, followed by the 2022 ceiling at 0.7593.
Downside scenario
An additional deterioration in global risk sentiment, persistent strength in the Greenback, or renewed weakness in Chinese data could further fuel the ongoing selling mood.
Initial support is at the September floor of 0.7007 (September 24). A breach below the latter would increase the likelihood of a retest of the weekly low at 0.6922 (July 29)
Bears regain the upper hand
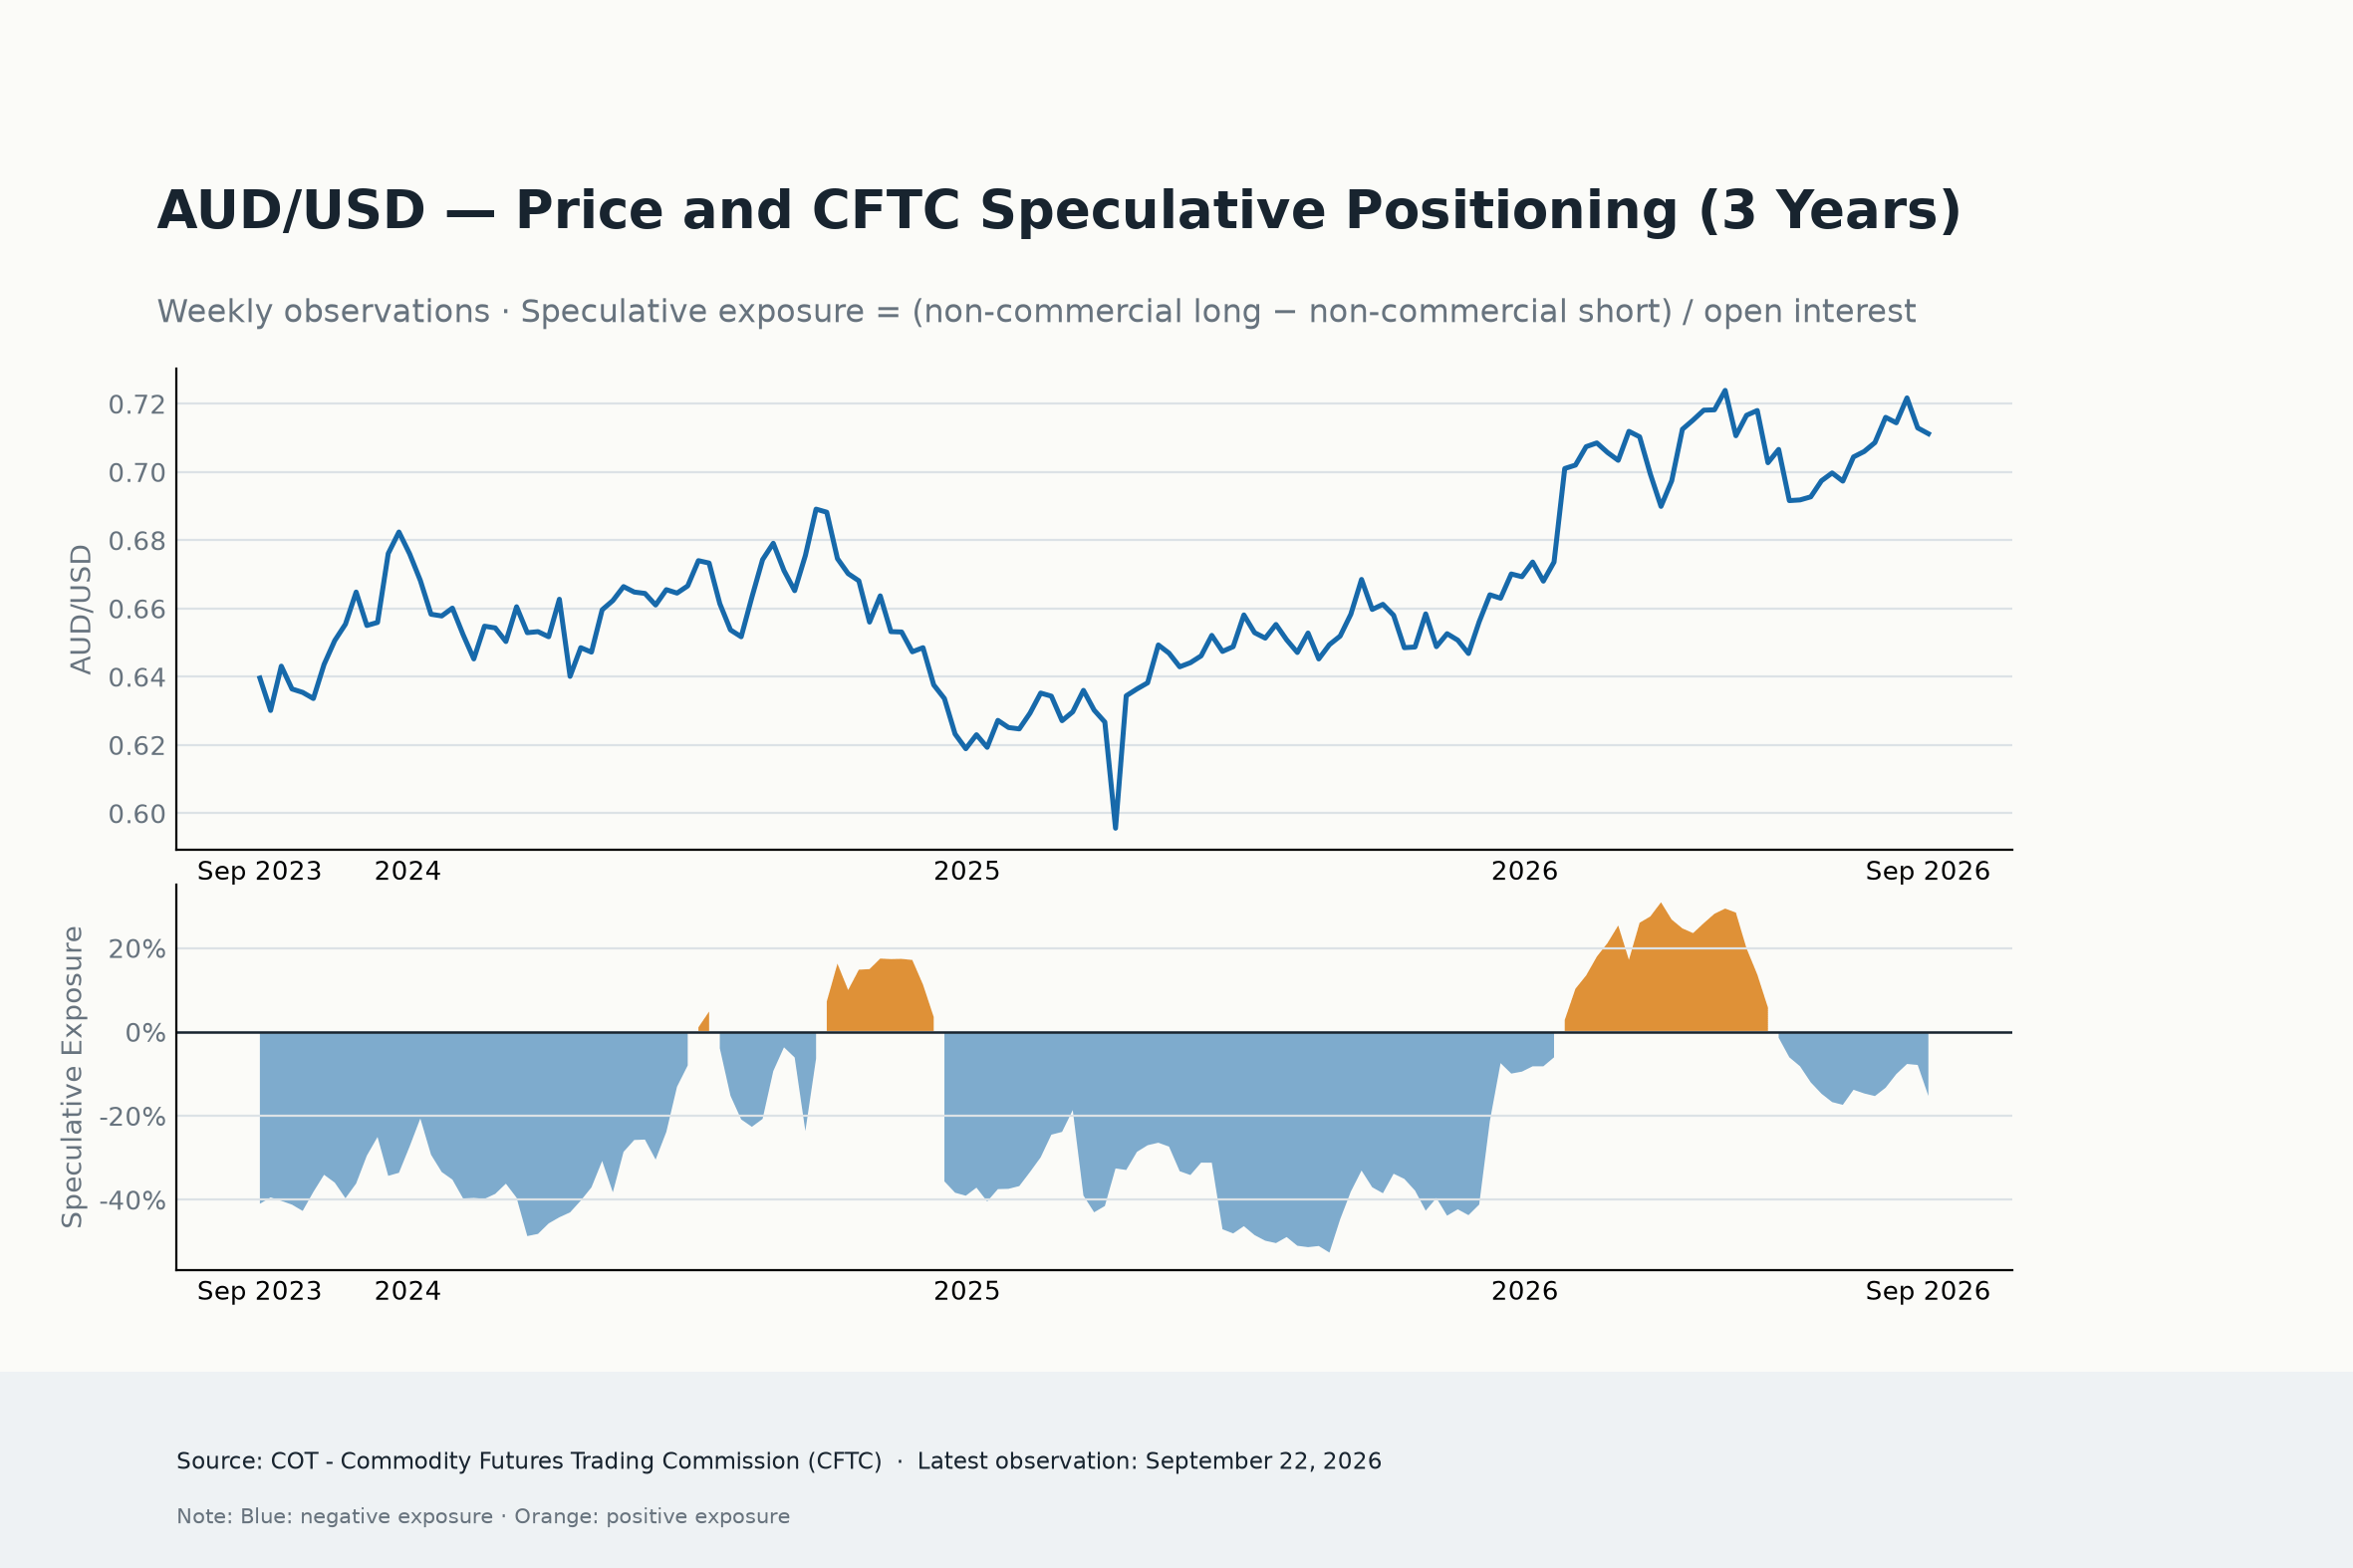
The latest Commodity Futures Trading Commission (CFTC) data suggest that non-commercial investors re-established bearish exposure toward the Aussie, reversing part of the short-covering seen over recent weeks. While positioning remains far from the extreme bearish levels reached earlier in the year, the latest report indicates growing caution toward the currency.
That said, speculators increased their net shorts to nearly 46.7K contracts, the largest in several weeks. The move marks a clear acceleration from the previous week's increase in shorts and suggests that investors have become more cautious towards the AUD following the recent stabilisation in positioning.
The sharp fall in speculative exposure to -15.3% reinforces that view. The decline reflects a much larger share of speculative positions being tilted to the short side, indicating that bearish conviction strengthened materially during the reporting week.
While the deterioration is stark, positioning indicators suggest sentiment has moved back into bearish territory but not to historical extremes.
The Speculative Exposure Percentile is 77.7, which means that the strength of the speculative bearishness is greater than that observed in about 3/4 of the observations. Meanwhile, the Net Position Percentile sits at 54.4, close to the middle of its historical range, suggesting that although shorts have increased, outright positioning remains relatively balanced compared with previous cycles.
This combination suggests investors have turned more negative on the AUD, but there is room for positioning to become materially more bearish if macro conditions deteriorate.
Also, medium-term momentum has turned negative, with the 4-week change moving back into negative territory at just over 2.3K contracts and reversing last week’s positive reading. This suggests that the broader trend has once again turned toward rebuilding short exposure rather than covering existing bearish positions.
One week’s worth of data does not indicate a new trend, but further increases in brief positioning would indicate that speculative sentiment is turning more bearish on the Australian currency.
Takeaway
This week's report points to a renewed bearish shift in speculators’ sentiment toward the Australian Dollar. Investors added fresh short positions, speculative exposure weakened significantly, and the 4-week trend slipped back into negative territory.
While positioning remains well short of historical extremes, the latest data suggest that market participants are becoming increasingly cautious on the AUD. Unless incoming domestic data or an improvement in global risk sentiment alters the macro backdrop, speculative flows may continue to favour the downside in the weeks ahead.
What could move AUD/USD next?
US Dollar dynamics, global risk sentiment, and geopolitical developments remain the main near-term drivers of AUD/USD.
In the meantime, the imminent RBA meeting will be the salient event on the domestic calendar, seconded by the release of the always relevant inflation figures due later in the week.
Beyond the immediate releases, the main risks include a sharper slowdown in China, a persistently cautious Fed, a deterioration in investor risk appetite or a change in the RBA’s current policy stance. Any of these developments could quickly alter the outlook for the Australian Dollar.
Technical analysis
In the daily chart, AUD/USD trades at 0.7027, maintaining a bearish near-term bias as it holds beneath the 55-day and 100-day simple moving averages (SMAs) at 0.7084 and 0.7068, respectively. Price is clinging just above the 200-day SMA at 0.7026, which acts as immediate underlying support, while the Relative Strength Index (RSI) at 35.68 hovers near oversold territory and the Average Directional Index (ADX) at 29.68 hints at a moderately directional, albeit weakening, downtrend.
On the topside, initial resistance is seen at the horizontal barrier at 0.7079, followed by the 100-day SMA at 0.7068 and the 55-day SMA at 0.7084, which together form a dense cap ahead of the higher resistance cluster around 0.7278/0.7283, with a more distant ceiling at 0.7661. On the downside, immediate support is provided by the 200-day SMA at 0.7026, ahead of the horizontal floor at 0.6833; a break lower would expose deeper support levels at 0.6660, 0.6593, 0.6414 and 0.6373.
(The technical analysis of this story was written with the help of an AI tool. Know more.)
External headwinds continue to cap upside
Some dark clouds continue to hover around the AUD’s near-term outlook.
Australia’s domestic backdrop compares favourably with that of many advanced economies, and the RBA is in no hurry to abandon its hawkish stance. These factors should somewhat contain the bearish impulse.
The recovery nevertheless remains vulnerable to renewed strength in the Greenback, persistent geopolitical uncertainty and a Chinese economy that is stabilising rather than accelerating.
The 200-day SMA remains the key level for the medium-term outlook. Holding above it preserves the constructive structure, but a convincing break above 0.7200 is necessary to further extend the bull run.
However, such a move would require the resumption of the downward trend in the Greenback, stronger demand for risk-sensitive assets, additional cooling in US inflation, or a (less likely) dovish shift from the Fed.
Until then, external forces are likely to exert more influence over the Australian Dollar than domestic fundamentals.
RBA FAQs
The Reserve Bank of Australia (RBA) sets interest rates and manages monetary policy for Australia. Decisions are made by a board of governors at 11 meetings a year and ad hoc emergency meetings as required. The RBA’s primary mandate is to maintain price stability, which means an inflation rate of 2-3%, but also “..to contribute to the stability of the currency, full employment, and the economic prosperity and welfare of the Australian people.” Its main tool for achieving this is by raising or lowering interest rates. Relatively high interest rates will strengthen the Australian Dollar (AUD) and vice versa. Other RBA tools include quantitative easing and tightening.
While inflation had always traditionally been thought of as a negative factor for currencies since it lowers the value of money in general, the opposite has actually been the case in modern times with the relaxation of cross-border capital controls. Moderately higher inflation now tends to lead central banks to put up their interest rates, which in turn has the effect of attracting more capital inflows from global investors seeking a lucrative place to keep their money. This increases demand for the local currency, which in the case of Australia is the Aussie Dollar.
Macroeconomic data gauges the health of an economy and can have an impact on the value of its currency. Investors prefer to invest their capital in economies that are safe and growing rather than precarious and shrinking. Greater capital inflows increase the aggregate demand and value of the domestic currency. Classic indicators, such as GDP, Manufacturing and Services PMIs, employment, and consumer sentiment surveys can influence AUD. A strong economy may encourage the Reserve Bank of Australia to put up interest rates, also supporting AUD.
Quantitative Easing (QE) is a tool used in extreme situations when lowering interest rates is not enough to restore the flow of credit in the economy. QE is the process by which the Reserve Bank of Australia (RBA) prints Australian Dollars (AUD) for the purpose of buying assets – usually government or corporate bonds – from financial institutions, thereby providing them with much-needed liquidity. QE usually results in a weaker AUD.
Quantitative tightening (QT) is the reverse of QE. It is undertaken after QE when an economic recovery is underway and inflation starts rising. Whilst in QE the Reserve Bank of Australia (RBA) purchases government and corporate bonds from financial institutions to provide them with liquidity, in QT the RBA stops buying more assets, and stops reinvesting the principal maturing on the bonds it already holds. It would be positive (or bullish) for the Australian Dollar.
Author

Pablo Piovano
FXStreet
Born and bred in Argentina, Pablo has been carrying on with his passion for FX markets and trading since his first college years.
















