Australian Dollar Price Forecast: Bulls need more conviction
- AUD/USD has started the week in a vacillating mood, trading below 0.7150.
- The US Dollar gathers fresh traction supported by Fed rate hike bets.
- The Trump-Xi Summit on September 24 is expected to dominate the week.
The Australian Dollar (AUD) has traded in an unconvincing fashion on Monday, prompting AUD/USD to alternate gains with losses in the low 0.7100s while struggling to add continuation to the recent two-day recovery.
Indeed, the pair’s lack of clear direction has come amid an auspicious beginning of the week for the US Dollar (USD), as investors continued to pencil in further tightening by the federal Reserve (Fed), while extra instability on the geopolitical front (this time from a potential Russia-NATO front) has reinforced the demand for the safe haven space.
Looking at the broader picture, however, the pair’s current positive stance still appears propped up by the Reserve Bank of Australia’s (RBA) hawkish policy bias and elevated inflation in Oz.
Australia’s growth holds up, but momentum softens
Australia’s economy continues to compare favourably with many of its G10 peers, supported by domestic demand and positive economic growth. Persistent inflation also supports the RBA’s cautious, data-dependent policy stance.
Business activity remained in expansionary territory in August after final Purchasing Managers’ Index (PMI) readings showed the Manufacturing index unchanged at 52.0, while the Services index edged a tad down to 53.2.
Trade data provided another positive signal: Australia recorded an A$1.923 billion surplus in July, adding to the A$2.341 billion surplus registered in June.
Growth figures were less encouraging, however. Indeed, the Gross Domestic Product (GDP) expanded by 0.4% QoQ in the second quarter of 2026, up from 0.3%, while annual growth came in at 2.1%, down from the previous 2.5% yearly expansion.
The labour market also showed signs of losing momentum in July. The Unemployment Rate rose to 4.5%, while Employment Change declined by 15.8K following a revised increase of 80.3K in the previous month.
Inflation remains the main constraint after July data showed price pressures running well above the RBA’s 2%-3% target band, suggesting that the return to target could remain uneven and prolonged. That said, the headline inflation eased to 3.5% in July (from 3.8%), while underlying price pressures tracked by the Trimmed Mean held steady at 3.6%.
The Melbourne Institute’s Consumer Inflation Expectations measure reinforced that view, holding steady at 4.9% in September.
The figures leave the RBA’s inflation task incomplete. Policymakers expect inflation to return to target only in early 2028, keeping the emphasis on patience rather than an imminent policy pivot.
China stabilises without providing a fresh boost
China is providing stability for the Australian economy, but not the growth impulse that has supported the Australian Dollar during previous expansions.
The Chinese economy grew by 4.3% YoY in the April-June period, while Industrial Production growth regained traction, expanding by 5.2% YTD, and the trade surplus widened to $119.1 billion in July, supported by decent increases in both imports and exports. However, on the downside, consumer spending remained sluggish after Retail Sales rose by only 0.4 % from a year earlier.
In addition, business surveys presented a mixed picture: the National Bureau of Statistics reported that the Manufacturing PMI improved to 49.8 in August from 49.2, while the Services PMI remained unchanged at 49.0. On the other hand, private measures like RatingDog remain in expansionary territory, with Manufacturing at 51.5 (from 50.9) and Services at 51.4 (from 50.4).
Disinflationary pressures seem to have taken a breather in August, with the CPI gaining 0.8% YoY, up from 0.5%, while prices rose by 0.4% on a monthly basis. Producer Prices rose by 3.8% over the previous twelve months, down from the 3.5% increase recorded in the previous month.
The People’s Bank of China (PBoC) left its Loan Prime Rates unchanged early on Monday, maintaining the one-year rate at 3.00% and the five-year rate at 3.50%.
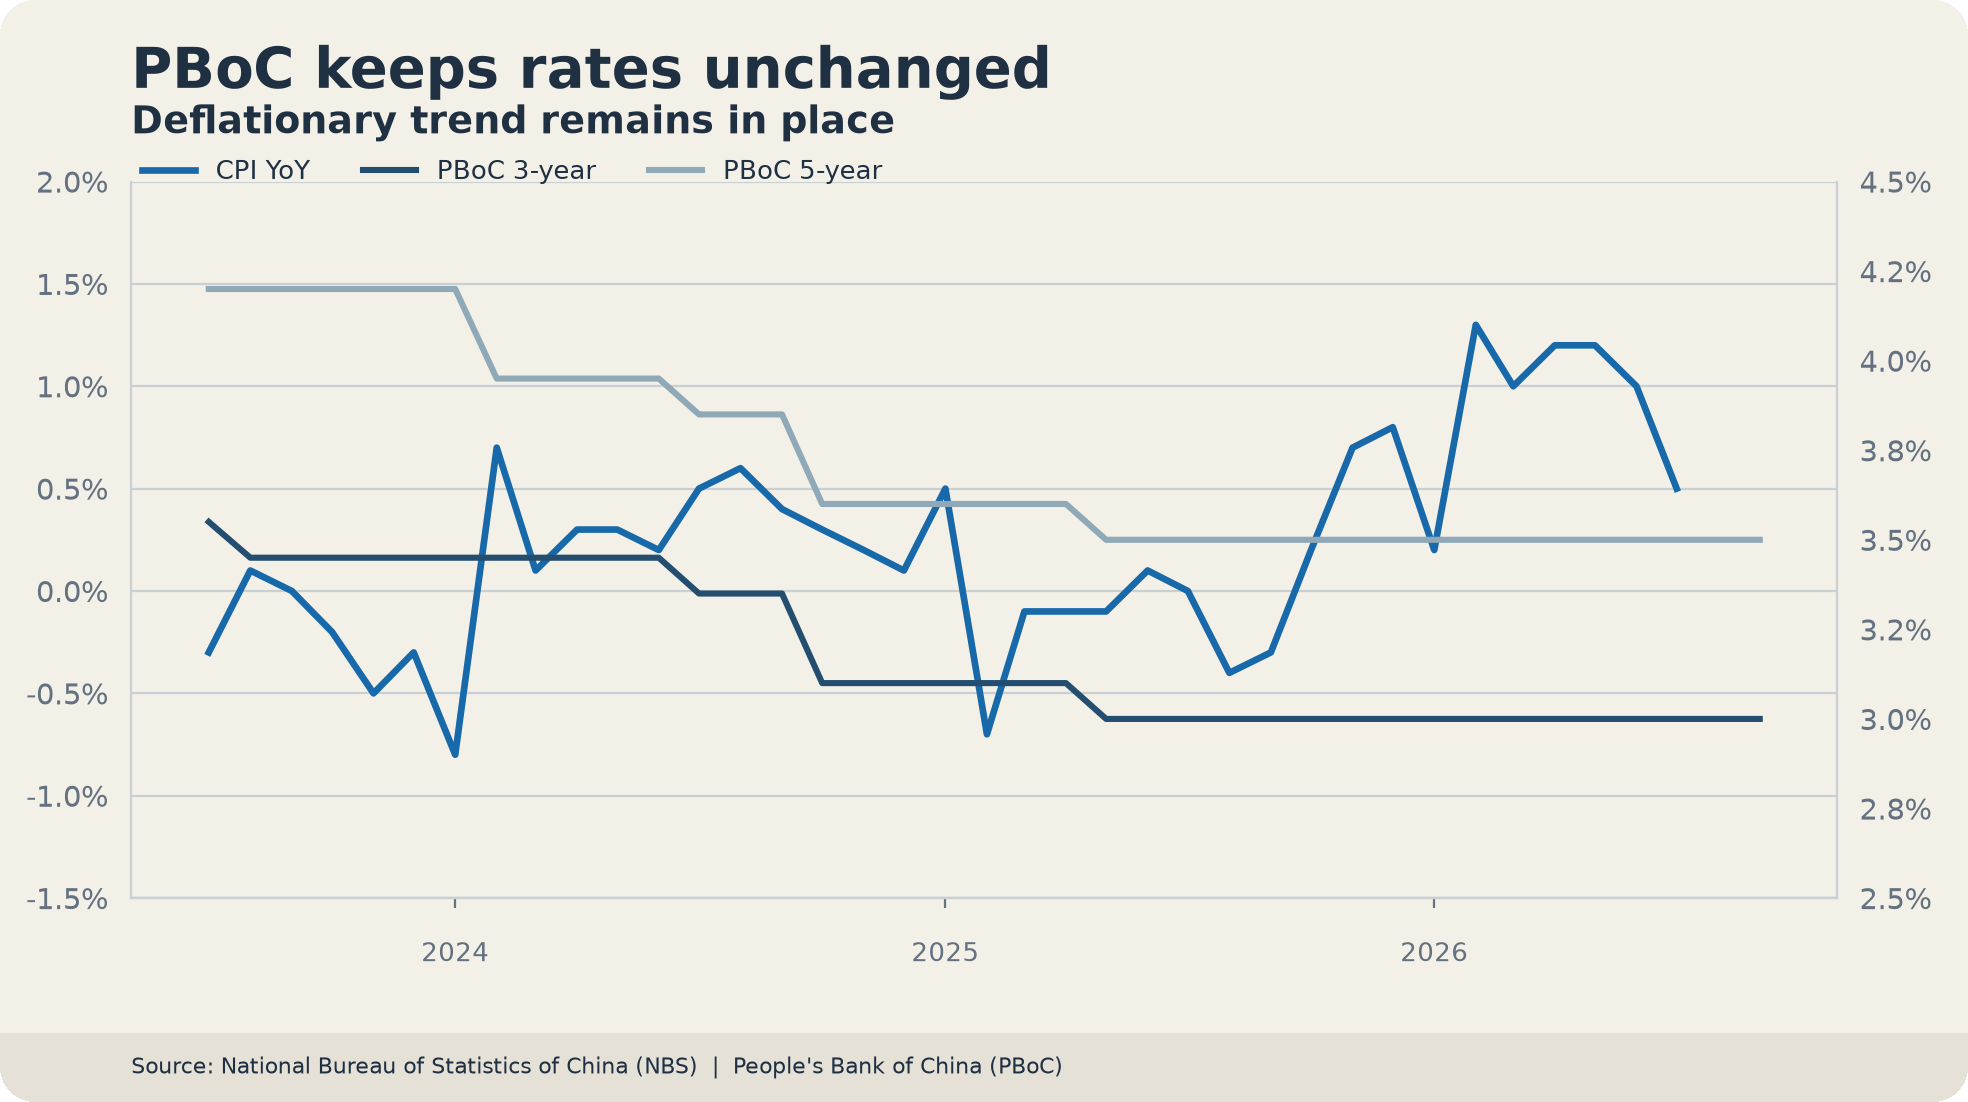
China is therefore neither providing a major boost nor creating a significant drag. Unless the data reveal a clearer acceleration or deterioration, its influence on AUD/USD is likely to remain limited.
RBA keeps the door open to further tightening
The RBA left its Official Cash Rate (OCR) unchanged on August 11 and retained a clear tightening bias, citing above-target inflation and upside risks to the outlook. The decision to hold rates was unanimous.
The Minutes maintained that cautious but hawkish stance. Several officials warned that inflation risks could materialise, which would leave the Board ready to raise rates. Potential sources of pressure include increased investment in data centres, cost pass-through and higher energy prices.
Policymakers discussed a 25-basis-point increase but concluded that the current policy setting was sufficiently restrictive. They also acknowledged more balanced risks, including falling house prices and the possibility that inflation could decline without causing significant damage to employment.
Fresh GDP, labour-market and inflation figures are expected before the September meeting, leaving policy dependent on the incoming data.
So far, investors are pricing in just over 41 basis points of tightening by year-end and expect the RBA to hike the OCR by 25 basis points at its meeting on September 29.
AUD/USD outlook: 0.7200 remains the key test
Base case
The medium-term outlook remains tilted towards further gains, as long as AUD/USD stays above its 200-day Simple Moving Average (SMA), which is currently around 0.7015.
Further progress will still require a quite strong catalyst: without a sustained improvement in risk appetite or continued US Dollar weakness, upward momentum could begin to fade.
Bull case
A stronger risk-on environment and a convincing break above 0.7200 would bring the 2026 high near 0.7280 into view.
Beyond that level, resistance emerges at the 0.7300 round level, followed by the 2022 ceiling at 0.7593.
Bear case
A deterioration in global risk sentiment, renewed strength in the Greenback, or further weakness in Chinese data could spark fresh selling interest in spot .
Initial support is at the September floor at 0.7074 (September 16), followed by the provisional 55-day SMA near 0.7070. The more important level remains the 200-day SMA.
However, a breach below that area would weaken the broader constructive structure and increase the risk of a deeper short-term decline.
Bearish conviction rebuilds
Speculative bearish positioning in the Australian Dollar strengthened in the week ending September 15, according to the Commodity Futures Trading Commission (CFTC). That said, net shorts increased to nearly 39K contracts, reversing part of the previous week’s improvement. However, the 4-week change increased to around 5.2K contracts, showing that the broader positioning trend remains less negative despite the latest setback.
In addition, open interest extended its climb, this time hitting around 494.1K contracts. The move suggests that traders are establishing new bearish positions as net shorts deepen and participation increases, rather than just unwinding prior longs. This suggests that conviction behind the negative AUD bias has picked up again.
Further data showed the speculative exposure edged lower to -7.9% from -7.7%, while its percentile remained elevated at 83.9. Bearish exposure is therefore historically significant, although the Net Position Percentile of 68.1 indicates that positioning is not yet at an extreme. The small change in exposure also suggests that the increase in open interest has broadly balanced out.
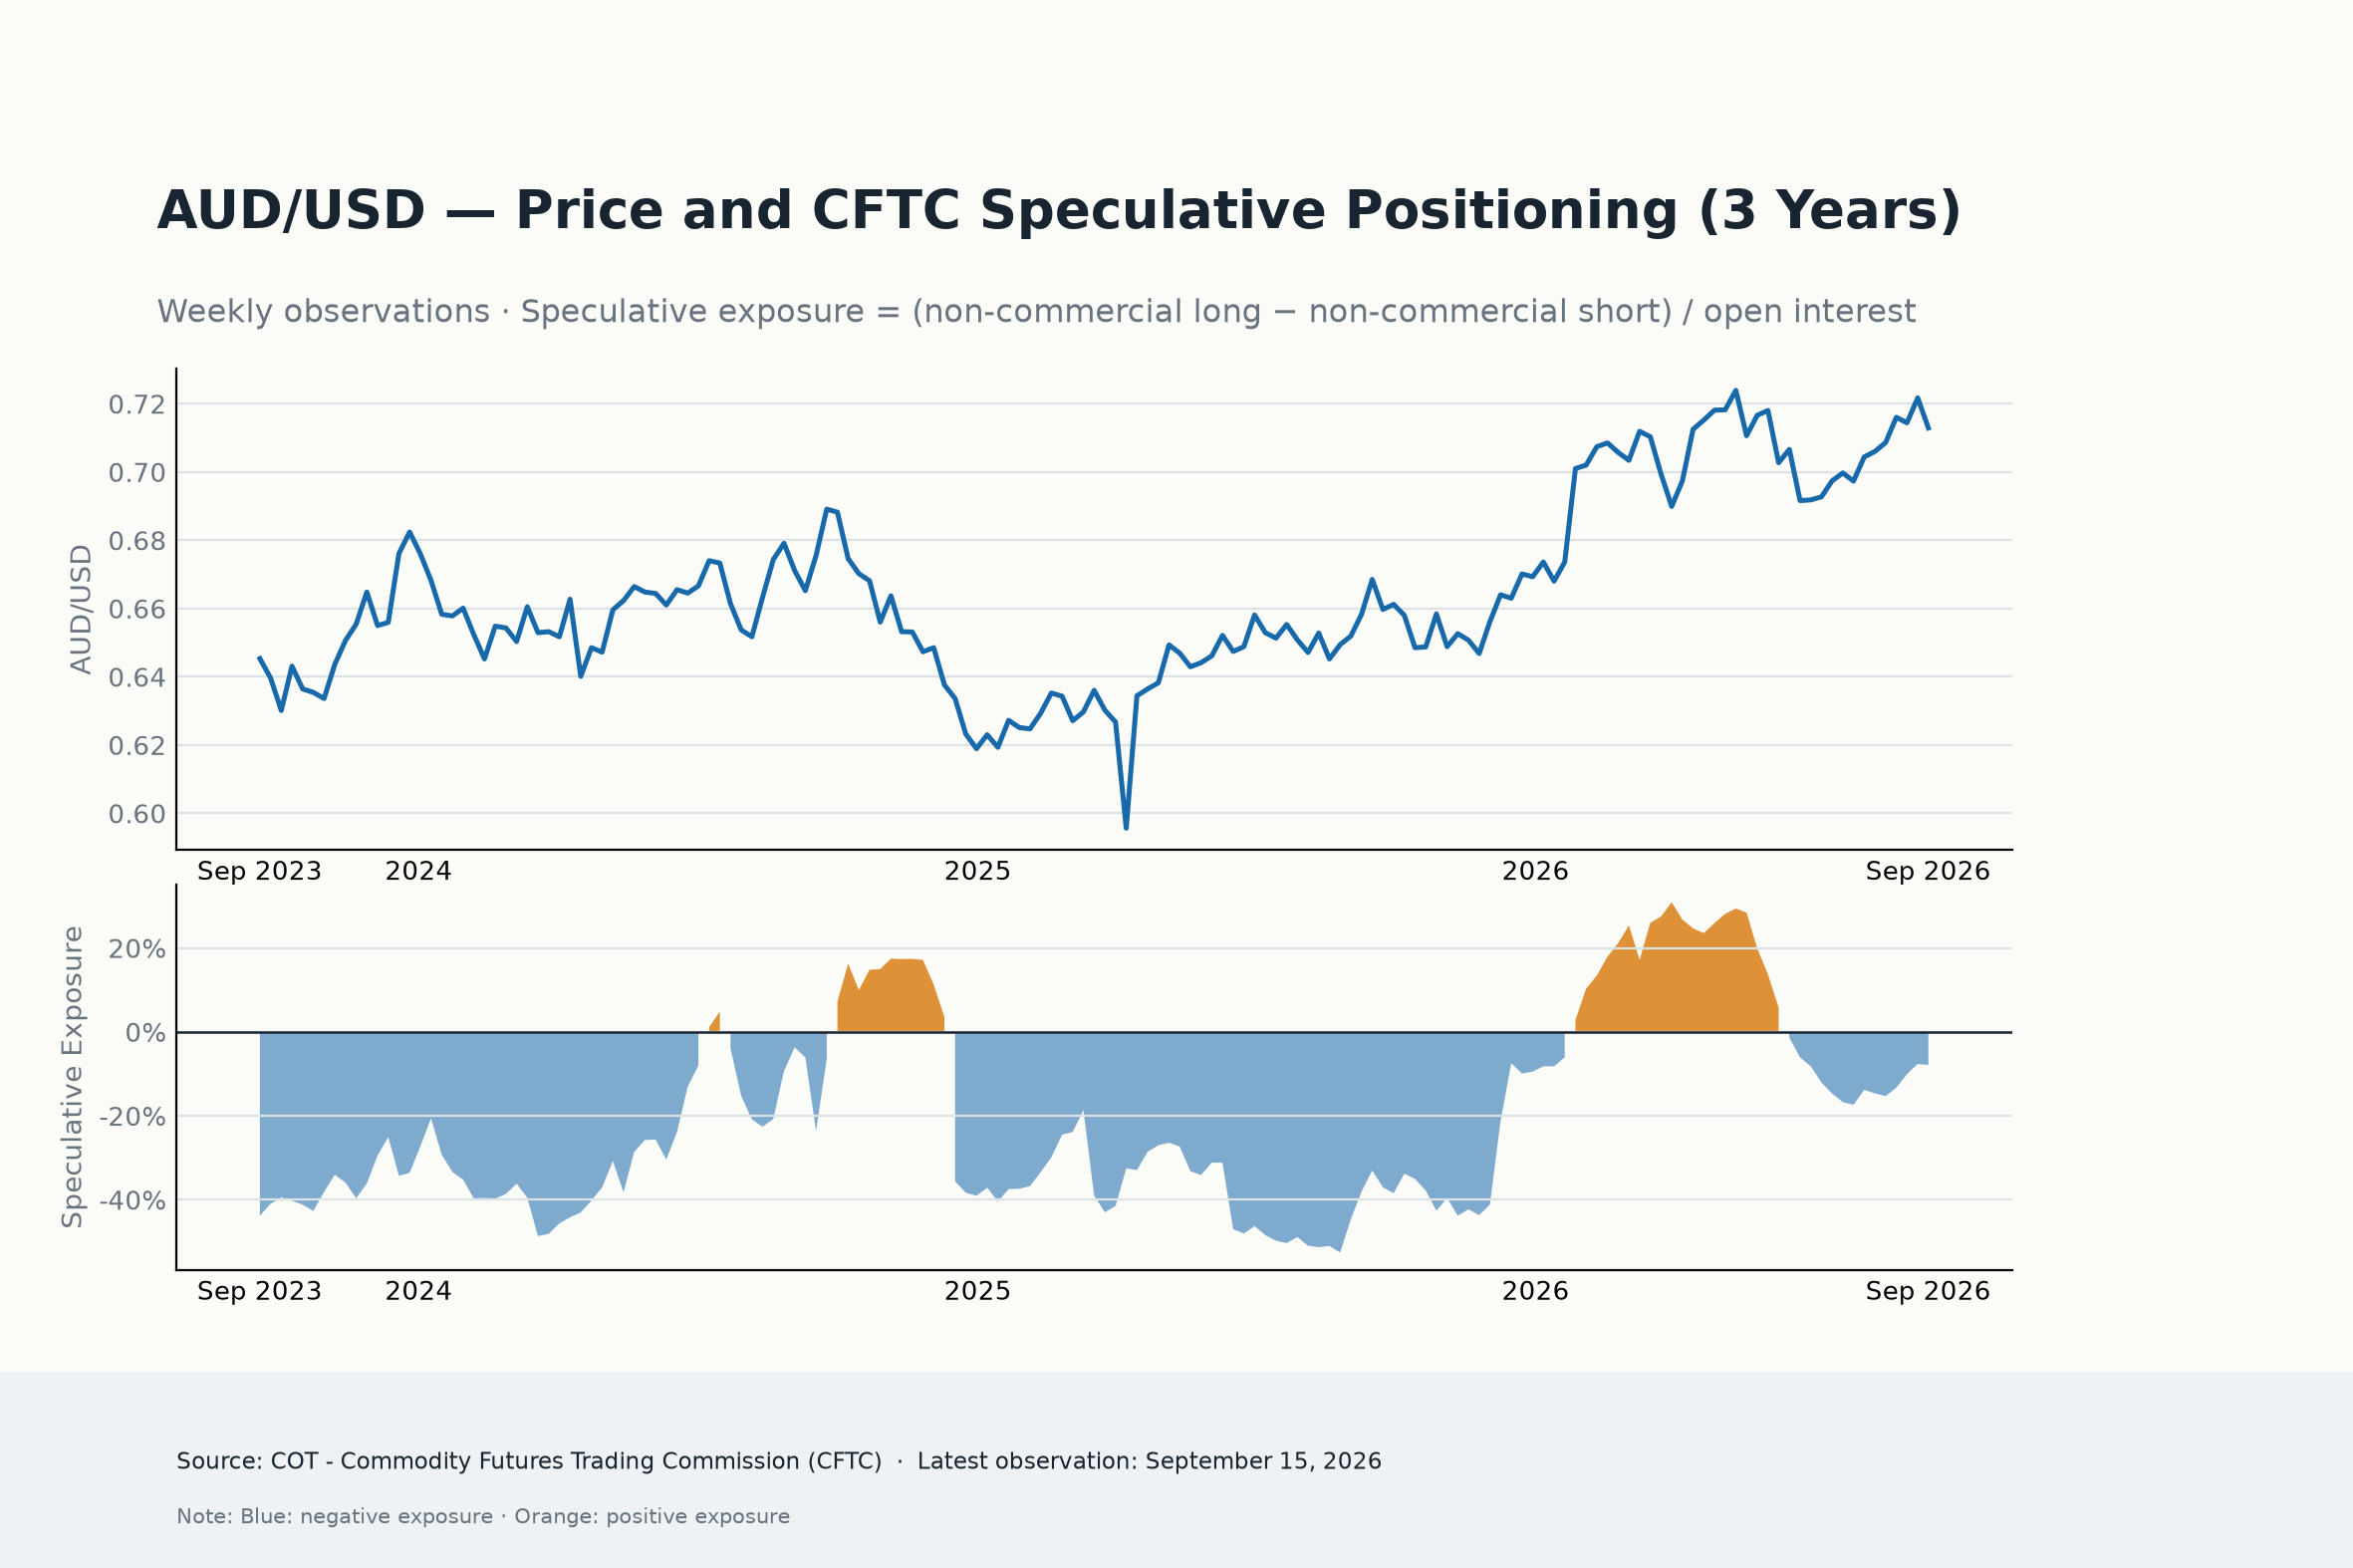
Overall, the AUD’s bearish bias remains intact, but the wider trend has not fully reversed. Fresh short-building is a negative signal, yet the positive 4-week change indicates that bearish momentum is not accelerating decisively. For now, the data point to renewed pressure on the Aussie rather than a fully fledged bearish regime.
What to watch next for the Australian Dollar
US Dollar dynamics, global risk sentiment and geopolitical developments remain the main near-term drivers of AUD/USD.
Meanwhile, next on tap on the domestic docket will be the release of the preliminary S&P Global PMIs on September 23, which should add further details on how the domestic business activity fared this month.
Apart from the data space, global markets will closely monitor the upcoming Trump-Xi Summit later in the week, with global trade and tariffs expected to be on top of the agenda.
Beyond the immediate releases, the main risks include a sharper slowdown in China, a persistently cautious Fed, a deterioration in investor risk appetite or a change in the RBA’s current policy stance. Any of these developments could quickly alter the outlook for the Australian Dollar.
Technical landscape
In the daily chart, AUD/USD trades at 0.7126, holding above the clustered 55-day, 100-day and 200-day simple moving averages (SMAs) between 0.7074 and 0.7015, which reinforces a constructive near-term bias. The Relative Strength Index (14) around 48 and a subdued Average Directional Index near 22 suggest consolidative price action rather than a strong trend, hinting that bulls may need a fresh catalyst to challenge overhead barriers.
On the downside, initial support is located at the recent horizontal floor at 0.7079, backed by the nearby 100-day and 55-day SMAs at 0.7078 and 0.7074, while deeper demand is seen at 0.7015 and then 0.6833. On the topside, immediate resistance is aligned at 0.7278 and 0.7283, ahead of a more distant hurdle at 0.7661, and a sustained break above this zone would open the way for a broader AUD/USD advance.
(The technical analysis of this story was written with the help of an AI tool. Know more.)
External risks complicate the bullish outlook
The broader picture continues to favour the AUD.
Australia’s domestic backdrop compares favourably with that of many advanced economies, and the RBA is in no hurry to abandon its hawkish stance.
The recovery nevertheless remains vulnerable to renewed strength in the Greenback, persistent geopolitical uncertainty and a Chinese economy that is stabilising rather than accelerating.
The 200-day SMA remains the key level for the medium-term outlook. Holding above it preserves the constructive structure, but a convincing break above 0.7200 will probably This would require a more convincing sell-off of the Greenback, stronger demand for risk-sensitive assets, additional cooling in US inflation, or a (less likely) dovish shift from the Fed.
Until then, external forces are likely to exert more influence over the Australian Dollar than domestic fundamentals.
RBA FAQs
The Reserve Bank of Australia (RBA) sets interest rates and manages monetary policy for Australia. Decisions are made by a board of governors at 11 meetings a year and ad hoc emergency meetings as required. The RBA’s primary mandate is to maintain price stability, which means an inflation rate of 2-3%, but also “..to contribute to the stability of the currency, full employment, and the economic prosperity and welfare of the Australian people.” Its main tool for achieving this is by raising or lowering interest rates. Relatively high interest rates will strengthen the Australian Dollar (AUD) and vice versa. Other RBA tools include quantitative easing and tightening.
While inflation had always traditionally been thought of as a negative factor for currencies since it lowers the value of money in general, the opposite has actually been the case in modern times with the relaxation of cross-border capital controls. Moderately higher inflation now tends to lead central banks to put up their interest rates, which in turn has the effect of attracting more capital inflows from global investors seeking a lucrative place to keep their money. This increases demand for the local currency, which in the case of Australia is the Aussie Dollar.
Macroeconomic data gauges the health of an economy and can have an impact on the value of its currency. Investors prefer to invest their capital in economies that are safe and growing rather than precarious and shrinking. Greater capital inflows increase the aggregate demand and value of the domestic currency. Classic indicators, such as GDP, Manufacturing and Services PMIs, employment, and consumer sentiment surveys can influence AUD. A strong economy may encourage the Reserve Bank of Australia to put up interest rates, also supporting AUD.
Quantitative Easing (QE) is a tool used in extreme situations when lowering interest rates is not enough to restore the flow of credit in the economy. QE is the process by which the Reserve Bank of Australia (RBA) prints Australian Dollars (AUD) for the purpose of buying assets – usually government or corporate bonds – from financial institutions, thereby providing them with much-needed liquidity. QE usually results in a weaker AUD.
Quantitative tightening (QT) is the reverse of QE. It is undertaken after QE when an economic recovery is underway and inflation starts rising. Whilst in QE the Reserve Bank of Australia (RBA) purchases government and corporate bonds from financial institutions to provide them with liquidity, in QT the RBA stops buying more assets, and stops reinvesting the principal maturing on the bonds it already holds. It would be positive (or bullish) for the Australian Dollar.
Author

Pablo Piovano
FXStreet
Born and bred in Argentina, Pablo has been carrying on with his passion for FX markets and trading since his first college years.















