USD/INR jumps ahead of US PMI data
- Indian Rupee edges lower in Tuesday’s early European session.
- Indian foreign inflows and lower crude oil prices might support the INR.
- Investors will focus on the US ISM Manufacturing PMI, which is due later on Tuesday.

The Indian Rupee (INR) weakens on Tuesday, pressured by the recovery of the Greenback. The positive Indian equity market, the inflow of foreign funds and a decline in crude oil prices could limit the INR’s losses. However, the increased US Dollar (USD) demand by the importer, and safe-haven flows ahead of the key US labor market data, might weigh on the local currency.
The US ISM Manufacturing Purchasing Managers Index (PMI) will be released on Tuesday ahead of the Indian August HSBC Services PMI. All eyes will be on the US labor market reports on Friday, including the Nonfarm Payrolls (NFP), Unemployment Rate and Average Hourly Earnings for August. The Federal Reserve (Fed) Chair Jerome Powell's comments at Jackson Hole last month have made this Friday's NFP report more significant than usual. A weaker-than-expected outcome could trigger the market to price in a larger rate cut, exerting selling pressure on the USD.
Daily Digest Market Movers: Indian Rupee remains on the defensive amid global factors
- The HSBC India Manufacturing Purchasing Managers Index (PMI) eased to a three-month low at 57.5 in August. This figure came in weaker than the expectations and the previous reading of 57.9.
- “New orders and output also mirrored the headline trend, with some panellists citing fierce competition as a reason for slowdown," noted Pranjul Bhandari, chief India economist at HSBC.”
- HSBC India Services PMI is estimated to improve to 60.4 in August from 60.3 in July.
- The US ISM Manufacturing PMI for August is projected to rise to 47.5 in August versus 46.8 prior, while the Services PMI is forecasted to ease to 51.1 in August from 51.4 in July.
- The market currently expects the Fed to cut interest rates by 25 basis points (bps) in September, pricing in odds of nearly 69%, according to the CME FedWatch tool.
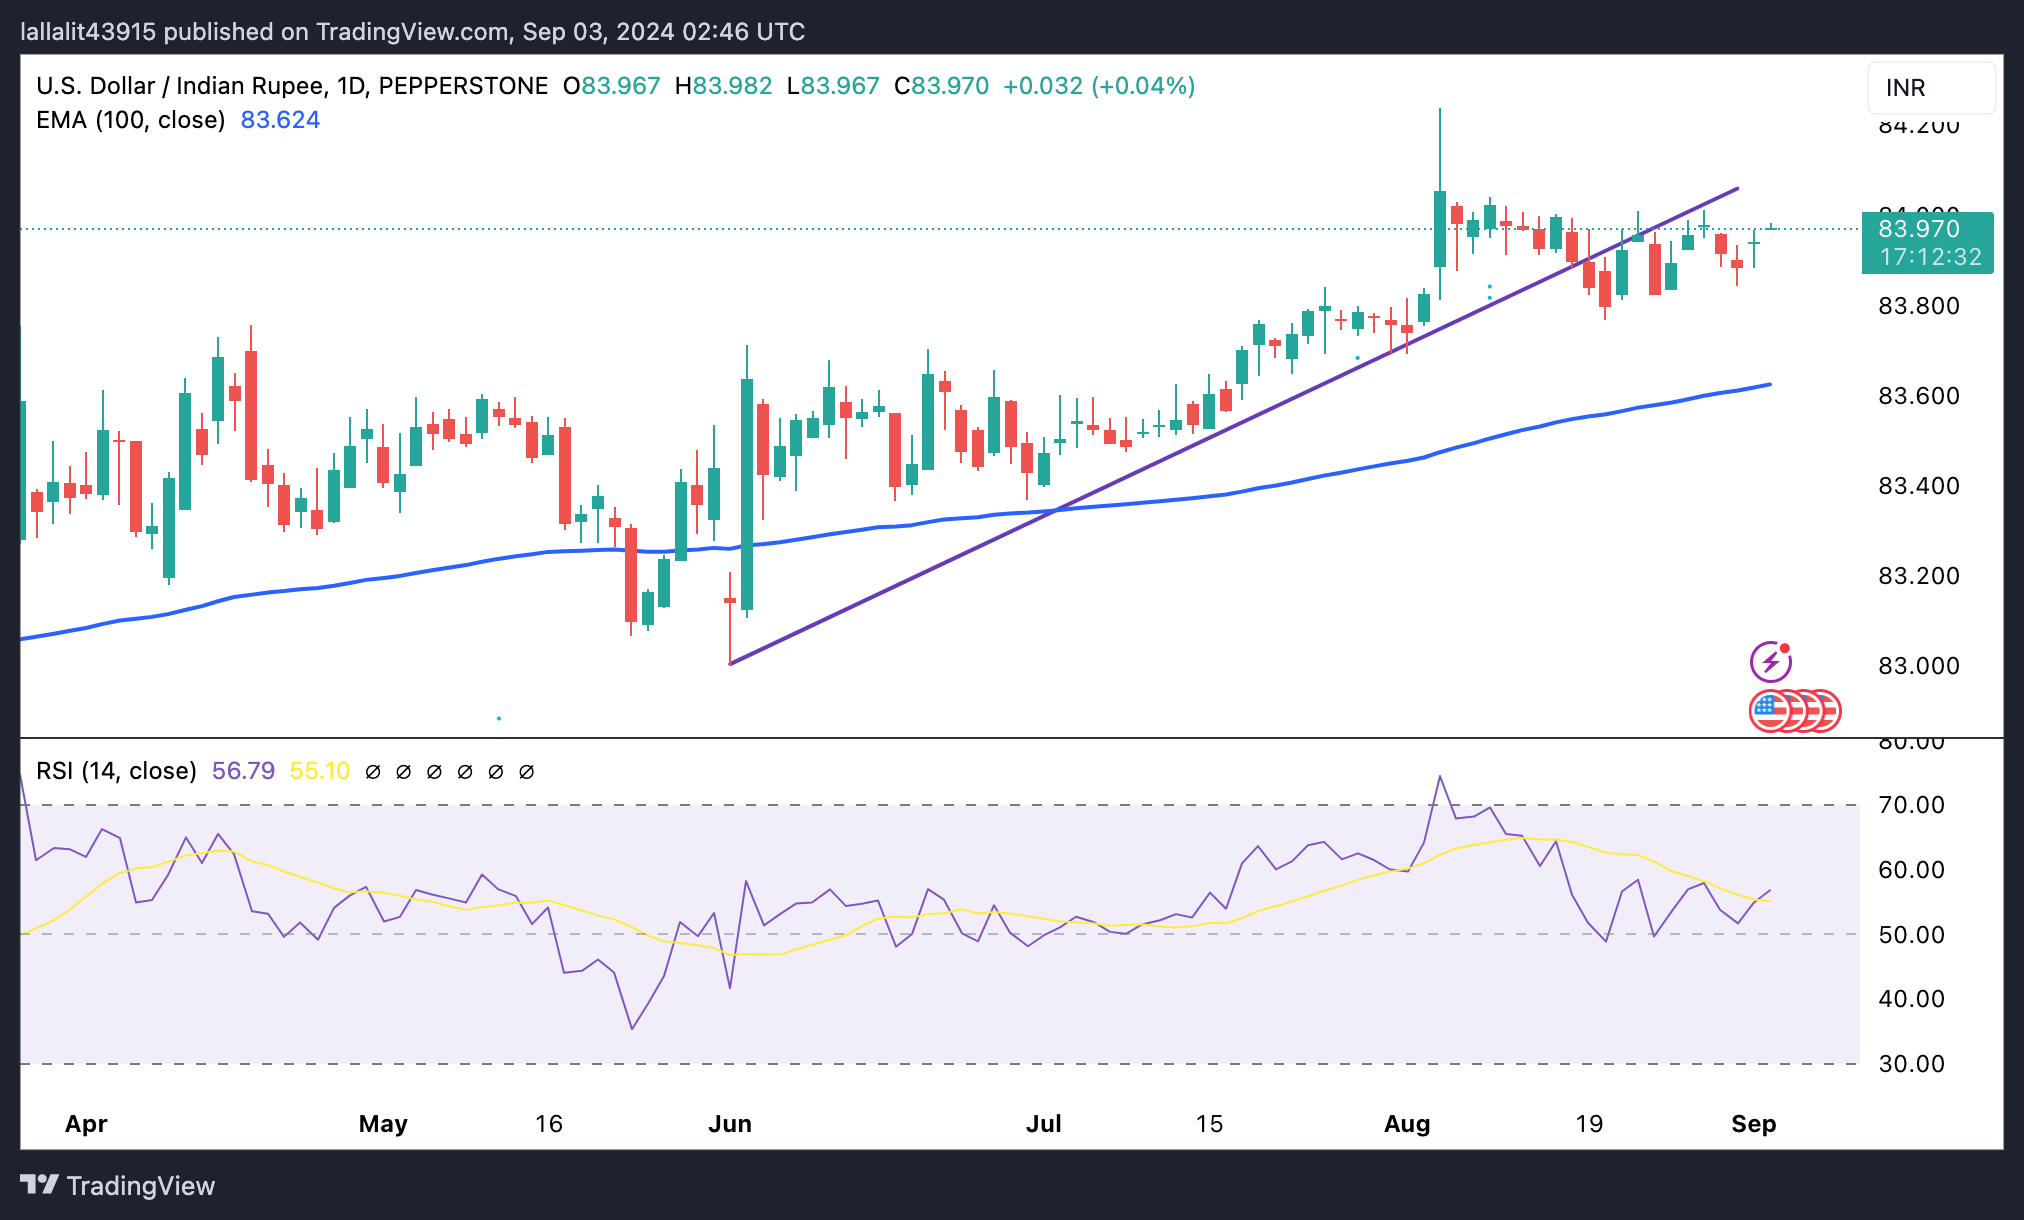
Technical Analysis: USD/INR in consolidative mode, longer-term bullish potential intact
The Indian Rupee trades on a softer note on the day. The USD/INR pair keeps the bullish vibe on the daily timeframe, characterized by the price holding above the key 100-day Exponential Moving Average (EMA) and the 14-day Relative Strength Index (RSI) standing above the midline.
The potential upside barrier for USD/INR is seen at the 84.00 psychological figure. Any follow-through buying above this level could expose 84.50.
In the bearish case, the first downside target is located at 83.84, the low of August 30. Further south, the next cushion level emerges at the 100-day EMA at 83.62.
Indian Rupee FAQs
The Indian Rupee (INR) is one of the most sensitive currencies to external factors. The price of Crude Oil (the country is highly dependent on imported Oil), the value of the US Dollar – most trade is conducted in USD – and the level of foreign investment, are all influential. Direct intervention by the Reserve Bank of India (RBI) in FX markets to keep the exchange rate stable, as well as the level of interest rates set by the RBI, are further major influencing factors on the Rupee.
The Reserve Bank of India (RBI) actively intervenes in forex markets to maintain a stable exchange rate, to help facilitate trade. In addition, the RBI tries to maintain the inflation rate at its 4% target by adjusting interest rates. Higher interest rates usually strengthen the Rupee. This is due to the role of the ‘carry trade’ in which investors borrow in countries with lower interest rates so as to place their money in countries’ offering relatively higher interest rates and profit from the difference.
Macroeconomic factors that influence the value of the Rupee include inflation, interest rates, the economic growth rate (GDP), the balance of trade, and inflows from foreign investment. A higher growth rate can lead to more overseas investment, pushing up demand for the Rupee. A less negative balance of trade will eventually lead to a stronger Rupee. Higher interest rates, especially real rates (interest rates less inflation) are also positive for the Rupee. A risk-on environment can lead to greater inflows of Foreign Direct and Indirect Investment (FDI and FII), which also benefit the Rupee.
Higher inflation, particularly, if it is comparatively higher than India’s peers, is generally negative for the currency as it reflects devaluation through oversupply. Inflation also increases the cost of exports, leading to more Rupees being sold to purchase foreign imports, which is Rupee-negative. At the same time, higher inflation usually leads to the Reserve Bank of India (RBI) raising interest rates and this can be positive for the Rupee, due to increased demand from international investors. The opposite effect is true of lower inflation.
Author

Lallalit Srijandorn
FXStreet
Lallalit Srijandorn is a Parisian at heart. She has lived in France since 2019 and now becomes a digital entrepreneur based in Paris and Bangkok.

















