|

USD/CAD marches steady around 1.2880, after US manufacturing data

  • The USD/CAD ended the week almost flat amidst a volatile’s Friday session.
  • Canada’s May GDP contracted by 0.2%, on its preliminary reading, a headwind for the CAD.
  • US manufacturing data showed signs of slowing down; will the Fed slow its tightening pace?

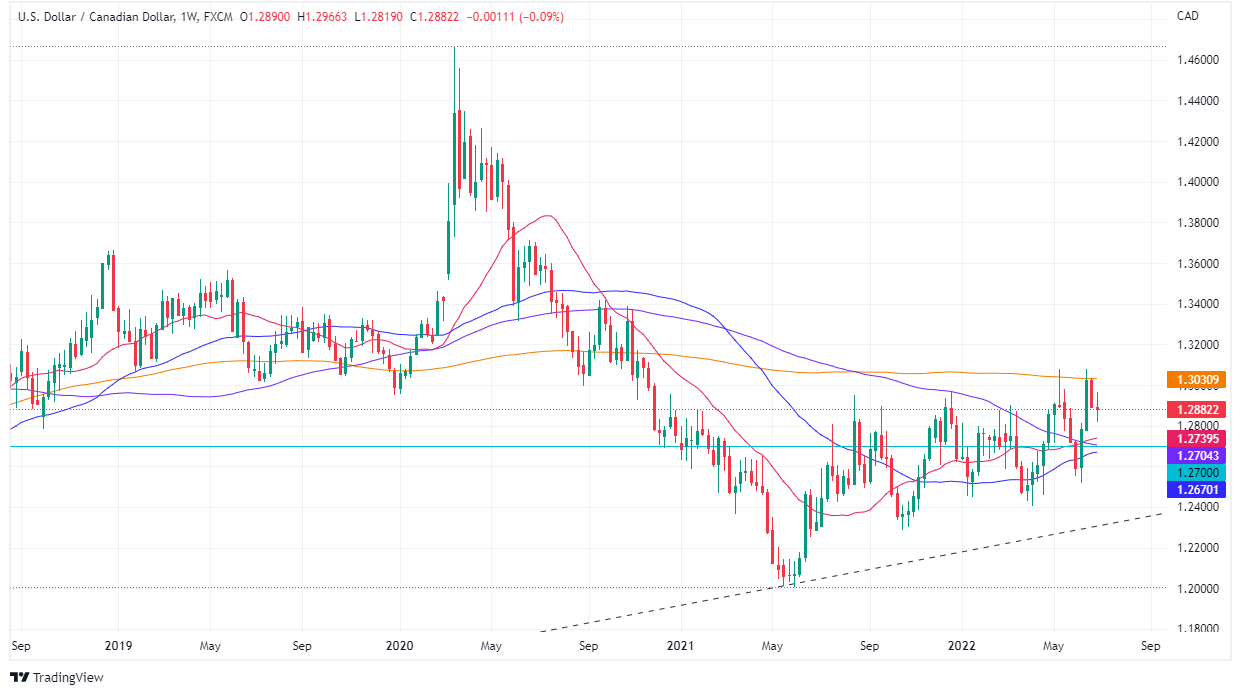
The USD/CAD pares some of Thursday’s losses after reaching a weekly high of around 1.2960s but retraced below 1.2900 as the greenback weakened ahead into a long weekend, courtesy of the US Independence day. At 1.2882, the USD/CAD records minimal gains of 0.08% and finishes the week with losses of 0.09%.

Sentiment shifts, and the USD/CAD retreats from weekly highs to familiar levels

US equities finished with solid gains after the S&P 500 slumped by 20% since its peak in 2022. US manufacturing data, as reported by the Institute for Supply Management, released June’s Manufacturing PMI at 53.0, lower than the 54.9 expected prior at 56.1. Investors’ reaction was a counter-cyclical, buying the US dollar as a safe-haven play as fears of a US and a global recession increased.

On the USD/CAD side, the pair rallied sharply, from around 1.2900s to 1.2966, amidst falling US Treasury yields, as bond traders bought US Treasuries, which sent short-term US bond yields plunging more than ten basis points, in the case of 2s, 5s, and 10s. The US 10-year benchmark note finalized around 2.889%, down twelve basis points and 70 bps from the 2022 peak near 3.5%.

Data-wise, during the week, the Canadian docket revealed a GDP contraction of 0.2% MoM on May’s preliminary reading, while April was downward revised from 0.7% to 0.3% MoM. The data could deter the Bank of Canada (BoC) from hiking rates aggressively, though, at the time of writing, Short Term Interest Rates (STIRs) markets have priced in a 92% chance of a 75 bps rate hike in the July 13 meeting.

On the US front, June’s Consumer Confidence reported by the Conference Board, downtick towards 98.7, missing expectations of 100.4, and trailed May’s 103.2. Furthermore, US inflation, as measured by the Personal Consumption Expenditure (PCE), and the Fed’s favorite gauge of inflation for May, rose by 6.3% YoY, lower than the 6.7% estimated. Meanwhile, the so-called core PCE, excluding volatile items, rose by 4.7% YoY, lower than foreseen and less than April’s 4.9%.

The week ahead, the Canadian economic calendar will feature S&P Global Manufacturing PMIs and Employment data. On the US front, the docket will reveal the ISN Non-Manufacturing PMI for June, the US Federal Reserve’s last meeting minutes, and the US Nonfarm Payrolls report for June.

USD/CAD Weekly chart
USD/CAD Key Technical Levels

USD/CAD

Overview
Today last price1.2882
Today Daily Change0.0035
Today Daily Change %0.27
Today daily open1.2873
 
Trends
Daily SMA201.2836
Daily SMA501.2826
Daily SMA1001.2737
Daily SMA2001.268
 
Levels
Previous Daily High1.2934
Previous Daily Low1.2861
Previous Weekly High1.3039
Previous Weekly Low1.289
Previous Monthly High1.3079
Previous Monthly Low1.2518
Daily Fibonacci 38.2%1.2889
Daily Fibonacci 61.8%1.2906
Daily Pivot Point S11.2845
Daily Pivot Point S21.2817
Daily Pivot Point S31.2772
Daily Pivot Point R11.2917
Daily Pivot Point R21.2962
Daily Pivot Point R31.299

Author

Christian Borjon Valencia

Markets analyst, news editor, and trading instructor with over 14 years of experience across FX, commodities, US equity indices, and global macro markets.


More from Christian Borjon Valencia
Share:

Editor's Picks

AUD/USD drops to two-week low, further below 0.7000 after RBA's less hawkish rate hike

AUD/USD drifts lower for the second straight day on Tuesday, hitting a fresh two-week low during the Asian session after the Reserve Bank of Australia's (RBA) widely expected 25 bps rate hike. The decision was far from unanimous, with three members preferring to hold rates at 4.60%. This tempers expectations of further tightening, which, along with modest US Dollar strength, weighs on the currency pair.


USD/JPY fails near 159.00 amid weak USD, intervention risks

USD/JPY edges lower during Tuesday’s Asian session, reversing part of the previous day's gains to 158.00 as the US Dollar remains depressed amid hopes for Iran diplomacy and ahead of US midterm elections. Meanwhile, intervention risks support the Japanese Yen, though the uncertainty over the timing of the next BoJ rate hike caps gains. This keeps the pair confined within a familiar range and warrants caution before placing directional bets.


Gold struggles below $3,950 amid Fed hike bets, ahead of US midterm elections

Gold weakens further below $3,950 during the Asian session, reversing part of the previous day's recovery from a one-year low set last week. Data released on Monday showed that US manufacturing sector business activity expanded for the 10th straight month in October. The Institute for Supply Management's Manufacturing PMI came in higher than consensus estimates and rose to 55.5 in October from 54.5 in the previous month. This reaffirms hawkish US Federal Reserve expectations, which along with rebounding US bond yields, prompt fresh selling around the non-yielding yellow metal.

Cardano extends losses as sellers stay in control

Cardano (ADA) extends correction, trading below $0.189 on Tuesday after losing key support zone the previous day. Mixed derivatives data and cautious on-chain metrics continue to weigh on bullish sentiment, while weakening technical indicators suggest further downside risks for ADA.

What a split Congress means for the US Dollar

The United States is going to the polls on Tuesday, and much is at stake. The mid-term elections mean the renovation of roughly one-third of the Senate and all 435 of the House seats. Additionally, special elections in Florida and Ohio will be held to fill the seats vacated by US Secretary of State Marco Rubio and Vice President JD Vance.

The 2% inflation target came from a throwaway remark. It now moves trillions
The Federal Reserve's 2% inflation goal grew out of an off-the-cuff remark by a New Zealand politician in 1988. Bond investors still price long-term US debt as if 2% holds, so a change in how the Fed measures inflation would move markets.















