US yields slip as Powell signals patience, US Dollar pulls back from highs
- Treasury yields ease after Powell says the Fed can be patient and policy remains appropriate.
- DXY edges down to 99.51 after peaking at 99.63; the Greenback is under pressure from falling yields.
- Powell warns tariffs may hinder progress on Fed’s goals, adding to uncertainty over policy path.
US Treasury yields edged lower across the whole curve, falling by an average of two and a half to three basis points after plunging more than seven basis points earlier. However, when asked whether the Federal Reserve (Fed) is leaning toward one side of its dual mandate, Chair Jerome Powell stated that it is too early to predict.
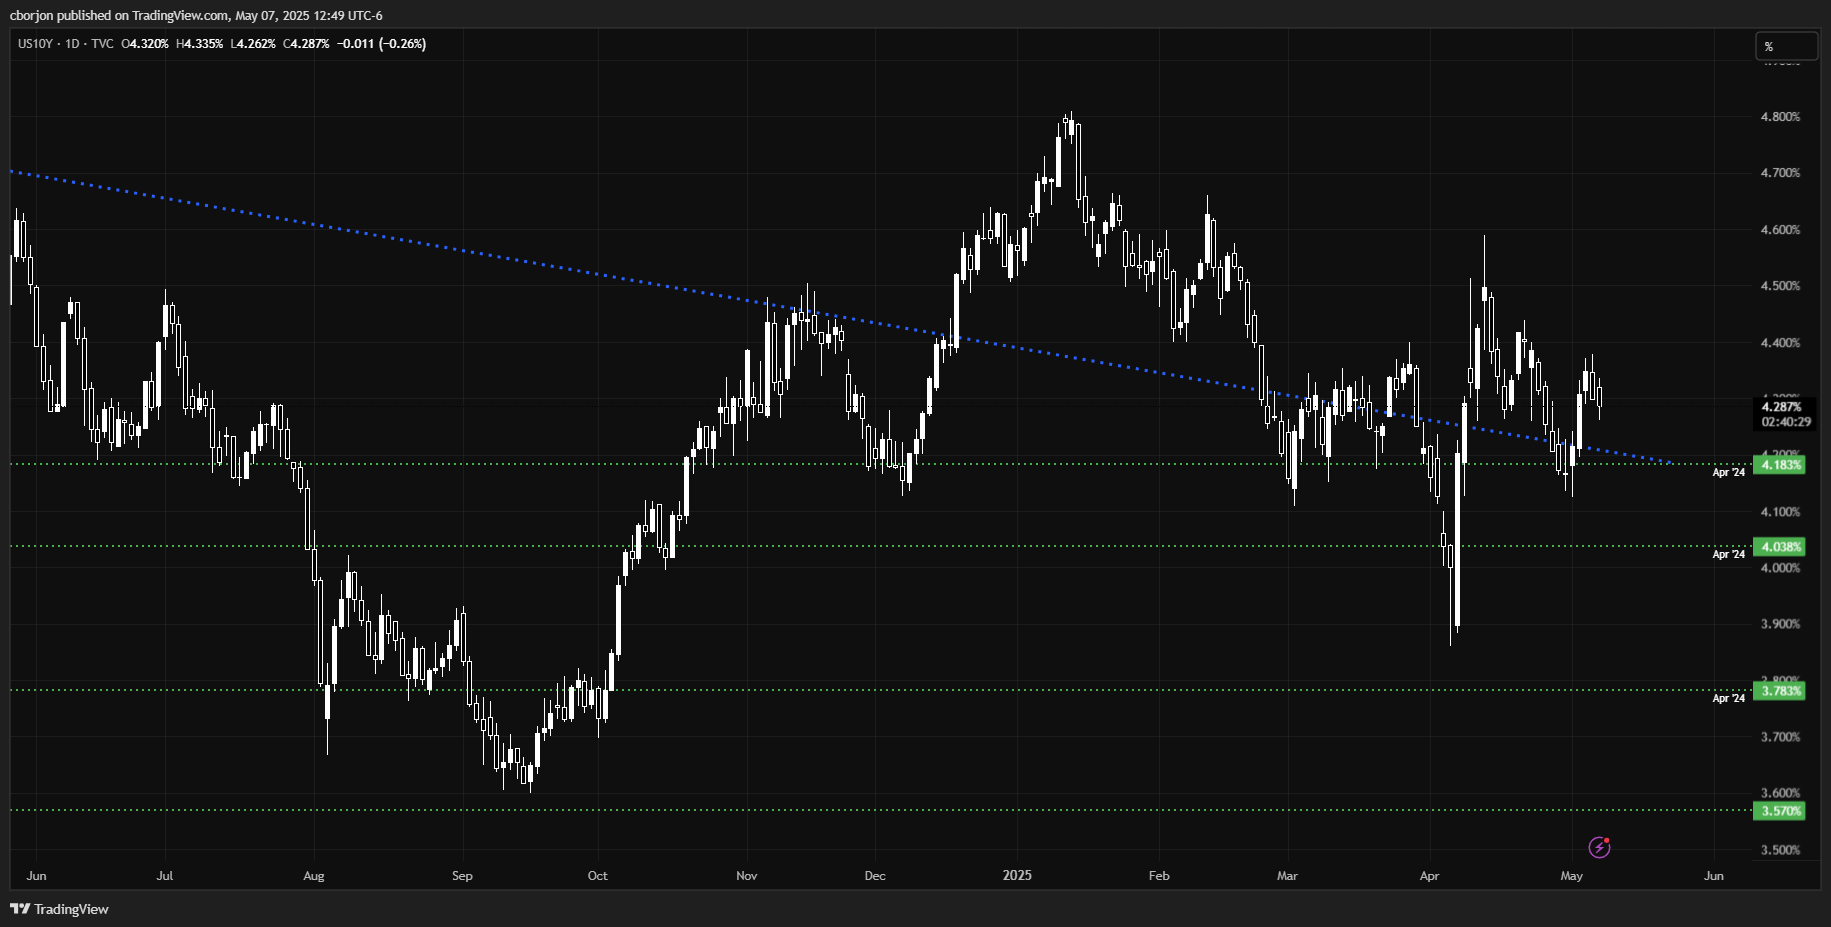
10-year yield falls to 4.27% after Chair Powell downplays urgency for action
The US 10-year Treasury yield falls two and a half basis points to 4.271% at the time of writing, weighing on the Greenback, which has so far retreated from daily highs of 99.63, as depicted by the US Dollar Index (DXY).
The DXY, which tracks the performance of the buck’s value against a basket of currencies, is at 99.51 up 0.12%.
Chair Jerome Powell said that the Fed is in no hurry and can be patient. He noted that current monetary policy is appropriate and that if things develop, “we can move quickly as appropriate.” Powell added, “We won’t make progress on our goals this year if tariffs remain.”
US 10-year yield daily chart
Fed FAQs
Monetary policy in the US is shaped by the Federal Reserve (Fed). The Fed has two mandates: to achieve price stability and foster full employment. Its primary tool to achieve these goals is by adjusting interest rates. When prices are rising too quickly and inflation is above the Fed’s 2% target, it raises interest rates, increasing borrowing costs throughout the economy. This results in a stronger US Dollar (USD) as it makes the US a more attractive place for international investors to park their money. When inflation falls below 2% or the Unemployment Rate is too high, the Fed may lower interest rates to encourage borrowing, which weighs on the Greenback.
The Federal Reserve (Fed) holds eight policy meetings a year, where the Federal Open Market Committee (FOMC) assesses economic conditions and makes monetary policy decisions. The FOMC is attended by twelve Fed officials – the seven members of the Board of Governors, the president of the Federal Reserve Bank of New York, and four of the remaining eleven regional Reserve Bank presidents, who serve one-year terms on a rotating basis.
In extreme situations, the Federal Reserve may resort to a policy named Quantitative Easing (QE). QE is the process by which the Fed substantially increases the flow of credit in a stuck financial system. It is a non-standard policy measure used during crises or when inflation is extremely low. It was the Fed’s weapon of choice during the Great Financial Crisis in 2008. It involves the Fed printing more Dollars and using them to buy high grade bonds from financial institutions. QE usually weakens the US Dollar.
Quantitative tightening (QT) is the reverse process of QE, whereby the Federal Reserve stops buying bonds from financial institutions and does not reinvest the principal from the bonds it holds maturing, to purchase new bonds. It is usually positive for the value of the US Dollar.
Author

Christian Borjon Valencia
FXStreet
Markets analyst, news editor, and trading instructor with over 14 years of experience across FX, commodities, US equity indices, and global macro markets.

















