US Dollar Index shudders as Supreme Court strikes down Trump tariffs
- The US Dollar Index waivered after the Supreme Court axed the Trump tariffs.
- US economic data came in broadly worse than expected, however consumer inflation expectations continue to ease for now.
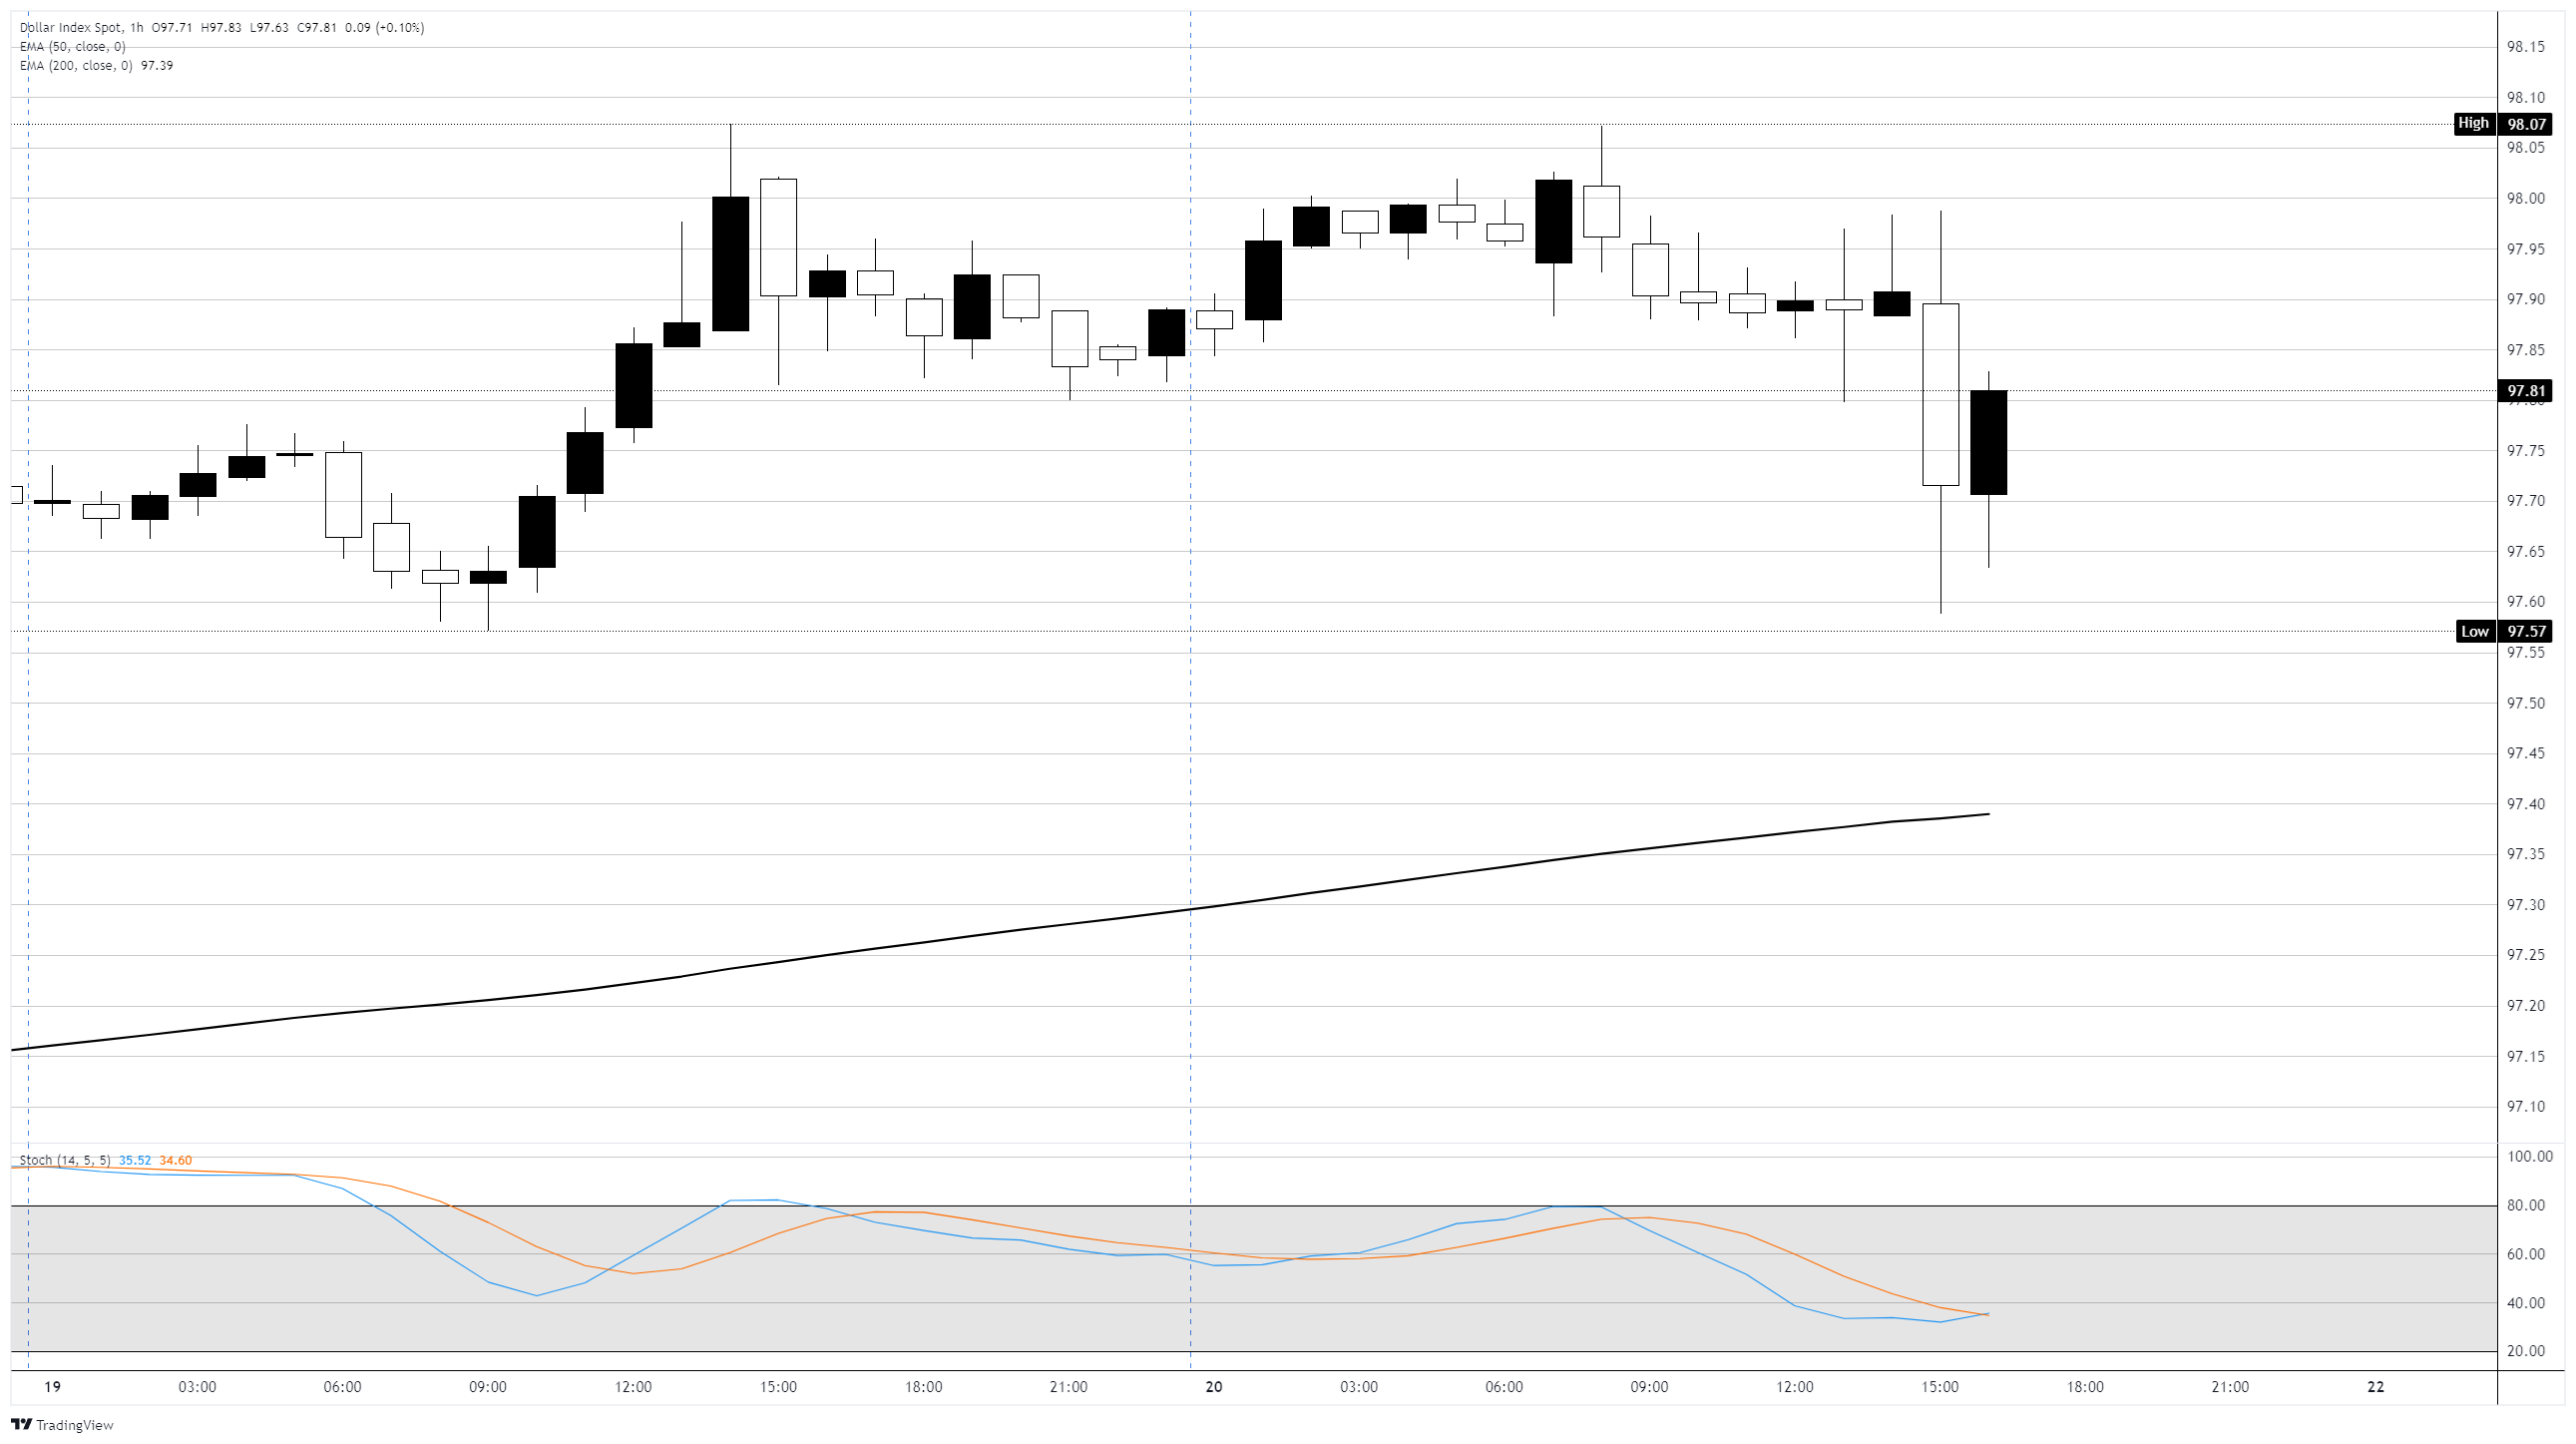
The US Dollar Index (DXY) tumbled on Friday, shedding early-session gains and dropping below 97.75 after the US Supreme Court struck down President Trump's sweeping IEEPA tariffs in a 6-3 ruling. The decision, combined with a disappointing batch of US economic data, dragged the Greenback lower against most G10 peers and reversed a modest rally that had carried DXY toward 98.00 in Asian and early European trading.
Weak GDP and hot PCE data fail to support the Dollar
The DXY initially held firm in early Friday trading after a mixed data dump at 13:30 GMT. Fourth-quarter Gross Domestic Product (GDP) came in at an annualized 1.4%, badly missing the 3.0% consensus and sharply decelerating from Q3's 4.4% expansion. The government shutdown during Q4 took a meaningful chunk out of growth, with estimates suggesting it shaved up to 1.5 percentage points off the headline figure. On the inflation side, the Personal Consumption Expenditures Price Index (PCE) ticked up to 2.9% year-over-year in December, slightly above estimates, while core PCE accelerated to 3.0% from 2.8%, topping the 2.9% consensus. Both headline and core readings rose 0.4% month-over-month versus 0.3% expected.
In isolation, the hotter-than-expected inflation data should have been Dollar-supportive, reinforcing the case for the Federal Reserve (Fed) to hold rates at 3.50%-3.75% for longer. But the sharp GDP miss undercut the narrative. The combination painted a stagflationary picture that traders struggled to price directionally, and the DXY drifted lower into the 97.85-97.90 range ahead of the Supreme Court ruling.
Supreme Court ruling sends DXY through session lows
The real move came just after 15:00 GMT when the Supreme Court handed down its decision, ruling that the International Emergency Economic Powers Act (IEEPA) does not authorize the president to impose tariffs. Chief Justice Roberts wrote the majority opinion, joined by Gorsuch, Barrett, and the three liberal justices. The ruling invalidates the "Liberation Day" reciprocal tariffs and the 25% IEEPA-based duties on Canada, China, and Mexico, though tariffs imposed under other trade statutes like Section 232 remain in place. The DXY dropped roughly a quarter of a percent in the immediate aftermath, slicing through 97.75 to print fresh session lows. The move was driven by a straightforward repricing: the removal of IEEPA tariffs reduces a key structural inflationary pressure, which in theory gives the Fed more room to cut rates eventually and weakens the Dollar's yield advantage. Penn-Wharton estimates suggest more than $175 billion in collected duties may need to be refunded, though the ruling was silent on that question.
That said, the initial Dollar weakness was somewhat contained. Markets had widely expected this outcome — JPMorgan had assigned a 64% probability to tariffs being struck down — and the Trump administration has repeatedly signaled it would attempt to replicate the tariff structure through alternative legal authorities. Treasury Secretary Bessent has pointed to Sections 301, 232, and 122 of the Trade Act as potential replacement vehicles, though analysts note these would be narrower in scope and slower to implement.
Bostic stays hawkish, flags uncertainty from ruling
Outgoing Atlanta Fed President Raphael Bostic, who retires at the end of February, was speaking on Friday and carried a hawkish tone. In the lead-up to the ruling, Bostic's recent positioning has been consistent: inflation is still too high, the Fed should be patient, and he projects no rate cuts for 2026. He has noted that one or two cuts could bring policy to neutral and warned that it is premature to declare victory on the inflation front. Following the Supreme Court decision, Bostic acknowledged that the ruling raises new questions for the Fed, noting the fallout is difficult to assess and hinges on factors like the need for refunds and how businesses react to the new trade landscape. The comments underscored the uncertainty that tariff removal introduces for monetary policy — while the disinflationary impact of lower tariffs could theoretically be dovish, the fiscal implications of $175 billion in potential refunds and the prospect of replacement measures muddy the outlook considerably.
Friday's data slate adds to the picture
The later-session data releases mostly came in softer than expected. Preliminary S&P Global PMIs for February showed both manufacturing (51.2 vs. 52.6 expected, prior 52.4) and services (52.3 vs. 53.0 expected, prior 52.7) losing momentum, with the composite index slipping to 52.3 from 53.0. The University of Michigan (UoM) consumer sentiment index for February finalized at 56.6, below the 57.3 consensus, while both 1-year and 5-year inflation expectations edged lower to 3.4% and 3.3%, respectively. The downward revisions in consumer inflation expectations are notable, as they suggest households may already be adjusting for a post-tariff environment. New home sales for November surged 15.5% month-over-month, though December's reading fell 1.7%.
DXY hourly chart
US Dollar FAQs
The US Dollar (USD) is the official currency of the United States of America, and the ‘de facto’ currency of a significant number of other countries where it is found in circulation alongside local notes. It is the most heavily traded currency in the world, accounting for over 88% of all global foreign exchange turnover, or an average of $6.6 trillion in transactions per day, according to data from 2022. Following the second world war, the USD took over from the British Pound as the world’s reserve currency. For most of its history, the US Dollar was backed by Gold, until the Bretton Woods Agreement in 1971 when the Gold Standard went away.
The most important single factor impacting on the value of the US Dollar is monetary policy, which is shaped by the Federal Reserve (Fed). The Fed has two mandates: to achieve price stability (control inflation) and foster full employment. Its primary tool to achieve these two goals is by adjusting interest rates. When prices are rising too quickly and inflation is above the Fed’s 2% target, the Fed will raise rates, which helps the USD value. When inflation falls below 2% or the Unemployment Rate is too high, the Fed may lower interest rates, which weighs on the Greenback.
In extreme situations, the Federal Reserve can also print more Dollars and enact quantitative easing (QE). QE is the process by which the Fed substantially increases the flow of credit in a stuck financial system. It is a non-standard policy measure used when credit has dried up because banks will not lend to each other (out of the fear of counterparty default). It is a last resort when simply lowering interest rates is unlikely to achieve the necessary result. It was the Fed’s weapon of choice to combat the credit crunch that occurred during the Great Financial Crisis in 2008. It involves the Fed printing more Dollars and using them to buy US government bonds predominantly from financial institutions. QE usually leads to a weaker US Dollar.
Quantitative tightening (QT) is the reverse process whereby the Federal Reserve stops buying bonds from financial institutions and does not reinvest the principal from the bonds it holds maturing in new purchases. It is usually positive for the US Dollar.
Author

Joshua Gibson
FXStreet
Joshua joins the FXStreet team as an Economics and Finance double major from Vancouver Island University with twelve years' experience as an independent trader focusing on technical analysis.