Stock Market Today: US equities end Tuesday broadly in the red as investors pull back after long weekend
- Wall Street's main indexes trade mixed after opening in the red.
- Walmart and Home Depot reported quarterly earnings ahead of the opening bell.
- Federal Reserve will release the minutes of the January policy meeting on Wednesday.

US stock indexes opened in negative territory following a long weekend on Tuesday and proceeded to end the day on the downside. The S&P 500 (SPX) index fell 0.60% to close the session at 4,975.51, falling back below the 5,000.00 major level. The Dow Jones (DJIA) dropped 0.17% to end at 38,563.8, with the Nasdaq (IXIC) losing 0.92% to finish at 15,630.78.
Stock market news
- The Consumer Staples Sector rose 1.13% as the best-performing major S&P sector on Tuesday. The Technology Sector plunged 1.7% before hitting the Tuesday close in the red 1.27% as the weakest major sector.
- Discover Financial Services (DFS) is the biggest gainer on the day, rising 12.6% to close at $124.42. On the other hand, Expeditors International of Washington Inc. (EXPD) fell 6.9% to end at $115.57 as one of the biggest decliners, just beat out by Trade Desk Inc. (TTD), which fell 7.163% to hit Tuesday's closing bell at $82.56.
- Dow Jones (DJIA) closed the previous week virtually unchanged at 38,628. S&P 500 lost 0.42% to close at 5,005.56 and Nasdaq fell 0.82% to 15,775.65.
- Retailer giant Walmart Inc. (WMT) reported an adjusted earning per share of $1.8 ahead of the opening bell on Tuesday. The company said that it expects consolidated net sales to rise in the range of 3%-4% and announced that it will buy smart-TV producer Vizio (VZIO) for about $2.3 billion.
- Home Depot Inc. (HD) said net income in Q4 was $2.8 billion and the adjusted earnings per share was $2.82. The company, however, said that if projects sales for the fiscal year 2024 to be below estimates, citing slowing demand for discretionary items such as flooring, furniture and kitchen, per Reuters.
- Palo Alto Networks Inc. (PANW), Public Storage (PSA) and Realty Income Corp. (O) will be among the top companies that will release quarterly earnings reports after the closing bell on Tuesday.
- The Federal Reserve will release the minutes of the January policy meeting on Wednesday. On Thursday, preliminary February Manufacturing and Services PMI reports for Germany, the Euro area, the UK and the US will be scrutinized by market participants.
- The Bureau of Labor Statistics reported on Friday that the Producer Price Index (PPI) for final demand in the US rose 0.9% on a yearly basis in January. This reading followed the 1% increase recorded in December but came in above the market expectation of 0.6%. The annual Core PPI rose 2% in the same period, compared to December's increase of 1.8%. On a monthly basis, the Core PPI was up 0.5% following the 0.1% decline recorded in the previous month.
- The University of Michigan's Consumer Sentiment Index improved modestly to 79.6 in February's flash estimate from 79.0 in January. The Current Conditions Index edged lower to 81.5 from 81.9 and the Consumer Expectations Index rose to 78.4 from 77.1.
- Inflation in the US, as measured by the change in the Consumer Price Index (CPI), softened to 3.1% on a yearly basis in January from 3.4% in December, the BLS reported on Tuesday. This reading came in above the market expectation of 2.9%. The Core CPI, which excludes volatile food and energy prices, rose 3.9% in the same period and matched December's increase, surpassing analysts' estimate of 3.7%.
S&P 500 15 minute chart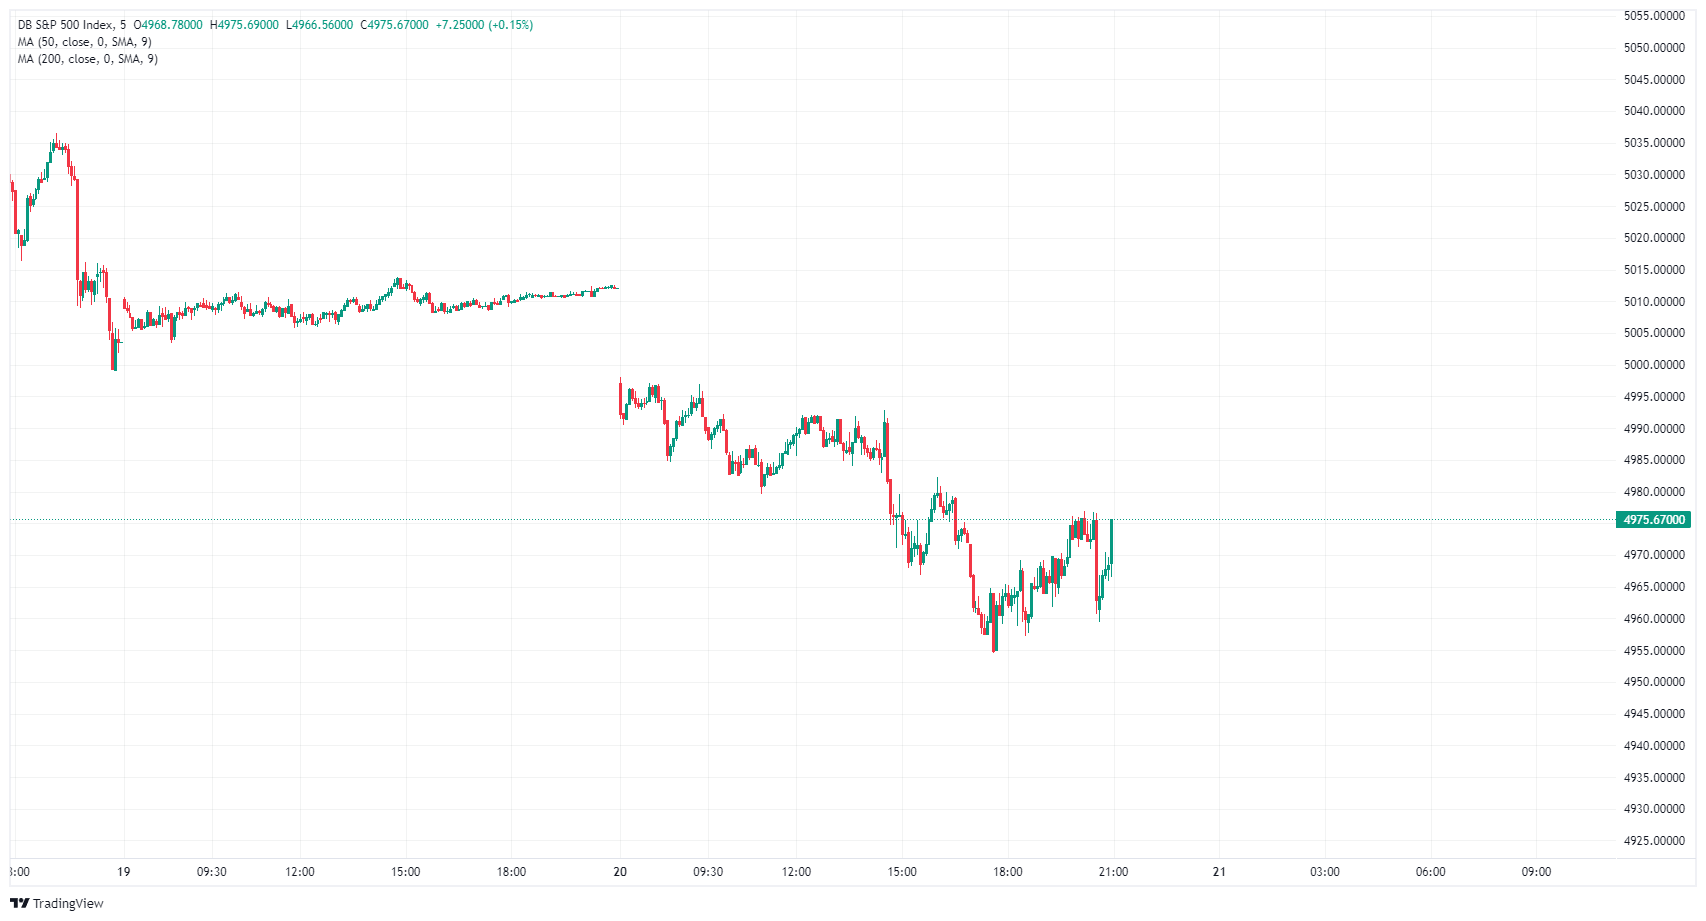
S&P 500 FAQs
What is the S&P 500?
The S&P 500 is a widely followed stock price index which measures the performance of 500 publicly owned companies, and is seen as a broad measure of the US stock market. Each company’s influence on the computation of the index is weighted based on market capitalization. This is calculated by multiplying the number of publicly traded shares of the company by the share price. The S&P 500 index has achieved impressive returns – $1.00 invested in 1970 would have yielded a return of almost $192.00 in 2022. The average annual return since its inception in 1957 has been 11.9%.
How are companies chosen to be included in the S&P 500?
Companies are selected by committee, unlike some other indexes where they are included based on set rules. Still, they must meet certain eligibility criteria, the most important of which is market capitalization, which must be greater than or equal to $12.7 billion. Other criteria include liquidity, domicile, public float, sector, financial viability, length of time publicly traded, and representation of the industries in the economy of the United States. The nine largest companies in the index account for 27.8% of the market capitalization of the index.
How can I trade the S&P 500?
There are a number of ways to trade the S&P 500. Most retail brokers and spread betting platforms allow traders to use Contracts for Difference (CFD) to place bets on the direction of the price. In addition, that can buy into Index, Mutual and Exchange Traded Funds (ETF) that track the price of the S&P 500. The most liquid of the ETFs is State Street Corporation’s SPY. The Chicago Mercantile Exchange (CME) offers futures contracts in the index and the Chicago Board of Options (CMOE) offers options as well as ETFs, inverse ETFs and leveraged ETFs.
What factors drive the S&P 500?
Many different factors drive the S&P 500 but mainly it is the aggregate performance of the component companies revealed in their quarterly and annual company earnings reports. US and global macroeconomic data also contributes as it impacts on investor sentiment, which if positive drives gains. The level of interest rates, set by the Federal Reserve (Fed), also influences the S&P 500 as it affects the cost of credit, on which many corporations are heavily reliant. Therefore, inflation can be a major driver as well as other metrics which impact the Fed decisions.
Author

FXStreet Team
FXStreet
Composed of a group of economic journalists and FX experts, the FXStreet content team produces and oversees all content published on FXStreet. It provides a purely journalistic approach to the Forex market.















