|

S&P 500 (SPX): 4,000 reasons to wait for earnings

  • US equity markets return after a long weekend.
  • Big earnings week with Netflix later this week.
  • Big technical levels could stall any more gains.
The equity market returns after a long weekend, and initial economic data points look promising. Europe posted some strong German ZEW data, and China also showed its economy going in the right direction. We had a muted reaction this morning from commodities, but oil has just spiked above $80 and this may start another push higher. Of course, this is a double-edged sword or catch-22. Positive news from China is likely to see a big surge in commodity prices, which would be another inflationary problem for global economies. 

S&P 500 (SPX) news

It is a make or break week for this latest rally. Earnings season started with mixed results from the big banks, and this week we move on to regional banks and then Netflix (NFLX) later in the week. That starts the tech season and another make-or-break period. Recent data has been positive and more news from China overnight is also positive. Perhaps a soft landing is possible, but companies are still beginning to report margin pressures, so earnings will give us more clarity. So far Goldman Sachs (GS) looks disappointing this morning, and Morgan Stanley (MS) is lackluster. 

S&P 500 (SPX) forecast

Technically, 4,000 is a huge level and trendline resistance on the daily chart. Break above, and we move on to 4,100. 4,000 is also the 200-day moving average, so really a key level. The pivot is at 3,951, and failure is likely to see the S&P 500 back to support at the 3,800 to 3,745 zone. For today my bias is slightly more positive but in cautious moves ahead of earnings.
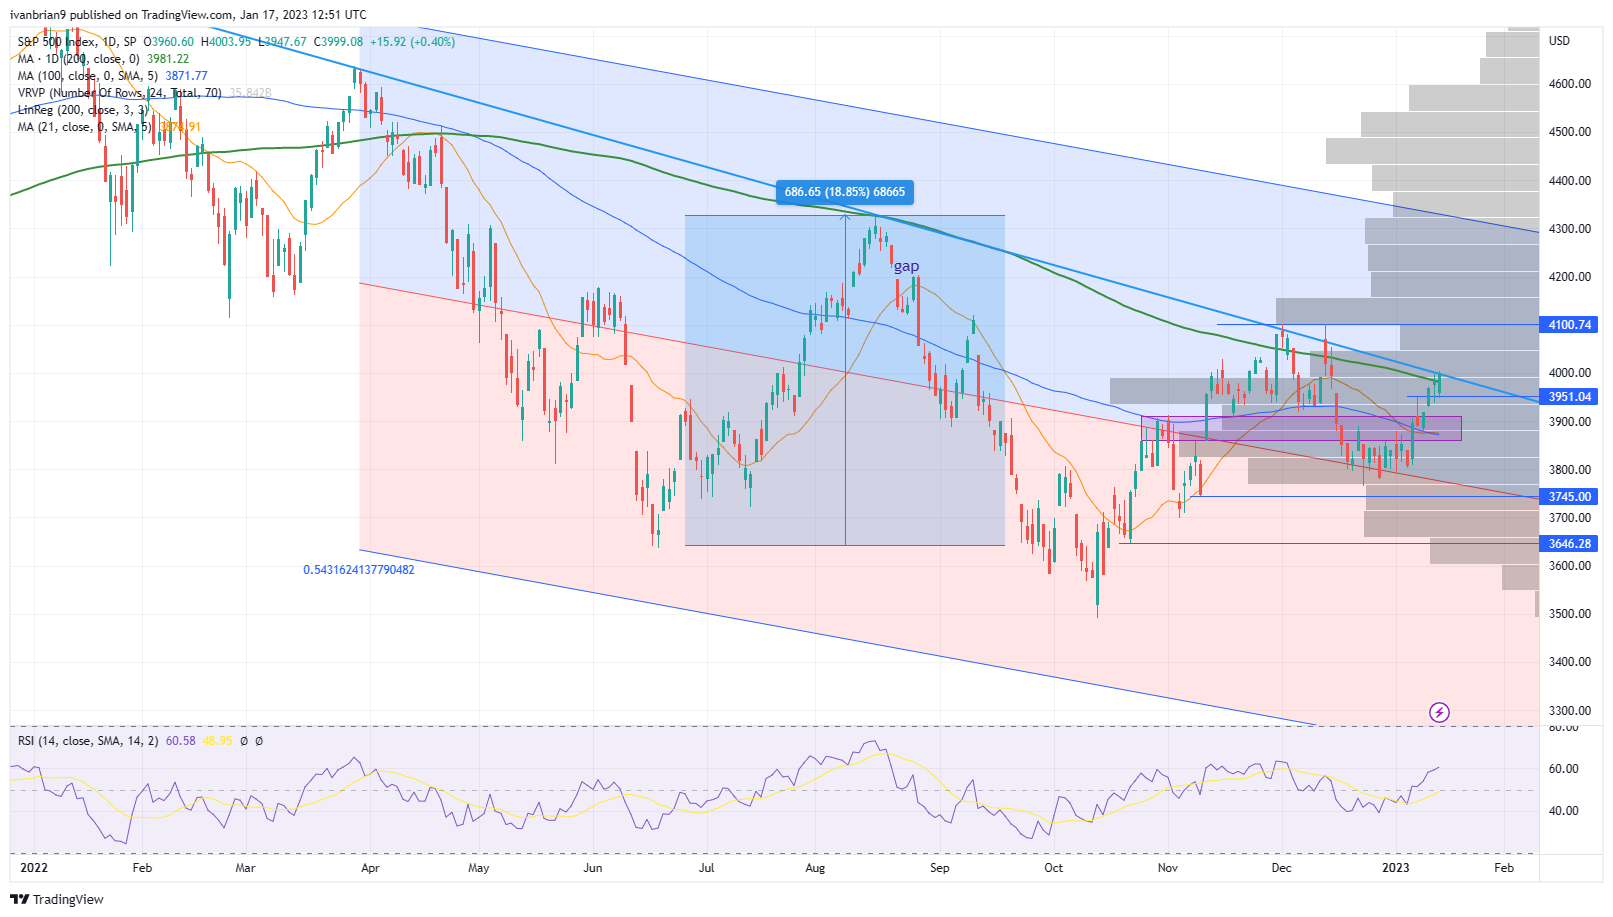
SPX daily chart

Author

Ivan Brian

Ivan Brian

FXStreet

Ivan Brian started his career with AIB Bank in corporate finance and then worked for seven years at Baxter. He started as a macro analyst before becoming Head of Research and then CFO.


More from Ivan Brian
Share:

Editor's Picks

AUD/USD bounces back toward 0.6950 on fresh USD supply

AUD/USD bounces back toward 0.6950 in the Asian session on Friday. The US Dollar retreats from 17-month highs as traders take profits off the table ahead of the all-important US Nonfarm Payrolls report. Meanwhile, the Australian Dollar draws support from reviving expectations of a November interest rate hike amid elevated global yields and inflation risks.


USD/JPY struggles near 158.00 as USD retreats ahead of NFP

USD/JPY is struggling for fresh impetus near 158.00, moving away from the top end of its weekly range in the Asian session on Friday, after hotter-than-expected Tokyo CPI and amid a broad US Dollar retreat. Traders reposition themselves ahead of US Nonfarm Payrolls.

Gold fades the earlier optimism; back below $4,200

Gold could not sustain the post-NFP bull run past the $4,200 mark per troy ounce, receding toward the $4,180 region at the end of the week. The precious metal’s inconclusive price action comes amid fresh selling pressure hurting the US Dollar as investors assess the latest NFP data.

Crypto Today: Bitcoin, Ethereum and XRP gains reinforce bullish outlook

Cryptocurrency prices are broadly recovering on Friday, led by Bitcoin moving above $86,000. Ethereum has reaffirmed its bullish outlook, rising above $2,700 while the immediate area at $2,800 caps upside. Meanwhile, Ripple hovers near $1.54.

Week ahead – Fed minutes in the spotlight amid bond market rout

Energy crisis and soaring bond yields to stay in driver’s seat in quiet week. Fed minutes eyed after drop in October rate hike bets. ISM services PMI and Treasury auctions to be watched too. Canadian employment, Japanese wages and ECB minutes also on tap.

The Euro is near a one-year low: Inflation could trigger its rebound, not its fall

EUR/USD has fallen to its lowest level since May 2025. The pair hit 1.1312 on Wednesday and trades well below the January peak of 1.2082. The decline reflects a powerful combination of US Dollar strength, geopolitical uncertainty and renewed concerns about Europe's exposure to higher energy prices.















