|

S&P 500 reclaims 3900 but remains negative, and the Dow Jones drops more than 150 points on risk aversion

  • The S&P 500, the Dow Jones, and the Nasdaq recorded losses amidst a risk-aversion environment.
  • Nothing would stop the Fed from hiking as Kansas City Fed’s George said that the rough markets wouldn’t alter the rate hike plan.
  • The US Dollar Index is falling more than 1.50%, dragged down by falling US Treasury yields; gold rallied.
US equities recovered some ground during the day but remain set to finish with losses, despite investors’ efforts of a last-hour rally. At the time of writing, the S&P 500, the Dow Jones Industrial, and the heavy-tech Nasdaq Composite record losses between  0.13% and 0.70% and sits at 3,904.92, 11,398.96 and 31,268.98, respectively.

Sentiment remains dismal, emphasized by the stagflation scenario surrounding the global economy. China’s coronavirus crisis continues as local outbreaks increase concerns of additional lockdowns. Also, high inflationary pressures have taken their toll on big US retailers, such as Walmart and Target, which expressed that their margins shrank due to elevated prices.

Fed officials have crossed the wires in the last couple of days, and most of them have expressed that inflation is “too high” and reiterated the posture of increasing the Federal Fund Rates (FFR) by 50-bps at the June meeting. The Kansas City Fed President Esther George said that a “rough week in the equity markets” would not change her view of hiking rates, while Philadelphia’s Fed Patrick Harker added that the US economy might have a few quarters of negative growth, but that is not what he is foreseeing.

In the meantime, the greenback is further weakening in the week, more than 1.50%. The US Dollar Index, a gauge of the buck’s value, sits at 102.751, losing 1.11% on Thursday. The US 10-year Treasury yield extended its losses in the day, four basis points down from the open and is currently at 2.850%.

Sector-wise, the gainers are Materials, Consumer Discretionary, and Energy, up 1.23%, 0.84%, and 0.69%, respectively. The worst performers are Consumer Staples, Financials, and Technology, falling 1.74%, 0.54%, and 0.50% each.

In the commodities complex, the US crude oil benchmark, WTI, is gaining 2.70%, trading at $112.00 a barrel, while precious metals like Gold (XAU/USD) is rallying 1.35%, exchanging hands at $1840.88 a troy ounce, helped by a softer US dollar.

S&P 500 Daily chart
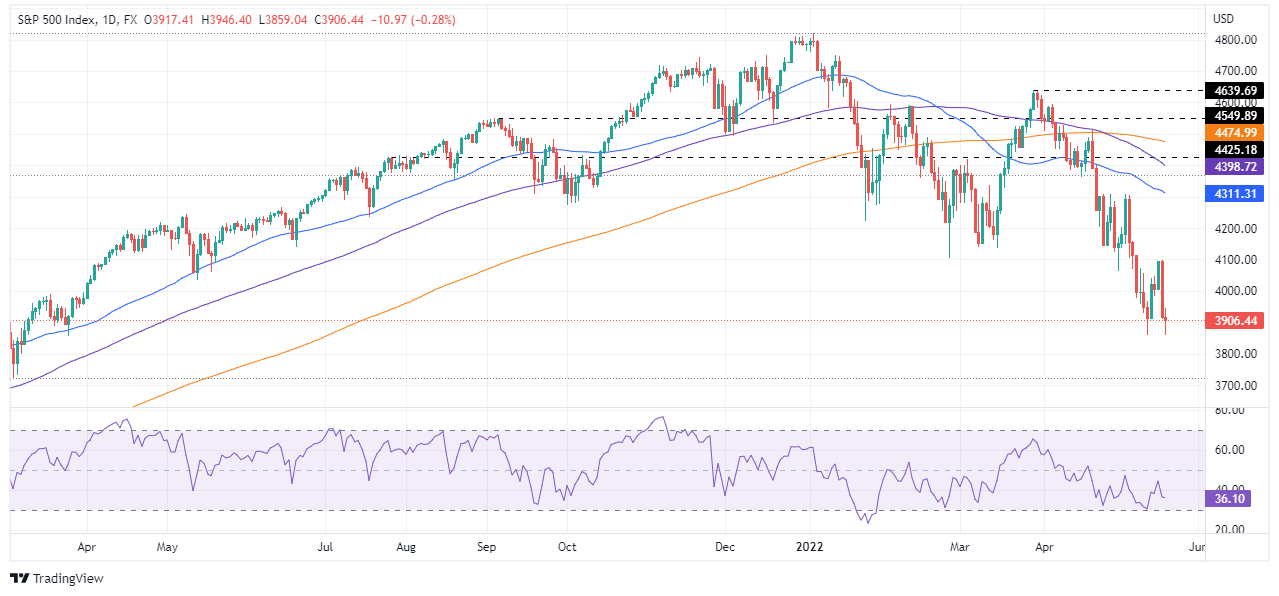
Key Technical Levels

SP 500

Overview
Today last price3904.92
Today Daily Change0.00
Today Daily Change %0.00
Today daily open3926.15
 
Trends
Daily SMA204126.55
Daily SMA504318.61
Daily SMA1004401.43
Daily SMA2004475.07
 
Levels
Previous Daily High4084.21
Previous Daily Low3911.75
Previous Weekly High4095.91
Previous Weekly Low3858.25
Previous Monthly High4592.12
Previous Monthly Low4122.09
Daily Fibonacci 38.2%3977.63
Daily Fibonacci 61.8%4018.33
Daily Pivot Point S13863.86
Daily Pivot Point S23801.58
Daily Pivot Point S33691.4
Daily Pivot Point R14036.32
Daily Pivot Point R24146.5
Daily Pivot Point R34208.78

Author

Christian Borjon Valencia

Markets analyst, news editor, and trading instructor with over 14 years of experience across FX, commodities, US equity indices, and global macro markets.


More from Christian Borjon Valencia
Share:

Editor's Picks

AUD/USD stays defensive below 0.7150 after Chinese data

AUD/USD remains on the back foot below 0.7150 in the Asian session on Tuesday, close to an over three-week low touched the previous day. US bond yields hold near multi-year highs ahead of the FOMC meeting and oil-driven inflation risks, supporting the US Dollar and weighing on the currency pair. Mixed Chinese activity data for August also fail to inspire the Aussie.

USD/JPY extends gains toward 155.00 amid USD resurgence

USD/JPY keeps pushing higher toward 155.00 early Tuesday, looking for more upside, as traders await the FOMC and BoJ meetings this week. Meanwhile, Fed rate-hike bets and oil-driven inflation risks keep US bond yields near multi-year highs, supporting the US Dollar and the pair. That said, a more hawkish repricing of the BoJ normalization path might continue to underpin the Japanese Yen and could limit USD/JPY's upside. .

$4,275: Gold skating on thin ice as eyes remain on Mideast conflict, Fed

Gold is briefly regaining $4,300 early Tuesday, looking to build on a tepid recovery from six-week troughs near $4,250. Traders are monitoring the widening conflict in the Middle East ahead of the two-day US Federal Reserve monetary policy meeting later in the day.

Bitcoin remains volatile amid CLARITY Act vote – Zcash, Stellar rally

Bitcoin holds steady around $78,000 on Tuesday, sustaining its roughly 2% recovery from the previous day. Broader cryptocurrency market volatility remains elevated ahead of the scheduled CLARITY Act cloture vote on Tuesday. Zcash and Stellar retain bullish momentum, emerging as the top performers over the last 24 hours.

Hard assets are entering their next explosive phase – Are you positioned?
It’s official: Commodities and Hard Assets have become the best-performing asset class of 2026. In a year defined by persistent inflation, geopolitical conflict, rising sovereign debt and intensifying supply disruption, capital is rotating aggressively into the one area governments cannot print and central banks cannot manufacture: scarce physical assets.
Venezuela’s 65-billion-barrel Oil deal could reshape America’s inflation fight
The United States (US) has secured unprecedented access to part of Venezuela’s vast Oil reserves. The timing is particularly significant as the war with Iran is disrupting Middle Eastern supplies, keeping energy prices elevated and reviving concerns about inflation.















