Mexican Peso surges as US Dollar weakens, USD/MXN approaches 19.00
- The Mexican Peso prolongs its gains to three straight days as the US Congress prepares for voting on Trump’s tax bill.
- Expectations of strong Mexican Retail Sales data and high inflation could improve the Mexican Peso’s appeal.
- USD/MXN is technically bearish, with sellers eyeing a test of the psychological 19.00 figure.
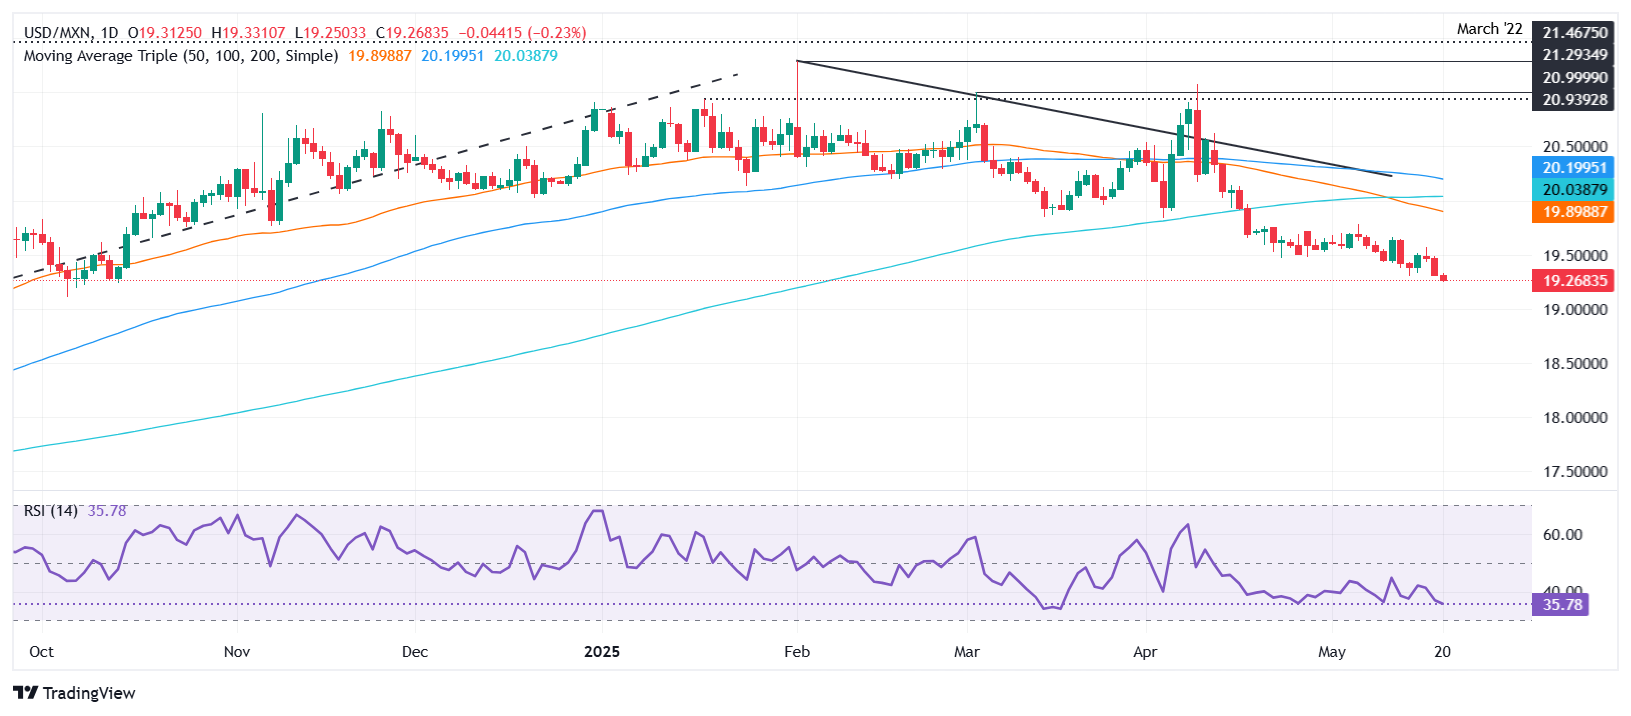
The Mexican Peso (MXN) rallied to a new yearly high against the US Dollar (USD) on Tuesday as investors continued to digest Moody’s downgrade to United States (US) government debt and wait for the vote on the Tax bill presented by the Trump administration. At the time of writing, USD/MXN trades at 19.28, down 0.18%.
Earlier, the Peso hit a new yearly high as the exotic pair fell to 19.25 earlier during the European session. Mexico’s economic docket remained absent, with traders eyeing the release of April’s Retail Sales on Wednesday, followed by the final reading of the Gross Domestic Product (GDP) for the first quarter of 2025 and the May mid-month inflation reading.
Across the northern border, the US economic schedule featured some Federal Reserve (Fed) officials grabbing the headlines. Meanwhile, the US Congress is preparing to approve President Trump’s “One Big Beautiful Bill,” which is expected to increase the US federal deficit significantly over the next decade.
Mexican Peso daily drivers: The Greenback’s fall on uncertainty is the Peso’s victory
- The main catalysts for USD/MXN remain broad US Dollar weakness, as depicted by the US Dollar Index (DXY). The DXY, which tracks the performance of the buck’s value against a basket of six currencies, falls 0.31% to 100.07.
- Mexico’s Retail Sales in April are expected to decline from 0.2% to 0.1% MoM. On an annual basis, sales are expected to improve from a 1.1% contraction to 2.2%.
- Mexico’s GDP economic growth for Q1 2025 is projected to rise by 0.2% QoQ, up from a 0.6% contraction in Q4 2024. May’s mid-month inflation is expected to rise by 4.01% YoY, and core figures at 3.98% YoY.
- On Monday, Banco de México (Banxico) Governor Victoria Rodríguez Ceja said that monetary policy would stay restrictive but hinted that there is room to reduce the benchmark interest rate in an interview published by El Financiero.
- Last week, Banxico reduced its rates to 8.50%, and cited the need for additional calibration of monetary policy and anticipating further easing.
- Moody’s downgrade of US government debt from AAA to AA1 continues to weigh on the US Dollar. The international agency cited the lack of action by successive US administrations and Congress as contributing to the country’s worsening fiscal position, raising concerns over long-term debt sustainability.
- Recently, St. Louis Fed President Alberto Musalem stated that if inflation expectations become de-anchored, the Fed's policy should focus on maintaining price stability. He said that there is uncertainty about whether tariffs would have a temporary or persistent effect on inflation, and added that if trade tensions are durable and de-escalated, inflation could get back to target.
- Beth Hammack of the Cleveland Fed stated that US government policies have increased the difficulty for the Fed to manage the economy and fulfill the dual mandate role. She said that the odds of a stagflationary scenario are rising.
USD/MXN technical outlook: The Peso surges as USD/MXN refreshes yearly lows, eyes on 19.00
USD/MXN remains bearish-biased, with sales poised to challenge the 19.00 figure in the near term. Momentum favors an extension of the downtrend, as indicated by the Relative Strength Index (RSI) being below the 50 neutral line and approaching extreme oversold conditions.
That said, if USD/MXN clears 19.00, last hit on August 21, 2024, then the next support would be 18.50, followed by the 18.00 psychological mark. Conversely, buyers must reclaim 19.50 to remain hopeful of hitting higher prices, with the first resistance seen at 19.53, the 20-day Simple Moving Average (SMA), followed by the 50-day SMA at 19.90.
Banxico FAQs
The Bank of Mexico, also known as Banxico, is the country’s central bank. Its mission is to preserve the value of Mexico’s currency, the Mexican Peso (MXN), and to set the monetary policy. To this end, its main objective is to maintain low and stable inflation within target levels – at or close to its target of 3%, the midpoint in a tolerance band of between 2% and 4%.
The main tool of the Banxico to guide monetary policy is by setting interest rates. When inflation is above target, the bank will attempt to tame it by raising rates, making it more expensive for households and businesses to borrow money and thus cooling the economy. Higher interest rates are generally positive for the Mexican Peso (MXN) as they lead to higher yields, making the country a more attractive place for investors. On the contrary, lower interest rates tend to weaken MXN. The rate differential with the USD, or how the Banxico is expected to set interest rates compared with the US Federal Reserve (Fed), is a key factor.
Banxico meets eight times a year, and its monetary policy is greatly influenced by decisions of the US Federal Reserve (Fed). Therefore, the central bank’s decision-making committee usually gathers a week after the Fed. In doing so, Banxico reacts and sometimes anticipates monetary policy measures set by the Federal Reserve. For example, after the Covid-19 pandemic, before the Fed raised rates, Banxico did it first in an attempt to diminish the chances of a substantial depreciation of the Mexican Peso (MXN) and to prevent capital outflows that could destabilize the country.
Author

Christian Borjon Valencia
FXStreet
Markets analyst, news editor, and trading instructor with over 14 years of experience across FX, commodities, US equity indices, and global macro markets.

















