Mexican Peso falls as Banxico cuts rates, USD/MXN rises
- USD/MXN rallies after Banxico slashes benchmark rate to 8.50%.
- Banxico unanimously cuts rates by 50 bps, reinforcing dovish outlook and pressuring the Peso.
- Weak US PPI and Retail Sales support the disinflation trend, but the Greenback gains on rate differential.
- Traders eye University of Michigan Consumer Sentiment for further insights into US economic momentum.
The Mexican Peso (MXN) depreciated against the US Dollar (USD) on Thursday after the Banco de Mexico (Banxico) reduced rates as expected, amid weaker-than-expected economic data from the United States (US). At the time of writing, the USD/MXN trades at 19.49, up 0.61%.
Recently, Banxico lowered its interest rate by 50 basis points (bps), as expected, to 8.50%, marking the seventh consecutive rate cut by the Mexican institution. The central bank’s decision was unanimous and weighed on the Mexican currency, which, since the beginning of the North American session, was losing ground against the Greenback.
In the US, inflation data on the producer side showed that the disinflation process continued in April, indicating progress despite trade policies implemented by President Donald Trump keeping investors uncertain about the global economic outlook.
Further data revealed that consumer spending is cooling, as shown by April’s Retail Sales, and that the labor market remains solid, following the latest release of Initial Jobless Claims figures.
In the US, the economic docket will feature the University of Michigan's preliminary Consumer Sentiment poll for June.
Daily digest market movers: Banxico’s decision tumbles the Peso
- Banxico reduced interest rates as expected, with unanimous support. In its policy statement, the central bank stated that it would continue to “calibrate” monetary policy, anticipating that the current inflationary environment would allow it to continue the easing cycle.
- Mexico’s central bank statement added that cuts by the same magnitude are on the table, and despite upward revising their inflation projections, the board expects headline prices to converge to the 3% goal by Q3 2026.
- Officials at Banxico added that the changes in economic policy by the US administration have introduced uncertainty to the forecasts.
- The interest rate differential between Mexico and the US is reducing. Therefore, Banxico’s dovish stance could cap Peso’s advance and exert upward pressure on the USD/MXN pair.
- Goldman Sachs has upwardly revised Mexico’s economic growth for 2025 to 0% from the previously projected 0.5% contraction.
- Recently, Mexico’s Economy Minister, Marcelo Ebrard, announced that the USMCA revision will commence in the second half of 2025.
- Notably, investors reduced their bets that the Federal Reserve (Fed) will only cut rates twice this year, rather than three times, as indicated by data from the Chicago Board of Trade (CBOT).
- The December 2025 fed funds rates futures contract shows that market players expect 54 basis points of easing.
USD/MXN technical outlook: Mexican Peso treads water, with USD/MXN poised to test 19.50
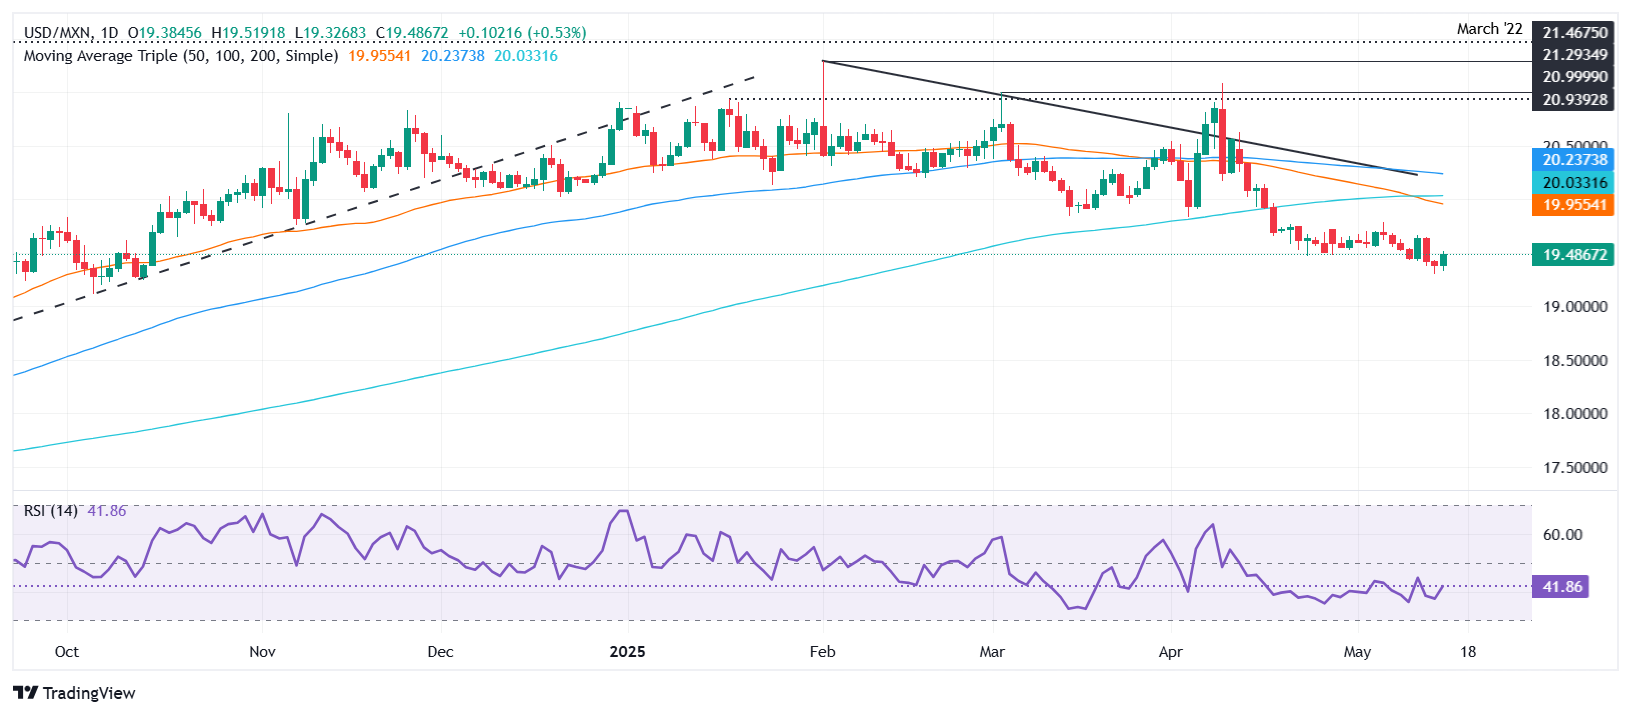
The USD/MXN downtrend paused as the pair edged up before and after the Banxico decision. Nevertheless, failure to achieve a daily close above 19.50 could pave the way for a Mexican Peso recovery, which could send the pair drifting toward the 19.00 figure.
Once that level is taken out, the next support would be August 19, 2024, swing low of 18.59. Conversely, if USD/MXN climbs past the 19.50 area and reaches a three-day high of 19.66, surpassing the 20-day Simple Moving Average (SMA), it may retreat somewhat.
Mexican Peso FAQs
The Mexican Peso (MXN) is the most traded currency among its Latin American peers. Its value is broadly determined by the performance of the Mexican economy, the country’s central bank’s policy, the amount of foreign investment in the country and even the levels of remittances sent by Mexicans who live abroad, particularly in the United States. Geopolitical trends can also move MXN: for example, the process of nearshoring – or the decision by some firms to relocate manufacturing capacity and supply chains closer to their home countries – is also seen as a catalyst for the Mexican currency as the country is considered a key manufacturing hub in the American continent. Another catalyst for MXN is Oil prices as Mexico is a key exporter of the commodity.
The main objective of Mexico’s central bank, also known as Banxico, is to maintain inflation at low and stable levels (at or close to its target of 3%, the midpoint in a tolerance band of between 2% and 4%). To this end, the bank sets an appropriate level of interest rates. When inflation is too high, Banxico will attempt to tame it by raising interest rates, making it more expensive for households and businesses to borrow money, thus cooling demand and the overall economy. Higher interest rates are generally positive for the Mexican Peso (MXN) as they lead to higher yields, making the country a more attractive place for investors. On the contrary, lower interest rates tend to weaken MXN.
Macroeconomic data releases are key to assess the state of the economy and can have an impact on the Mexican Peso (MXN) valuation. A strong Mexican economy, based on high economic growth, low unemployment and high confidence is good for MXN. Not only does it attract more foreign investment but it may encourage the Bank of Mexico (Banxico) to increase interest rates, particularly if this strength comes together with elevated inflation. However, if economic data is weak, MXN is likely to depreciate.
As an emerging-market currency, the Mexican Peso (MXN) tends to strive during risk-on periods, or when investors perceive that broader market risks are low and thus are eager to engage with investments that carry a higher risk. Conversely, MXN tends to weaken at times of market turbulence or economic uncertainty as investors tend to sell higher-risk assets and flee to the more-stable safe havens.
Author

Christian Borjon Valencia
FXStreet
Markets analyst, news editor, and trading instructor with over 14 years of experience across FX, commodities, US equity indices, and global macro markets.

















