Indian Rupee cushioned by RBI’s likely intervention, outlook remain fragile
- The Indian Rupee finds a temporary ground against the US Dollar near 96.00 on possible RBI intervention.
- Elevated energy prices and Fed’s higher interest rates prospects boost US Treasury Yields.
- The possibility of an RBI interest rate hike in October has increased.
The Indian Rupee (INR) gains a temporary ground against the US Dollar (USD) on Friday after remaining under pressure in the past few days. The USD/INR pair struggles to extend gains above 95.96 on the likely Reserve Bank of India’s (RBI) intervention.
According to a Reuters report, India's central bank likely sold US Dollars before the local spot market opened on Friday, four traders told, helping the Indian rupee hold stronger than the key psychological 96-per-dollar level.
However, the mild strength in the Indian Rupee appears to be short-lived as United States (US) Treasury Yields continue to rally due to elevated energy prices and Federal Reserve’s (Fed) higher-for-longer interest rate narrative.
In the opening trade, the MCX Crude Oil contract expiring on October 19 trades 2.3% lower to near Rs. 8,950, but has gained sharply in the last two trading days. Meanwhile, 10-year US Treasury Yields are close to its 19-year high of 5.23% posted on Thursday.
The appeal of riskier assets, such as equities and currencies, like the Indian Rupee, gets diminished, in a high US bond yields environment.
US yields surge as markets reprice Fed's rate path
Analysts at MUFG highlight that the “dominant market theme remains the relentless rise in US yields and the renewed repricing of Fed expectations.” They note that Treasury yields “moved sharply higher as strong US activity data and rising energy prices reinforced concerns that inflation could prove more persistent.” In their latest update, MUFG points out that the “US 2-year Treasury yield jumped 14bp to around 4.9%, while the 10-year yield rose above 5.0% and the 30-year yield climbed beyond 5.4%.”
Against this backdrop, MUFG observes that “markets now price around 37bp of additional Fed tightening by December 2026, equivalent to roughly 1.5 rate hikes by year-end.” The bank cautions that this “economic resilience raises the risk that policymakers may need to do more to prevent inflation pressures from becoming entrenched,” underscoring the challenging environment for risk assets and, in particular, Asia FX.
India’s rising retail inflation boosts hawkish RBI bets
Analysts at MUFG note that India’s August inflation “rose 4.8% yoy (DBSf 4.9%) from a revised 4.5% month before, firmest since December 2024,” highlighting a clear uptick in price pressures. They add that “a gradual broadening of price pressures is likely to keep headline inflation above 5% in second half of the fiscal year, underscoring the need for a tighter policy bias.” In their view, “recent developments, including a sustained rise in crude prices, tightening global financial conditions, firm domestic growth and signs of broadening in core pressures, strengthen the case for a shallow 50bp hike in second half of FY27, making October’s meeting a live one.”
USD/INR Technical Analysis
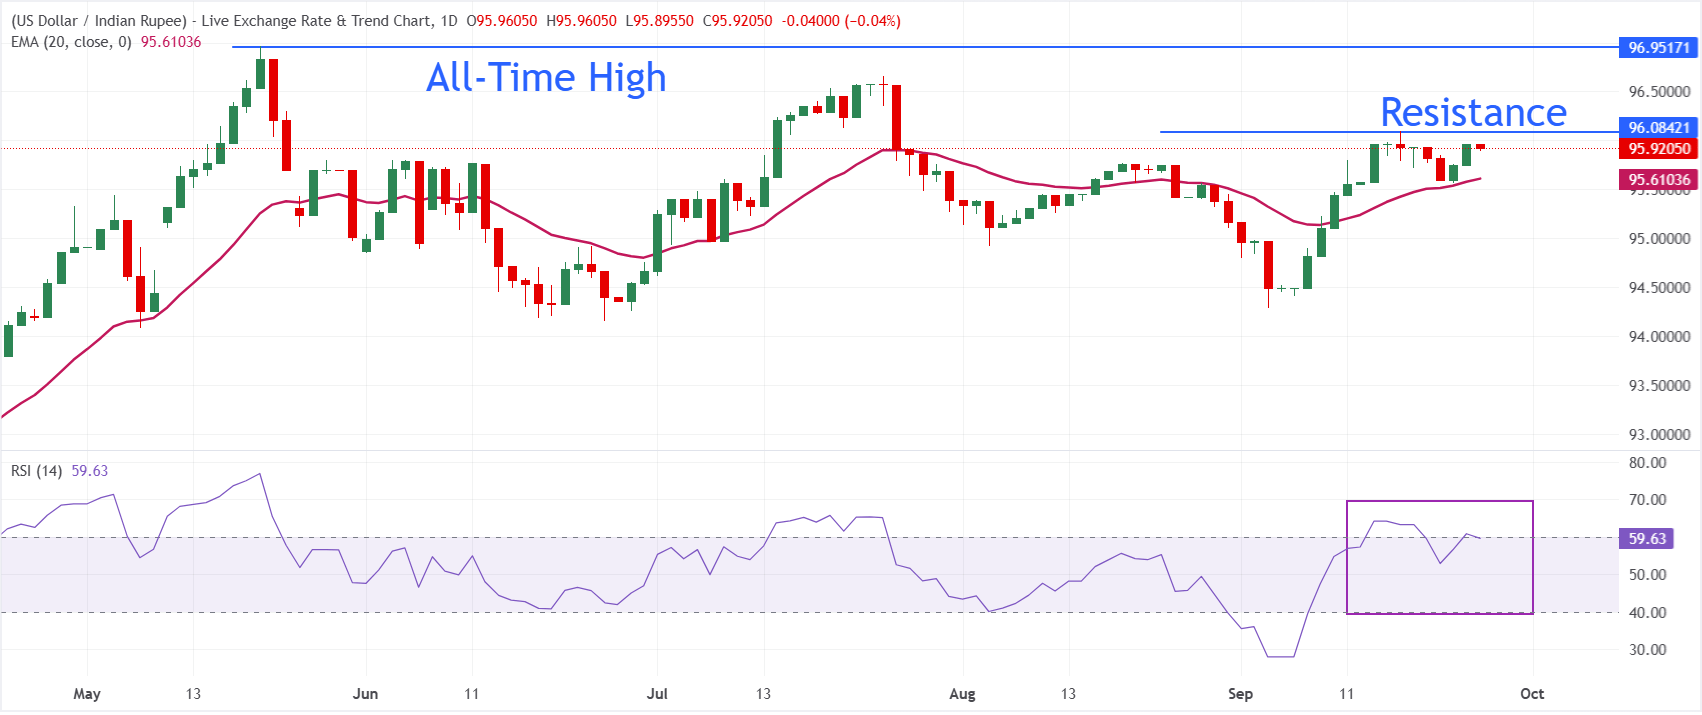
In the daily chart, USD/INR trades at 95.9205, holding a bullish near-term bias as spot remains above the 20-day exponential moving average (EMA) at 95.6104. The price action staying over this short-term EMA suggests underlying demand is intact, while the Relative Strength Index (14) around 59.6 keeps a constructive tone without yet entering overbought territory.
On the downside, initial support is seen at the 20-day EMA clustered near 95.6104, where buyers are likely to defend the current upswing if a pullback unfolds. Looking up, the pair would aim to revisit the all-time high near 97.00 if it manages a decisive break above 96.00
(The technical analysis of this story was written with the help of an AI tool. Know more.)
Indian Rupee FAQs
The Indian Rupee (INR) is one of the most sensitive currencies to external factors. The price of Crude Oil (the country is highly dependent on imported Oil), the value of the US Dollar – most trade is conducted in USD – and the level of foreign investment, are all influential. Direct intervention by the Reserve Bank of India (RBI) in FX markets to keep the exchange rate stable, as well as the level of interest rates set by the RBI, are further major influencing factors on the Rupee.
The Reserve Bank of India (RBI) actively intervenes in forex markets to maintain a stable exchange rate, to help facilitate trade. In addition, the RBI tries to maintain the inflation rate at its 4% target by adjusting interest rates. Higher interest rates usually strengthen the Rupee. This is due to the role of the ‘carry trade’ in which investors borrow in countries with lower interest rates so as to place their money in countries’ offering relatively higher interest rates and profit from the difference.
Macroeconomic factors that influence the value of the Rupee include inflation, interest rates, the economic growth rate (GDP), the balance of trade, and inflows from foreign investment. A higher growth rate can lead to more overseas investment, pushing up demand for the Rupee. A less negative balance of trade will eventually lead to a stronger Rupee. Higher interest rates, especially real rates (interest rates less inflation) are also positive for the Rupee. A risk-on environment can lead to greater inflows of Foreign Direct and Indirect Investment (FDI and FII), which also benefit the Rupee.
Higher inflation, particularly, if it is comparatively higher than India’s peers, is generally negative for the currency as it reflects devaluation through oversupply. Inflation also increases the cost of exports, leading to more Rupees being sold to purchase foreign imports, which is Rupee-negative. At the same time, higher inflation usually leads to the Reserve Bank of India (RBI) raising interest rates and this can be positive for the Rupee, due to increased demand from international investors. The opposite effect is true of lower inflation.
Author

Sagar Dua
FXStreet
Sagar Dua is associated with the financial markets from his college days. Along with pursuing post-graduation in Commerce in 2014, he started his markets training with chart analysis.