Higher, still higher
S&P 500 is reaching for fresh yearly highs, but this isn‘t accompanied by improvements in market breadth – neither stark nor subtle. If anything, the market has become ever more concentrated, with NVDA earnings guidance reflection taking valuations to ridiculous 188. That‘s the AI side of the market, on fire and leading. The only other sectors doing well apart from tech with semis segment, are communications and consumer discretionaries – effect strong enough to overpower badly lagging industrials, materials, financials (chiefly banking), retail, smallcaps and defensives (utilities and staples), which brought about yet another daily bullish call before the opening bell Friday.
Debt ceiling deal hype is another factor going in for the bulls as any sell the news reaction seems to me postponed by a couple of days at least if Yellen moved the new make or break date to Jun 05 (there is still almost $40bn in TGA). Friday saw much of the hope for a deal to be reached soon, priced in – and the tentative one announced this weekend, will likely invite a some sell the news reaction before the AI mania continues. The midnight May 31 vote on it is a downswing risk, but I‘m not looking for a stunner, and instead expect the deal to pass.
So, the only variable the market chose to override Friday, was somewhat hotter core PCE, which didn‘t result in more than a 30min dip. Jun 25bp hike is now the base case scenario, and the short end of the curve isn‘t budging in its bets on Fed pause then, and rate cuts going into 2024. Tech still doesn‘t mind the ever widening disconnect to rates, and apart from AI FOMO, a smaller portion of the explanation is that rates on the long end are approaching their peak, and with the onset of recession (most likely Jul-Aug-Sep), these would retreat to arround midpoint of their yearly range (3.50% for 10-y).
Unless a debt ceiling deal fails, the Fed wouldn‘t back off inflation fight and balance sheet shrinking, and with the Treasury back to issuing fresh debt when commercial bank lending to the private sector isn‘t exactly expanding (crowding out effect), new buyers incl. from abroad would have to step up to the plate – and any flight to safety would have of course negative implications for the stock market standing on increasingly fever legs at a time when LEIs keep still sharply decelerating (inevitable recession)...
S&P 500 and Nasdaq outlook
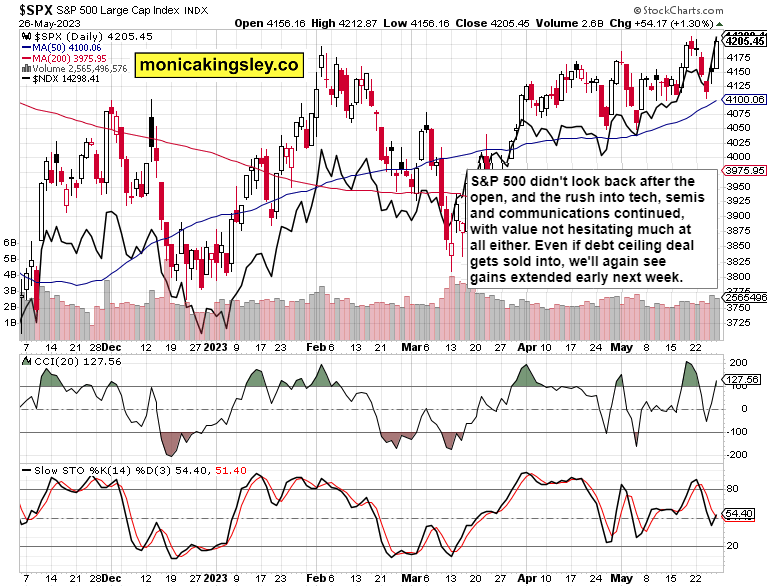
There is still more to squeeze from this rally, no matter how weak internally it is. Bears have to forget about 4,154, and focus on defending (not the indefensible 4,225 but) 4,235 to 4,245 area – that‘s where the bulls will run into concerted selling.
Not that it would decide the fate of this run aka hyped bull market – 4,275 is a logical target if you look at the weekly chart and consider late Apr setback‘s extension magnet for the buyers, which they aren‘t likely to break to the upside before the medium-term bearish factors and recession catch up.
So, remembering what I stated Friday:
(…) That means if you‘re willing to jump in and out fast, you can take the upcoming intraday dip while benefiting from whatever upside next week brings – as a hedge to the medium-term bearish position.
that means you can either chase the remaining upside, minimum as a hedge on the long side, or revert back to or close to the original very wide stop-loss (inititally 4,320, which due to the position sizing relative to dollar value of the given move in percentage terms of your account – my max. 8% rule – shouldn‘t have put you in danger), because I remain convinced we would see meaningful S&P 500 deterioration especially over the summer months. Should the debt ceiling deal announcement not result in a meaningful sell-the-news reaction, I would prefer to reshort from higher levels than to move the current stop-loss considerably higher.
Why then the moves in stop-loss placements this week? That‘s on account of market breadth developments resulting in more or less fuel ahead in the market advance..
The first swallows thereof would coincide with Treasury turning to replenish its account at the Fed, taking off liquidity, which would have a stronger effect than any disinflation progress on Fed easing bets (and don‘t look for disinflation to help too much to drive down nominal wage pressures).
What would though an investor do?
For now, it‘s still going to be about Big Tech, communications and consumer discretionaries with some non-banking financials, dividend aristocrats, and then on longer investment horizon, consumer staples, energy and generally necessities of life, these are to benefit the most.
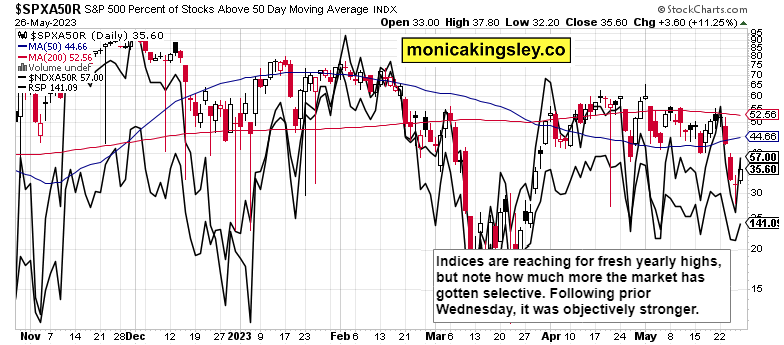
Such an advance breadth isn‘t characteristic of bull markets – the Oct momentum and increasing breadth has become bistory already last year. See equal weighted S&P 500 if in doubt – after the earnings recession, there isn‘t enough momentum in earnings recovery apart from select few and far between.
Credit markets
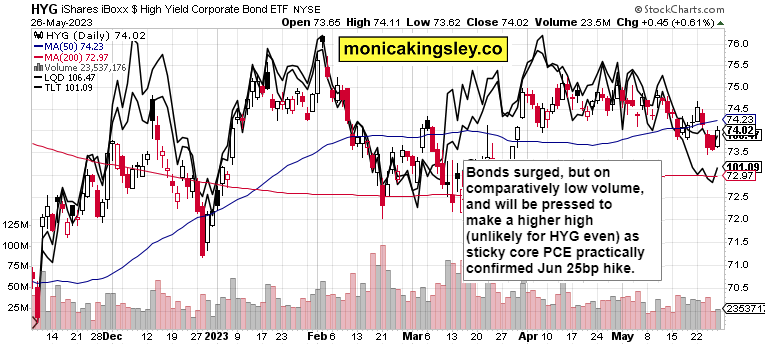
Pause in declining bonds indeed materialized, and would prove temporary and coinciding with the upcoming stock market top. For now, HYG would continue the slow appreciation path, supporting stocks during the remaining upside left. True, when the Jan-May period and the month of May isn‘t a down month, it then takes a while for the positive momentum in stocks to fizzle out, which is exactly what we‘re looking at entering Jun.
Gold, Silver and Miners
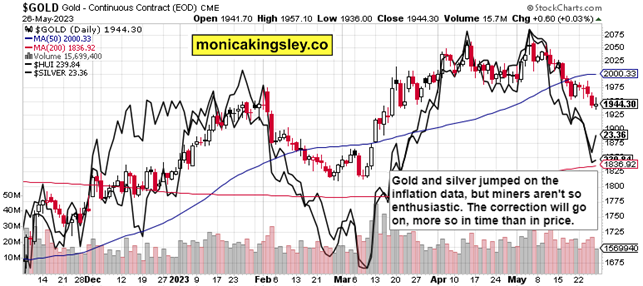
Gold with silver did catch some bid on inflation data with debt ceiling kicking the can down the road Friday advance hopes. Not only thanks to disinflation, the correction has to go further in time, but I remain bullish especially silver, and only then gold when it comes to year end closing prices – thanks to the return of inflation coupled with subpar growth, equals stagflation.
Author

Monica Kingsley
Monicakingsley
Monica Kingsley is a trader and financial analyst serving countless investors and traders since Feb 2020.

















