Gold price rallies to all-time high shy of $2,600 as Fed cuts 50 bps
- Gold reached all-time high at $2,591 post Fed decision.
- Fed delivers a 50 bps as it grows confident that inflation will get to 2% goal.
- Fed dot-plot estimates the fed funds rate to end 2024 at around 4.4%
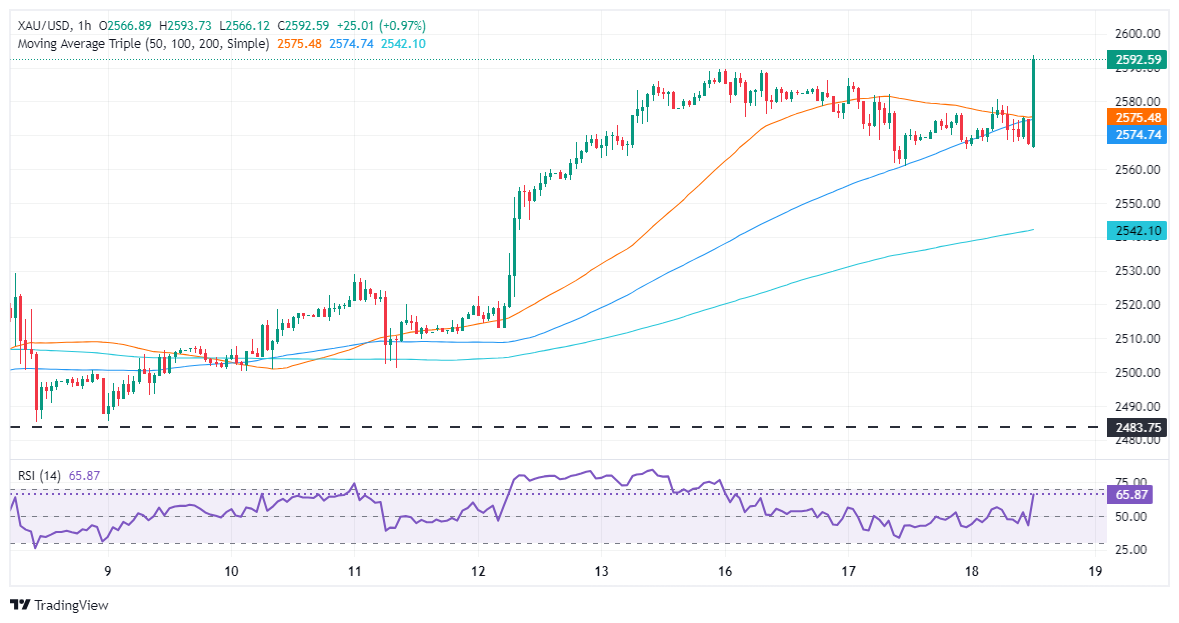
Gold price trades volatile within the $2,565-$2,587 range during the North American session after the Federal Reserve cut rates by 50 bps while expecting the fed funds rates to end in 2024 at around 4.4%, according to the median. At the time of writing, XAU/USD trades post gains of over 0.50%.
Summary of Fed’s monetary policy statement
In their monetary policy statement, Fed officials acknowledge that economic activity continues to expand solidly, though the unemployment rate has “moved up.” They added that although inflation “remains somewhat elevated,” the Committee “has gained greater confidence that inflation is moving sustainably toward 2 percent, and judges that the risks to achieving its employment and inflation goals are roughly in balance.” The FOMC noted that the economic outlook is uncertain.
The Fed’s decision was not unanimous as Governor Michell Bowman voted for a 25 bps rate cut.
Regarding the Summary of Economic Projections (SEP), officials are already expecting another 50 bps of cuts toward the end of 2024 and 100 bps of cuts in 2025.
Gold’s reaction to the Fed’s decision
On the Fed's decision, the gold price reached a new all-time high of $2,591, yet traders prepared for the Fed Chair Powell press conference.
Gold FAQs
Gold has played a key role in human’s history as it has been widely used as a store of value and medium of exchange. Currently, apart from its shine and usage for jewelry, the precious metal is widely seen as a safe-haven asset, meaning that it is considered a good investment during turbulent times. Gold is also widely seen as a hedge against inflation and against depreciating currencies as it doesn’t rely on any specific issuer or government.
Central banks are the biggest Gold holders. In their aim to support their currencies in turbulent times, central banks tend to diversify their reserves and buy Gold to improve the perceived strength of the economy and the currency. High Gold reserves can be a source of trust for a country’s solvency. Central banks added 1,136 tonnes of Gold worth around $70 billion to their reserves in 2022, according to data from the World Gold Council. This is the highest yearly purchase since records began. Central banks from emerging economies such as China, India and Turkey are quickly increasing their Gold reserves.
Gold has an inverse correlation with the US Dollar and US Treasuries, which are both major reserve and safe-haven assets. When the Dollar depreciates, Gold tends to rise, enabling investors and central banks to diversify their assets in turbulent times. Gold is also inversely correlated with risk assets. A rally in the stock market tends to weaken Gold price, while sell-offs in riskier markets tend to favor the precious metal.
The price can move due to a wide range of factors. Geopolitical instability or fears of a deep recession can quickly make Gold price escalate due to its safe-haven status. As a yield-less asset, Gold tends to rise with lower interest rates, while higher cost of money usually weighs down on the yellow metal. Still, most moves depend on how the US Dollar (USD) behaves as the asset is priced in dollars (XAU/USD). A strong Dollar tends to keep the price of Gold controlled, whereas a weaker Dollar is likely to push Gold prices up.
Author

Christian Borjon Valencia
FXStreet
Markets analyst, news editor, and trading instructor with over 14 years of experience across FX, commodities, US equity indices, and global macro markets.
















