GBP/USD rallies past 1.2800 amid soft US NFP
- GBP/USD rallies to 1.2845, a gain of 0.83%, following softer-than-expected US Nonfarm Payrolls figures that added pressure on the US Dollar.
- The US economy added just 209K jobs in June, below estimates of 225K, leading to a drop in the value of the US Dollar across the board.
- On the UK front, despite fears of a possible recession scenario, the swaps market continues to forecast several more rate hikes by the Bank of England, potentially as high as 6%.


GBP/USD rallied sharply after briefly edging towards its daily low of 1.2725, but soft data from the United States (US) weighed on the US Dollar (USD), opening the door for a GBP late bounce. At the time of writing, the GBP/USD is past the 1.2800 figure, trading at 1.2845, and gains 0.83%.
Pound Sterling rallies as soft US labor data weighs on the US Dollar
Key economic data from the US, particularly Nonfarm Payrolls figures for June, showed the economy adding just 209K jobs, below estimates of 225K, spurring US Dollar weakness across the board. Furthermore, the Unemployment Rate portrayed a tight labor market, decelerating from 3.7% to 3.6% in June, while Average Hourly Earning (AHE) expanded 4.4% YoY, above the prior’s month 4.2%, adding to inflationary pressures, keeping the US Federal Reserve (Fed) under pressure.
GBP/USD reacted upwards and claimed the 1.2800 mark. Once market analysts dissected the US Nonfarm Payrolls report, the GBP/USD extended its gains past the R1 daily pivot at 1.2840. Consequently, the US Dollar Index (DXY), a measure of the performance of a basket of six currencies against the buck, falls 0.83%, down at 102.249, a tailwind for the GBP/USD.
US Treasury bond yields, mainly the 10-year Treasury note, yielding 4.042%, are almost unchanged. Although the labor market is showing signs of cooling down, traders remain certain the US Federal Reserve (Fed) will increase rates by 25 bps at the July 25-26 meeting, as shown by the CME FedWatch Tool. Odds are at 92.4%, higher than last week’s 86.8%. Nevertheless, they seem not convinced the Fed will hike twice, as the Fed’s dot-plot portrayed.
Of late, Chicago Fed President Aaron Golsbee expressed that the labor market remains strong but cooling. Golsbee added that inflation is too high and that 1 or 2 more rate hikes could be needed to tame elevated inflation.
On the United Kingdom front, the Bank of England (BoE) Governor Andrew Bailey said they must act now to bring inflation to heel, allowing market participants to maintain bets of several more hikes before the Bank decides the end credits of this tightening season roll. The swaps market still shows the BoE will raise rates as high as 6%, even though recent manufacturing and services business activity polls portrayed a possible recession scenario in the country.
Given the fundamental backdrop, further GBP/USD upside is expected, but woes about a UK recession would cap the Pound Sterling (GBP) uptrend. If data proves right, and the UK’s economy remains resilient, the GBP/USD could challenge the 1.3000 figure in the medium term.
GBP/USD Price Analysis: Technical outlook
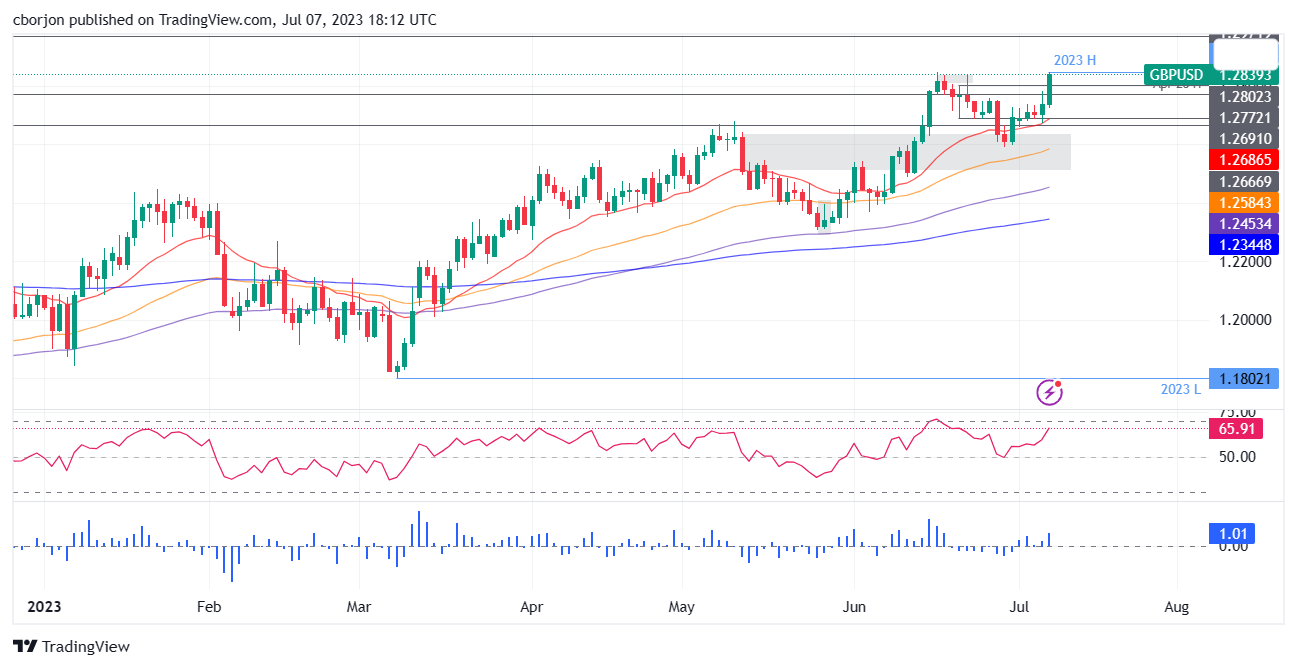
From a technical perspective, the GBP/USD rose to new year-to-date (YTD) highs of 1.2849 after the US data release. If GBP/USD prints a daily close above 1.2850, the 1.2900 figure would be up for grabs. Further rallies could challenge the 1.3000 mark. Conversely, GBP/USD’s failure to register a daily close above 1.2850 would exacerbate a dip towards 1.2800. Break below will expose 1.2700, followed by the 20-day EMA at 1.2687.
Author
Christian Borjon Valencia
FXStreet
Markets analyst, news editor, and trading instructor with over 14 years of experience across FX, commodities, US equity indices, and global macro markets.
















