GBP/USD Extends upbeat rally as US CPI inflation cools
- GBP/USD found the gas pedal and extended into a two-day bull run.
- US CPI inflation cooled in June, and reigniting rate-cut bets.
- US PPI wholesale inflation on the docket for Friday.

GBP/USD extended into a second day of a topside run, breaking through a firm supply zone and setting a fresh peak for 2024 near 1.2950. The pair set a new 50-week high as the Greenback tumbled across the board after US Consumer Price Index (CPI) inflation cooled to its lowest levels since 2021.
Forex Today: Focus remains on US inflation
In June, US CPI inflation was lower than expected. The annualized headline CPI inflation dropped to 3.0% YoY from the previous 3.3%, lower than the forecasted 3.1%. Additionally, CPI inflation decreased by -0.1% MoM in June, down from the previous month’s 0.0% and below the expected 0.1%.
For the week ending July 5, US Initial Jobless Claims decreased to 222K, down from the revised 239K of the previous week and better than the forecasted 236 K. This decline in jobless claims reduced the four-week average to 233.5K from the previous 238.75 K.
Due to the accelerated cooling of US CPI inflation, market expectations for a rate hike from the Federal Reserve (Fed) are now indicating the possibility of three quarter-point rate cuts in 2024. The CME’s FedWatch Tool is showing a 95% increase in the likelihood of a rate cut in September.
With US CPI data out of the way, all that’s left for the week is Friday’s US Producer Price Index (PPI) wholesale inflation print, which could throw a wrench in the works for rate-cut hopefuls. Core PPI for the year ended in June is expected to tick upwards to 2.5% from the previous 2.3% as businesses continue to face higher cost pressures than the Fed would like to see.
British Pound PRICE Today
The table below shows the percentage change of British Pound (GBP) against listed major currencies today. British Pound was the strongest against the Japanese Yen.
| USD | EUR | GBP | JPY | CAD | AUD | NZD | CHF | |
|---|---|---|---|---|---|---|---|---|
| USD | 0.00% | -0.01% | 0.32% | 0.00% | -0.06% | 0.14% | 0.07% | |
| EUR | -0.01% | -0.02% | 0.36% | -0.01% | -0.08% | 0.12% | 0.04% | |
| GBP | 0.01% | 0.02% | 0.37% | 0.00% | -0.07% | 0.14% | 0.05% | |
| JPY | -0.32% | -0.36% | -0.37% | -0.37% | -0.41% | -0.23% | -0.29% | |
| CAD | -0.01% | 0.00% | -0.01% | 0.37% | -0.07% | 0.12% | 0.04% | |
| AUD | 0.06% | 0.08% | 0.07% | 0.41% | 0.07% | 0.20% | 0.13% | |
| NZD | -0.14% | -0.12% | -0.14% | 0.23% | -0.12% | -0.20% | -0.07% | |
| CHF | -0.07% | -0.04% | -0.05% | 0.29% | -0.04% | -0.13% | 0.07% |
The heat map shows percentage changes of major currencies against each other. The base currency is picked from the left column, while the quote currency is picked from the top row. For example, if you pick the British Pound from the left column and move along the horizontal line to the US Dollar, the percentage change displayed in the box will represent GBP (base)/USD (quote).
GBP/USD technical outlook
The Cable’s Thursday bull run dragged the pair into a 50-week peak just shy of 1.2950, and the pair is up 2.65% from July’s early swing low near 1.2615.
Daily candlesticks have resumed a near-term topside run, closing in the green for all but two of the last eleven consecutive trading days. It’s the bulls’ game to lose as a bearish turnaround from here will drag GBP/USD back into major technical levels near the 200-day Exponential Moving Average (EMA) at 1.2606.
GBP/USD hourly chart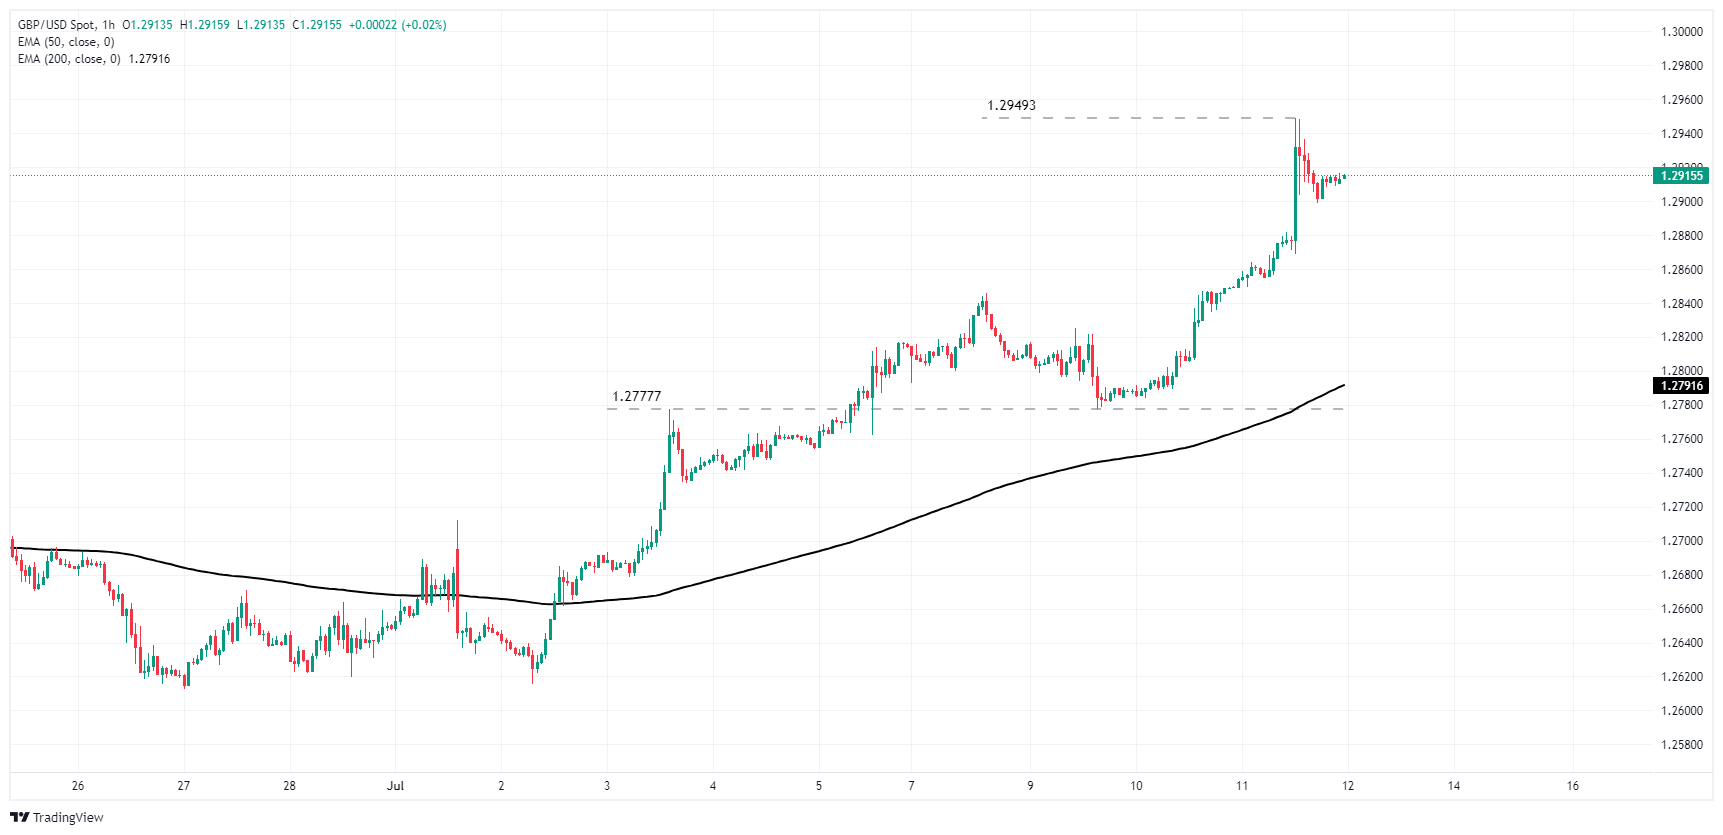
GBP/USD daily chart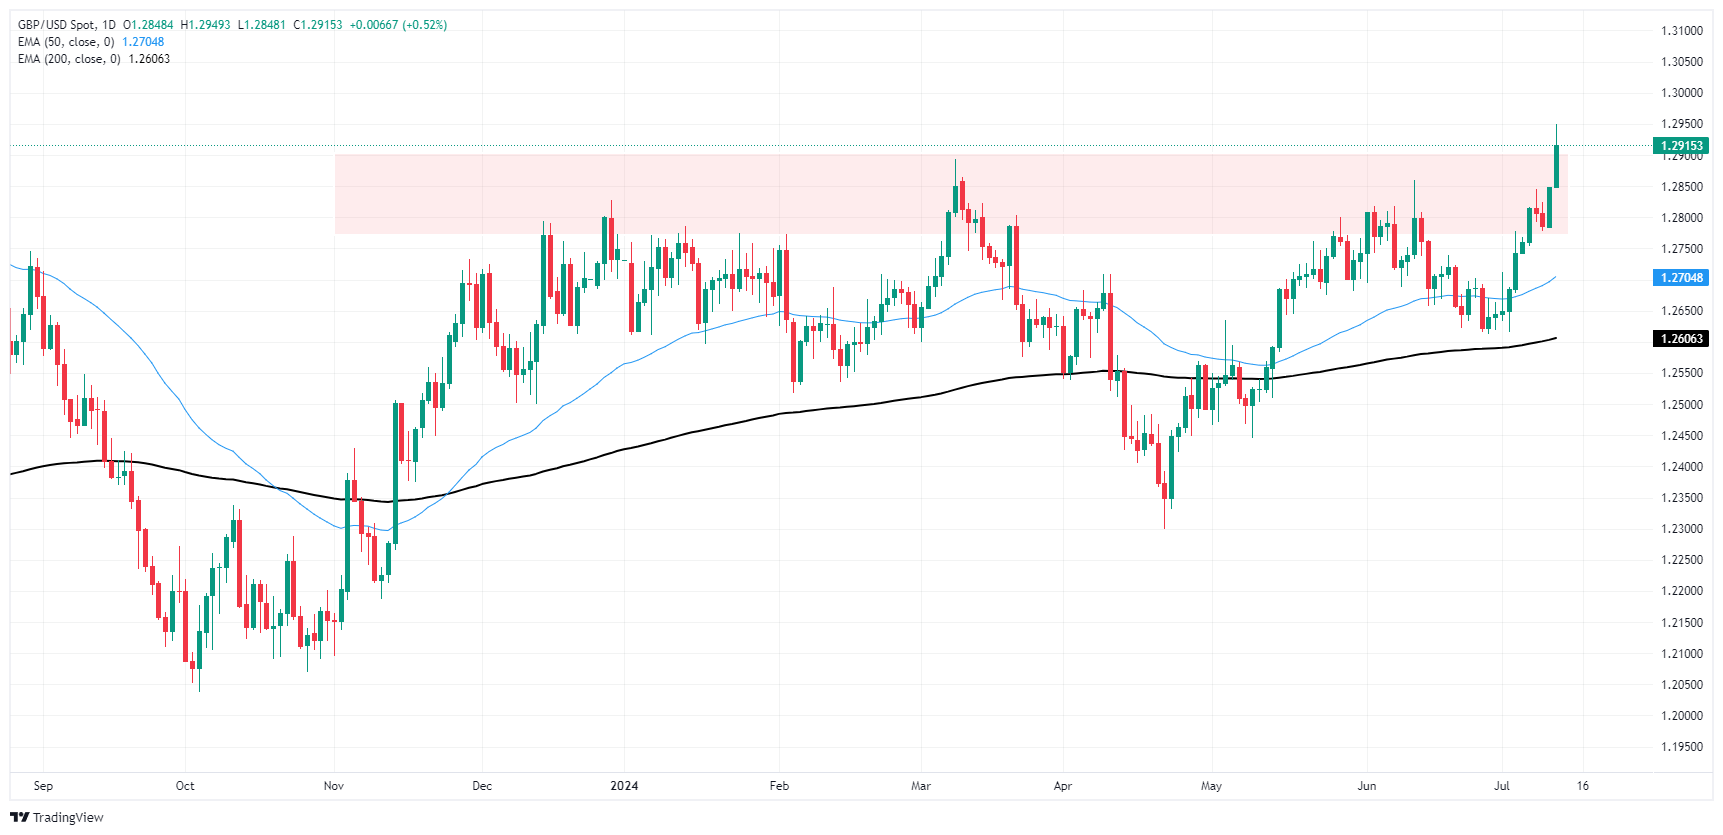
Pound Sterling FAQs
The Pound Sterling (GBP) is the oldest currency in the world (886 AD) and the official currency of the United Kingdom. It is the fourth most traded unit for foreign exchange (FX) in the world, accounting for 12% of all transactions, averaging $630 billion a day, according to 2022 data. Its key trading pairs are GBP/USD, aka ‘Cable’, which accounts for 11% of FX, GBP/JPY, or the ‘Dragon’ as it is known by traders (3%), and EUR/GBP (2%). The Pound Sterling is issued by the Bank of England (BoE).
The single most important factor influencing the value of the Pound Sterling is monetary policy decided by the Bank of England. The BoE bases its decisions on whether it has achieved its primary goal of “price stability” – a steady inflation rate of around 2%. Its primary tool for achieving this is the adjustment of interest rates. When inflation is too high, the BoE will try to rein it in by raising interest rates, making it more expensive for people and businesses to access credit. This is generally positive for GBP, as higher interest rates make the UK a more attractive place for global investors to park their money. When inflation falls too low it is a sign economic growth is slowing. In this scenario, the BoE will consider lowering interest rates to cheapen credit so businesses will borrow more to invest in growth-generating projects.
Data releases gauge the health of the economy and can impact the value of the Pound Sterling. Indicators such as GDP, Manufacturing and Services PMIs, and employment can all influence the direction of the GBP. A strong economy is good for Sterling. Not only does it attract more foreign investment but it may encourage the BoE to put up interest rates, which will directly strengthen GBP. Otherwise, if economic data is weak, the Pound Sterling is likely to fall.
Another significant data release for the Pound Sterling is the Trade Balance. This indicator measures the difference between what a country earns from its exports and what it spends on imports over a given period. If a country produces highly sought-after exports, its currency will benefit purely from the extra demand created from foreign buyers seeking to purchase these goods. Therefore, a positive net Trade Balance strengthens a currency and vice versa for a negative balance.
Author

Joshua Gibson
FXStreet
Joshua joins the FXStreet team as an Economics and Finance double major from Vancouver Island University with twelve years' experience as an independent trader focusing on technical analysis.
















