Canadian Dollar holds steady as US government reopens, ADP data disappoints
- CAD trades near 1.3635 against USD on Wednesday, little changed from the previous session.
- ADP private payrolls rose just 22,000 in January, well below expectations; official NFP delayed to next week.
- Treasury Secretary Bessent testifies before Congress; oil prices climb toward $64 on Middle East tensions.
The Canadian Dollar (CAD) held steady against the US Dollar (USD) on Wednesday, trading just below 1.3700 as markets adjusted to the end of the partial US government shutdown and digested a soft private payrolls report. The Loonie has pulled back from sixteen-month highs hit in late January, with the retreat driven by softer Canadian growth data and a modest rebound in USD demand following the nomination of Kevin Warsh as Federal Reserve (Fed) Chair.
President Donald Trump signed a $1.2 trillion funding package into law on Tuesday, ending the three-day partial shutdown. Federal agencies reopened Wednesday morning, though Department of Homeland Security funding was extended for only two weeks as lawmakers continue negotiations over immigration enforcement reforms. The quick resolution removed one source of market uncertainty, though the brief closure forced the Bureau of Labor Statistics (BLS) to delay this week's key labor data releases.
ADP misses estimates, NFP pushed to next week
The ADP National Employment Report showed private payrolls increased by just 22K in January, well below market expectations for a stronger reading. The report highlighted that job creation slowed considerably in 2025, with private employers adding only 398K positions for the full year, compared to 771K in 2024. The weak print carried extra weight given the postponement of official government data.
The BLS confirmed that the January Nonfarm Payrolls (NFP) report, originally scheduled for Friday, February 6, will be rescheduled once government funding is fully restored. The December Job Openings and Labor Turnover Survey (JOLTS) data was also delayed. Markets had expected NFP to show an increase of roughly 55K jobs with unemployment holding at 4.4%. The January release typically includes annual benchmark revisions and updated seasonal adjustment factors, making its eventual publication closely watched.
Bessent faces lawmakers on tariffs and inflation
Treasury Secretary Scott Bessent appeared before the House Financial Services Committee on Wednesday, facing sharp questions from Democratic lawmakers about the administration's tariff policies and their impact on consumer prices. In heated exchanges, Bessent acknowledged his earlier statements that tariffs could be inflationary were "mistaken," pointing to economic growth and declining inflation as evidence that tariff-related price pressures had not materialized as critics warned.
Bessent also warned against overregulation of the financial sector, characterizing the previous administration's approach as "regulation by reflex." The testimony came as markets await a Supreme Court ruling on whether the administration's trade duties exceeded presidential authority. Bessent is scheduled to appear before the Senate Banking Committee on Thursday.
Oil prices climb on Middle East tensions
West Texas Intermediate (WTI) crude oil futures climbed toward $64 per barrel on Wednesday after the US military downed an Iranian drone near a US aircraft carrier in the Arabian Sea. The incident unsettled energy markets, though President Trump emphasized that diplomatic channels with Iran remain open and talks are still scheduled. API data showing an 11.1 million barrel draw in US crude inventories, the largest since June if confirmed, added further support.
The US Dollar Index (DXY) held near 97.4 on Wednesday, pausing its recent rebound from a near six-year low. The index found mild support following the strong ISM Manufacturing print earlier this week, though the lack of official labor data kept traders cautious. Rate markets continue to price roughly a 70% chance the Fed will hold rates through April, with the first cut of 2026 expected around June.
Daily digest market movers: ADP disappoints as NFP gets pushed back
- USD/CAD trades near 1.3635, little changed on the session as the Loonie consolidates below sixteen-month highs.
- ADP private payrolls rose 22,000 in January, below expectations; full-year 2025 job creation totaled just 398,000.
- BLS delays January NFP and December JOLTS releases due to partial government shutdown; rescheduled dates pending.
- WTI crude climbs toward $64/bbl after US downs Iranian drone; API reports 11.1 million barrel inventory draw.
- Bessent tells Congress his earlier view that tariffs were inflationary was mistaken; faces lawmakers on economic policy.
- DXY holds near 97.4; rate markets see Fed on hold through April with first cut likely in June.
Canadian Dollar price forecast
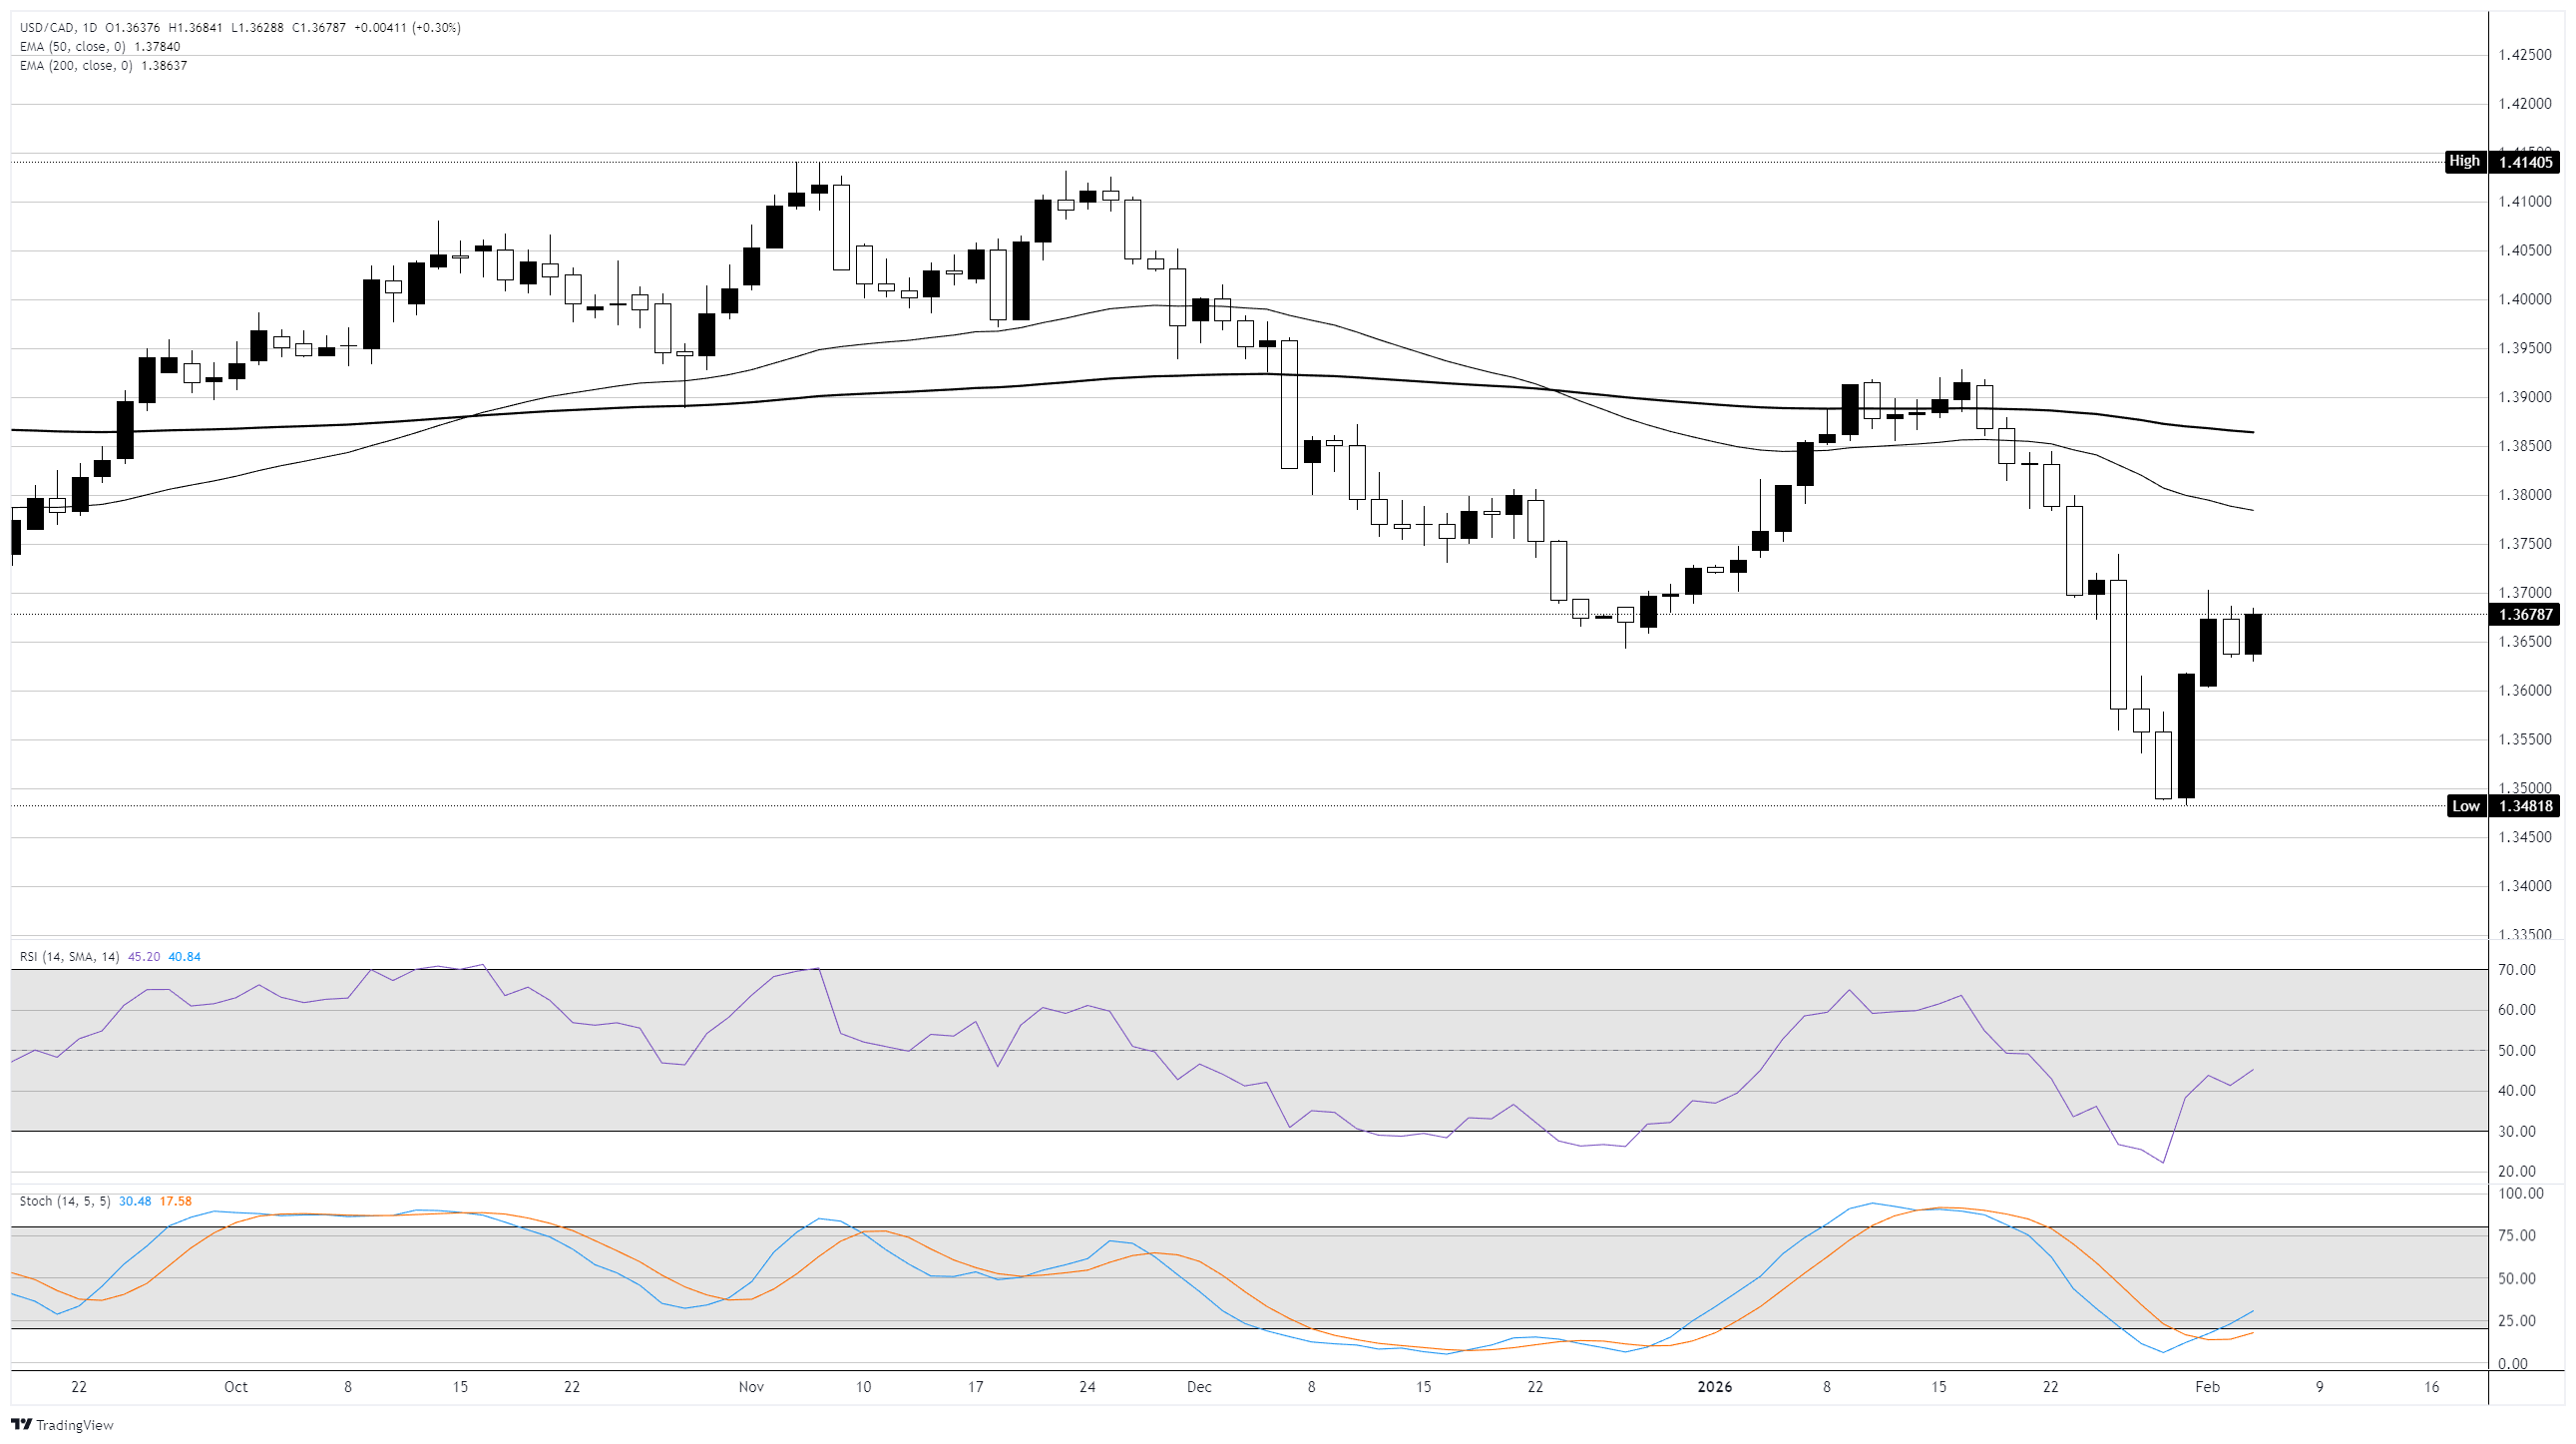
USD/CAD trades near 1.3635 on Wednesday, holding within a familiar range after retreating from the late-January low near 1.3490. The pair has bounced off the 2025 swing lows as the US Dollar found renewed demand following the Warsh nomination and firmer ISM data. The 50-day Exponential Moving Average (EMA) near 1.3700 marks the first layer of resistance, with the 200-day EMA and the 2026 yearly open clustered around 1.3725-1.3735.
Support near 1.3540, resistance at 1.3700
On the downside, initial support lies near 1.3600, followed by the 2025 swing low at 1.3540. A weekly close below that threshold would signal renewed bearish momentum and open the door to a test of 1.3430. On the upside, a clear break above the 1.3725-1.3735 zone would suggest a more significant low is in place, with subsequent resistance at the 1.3930-1.3970 area.
RSI neutral as pair consolidates
The Relative Strength Index (RSI) on the daily chart hovers in the mid-range near 45-50, indicating neither overbought nor oversold conditions. This neutral reading matches the choppy price action as the pair consolidates after January's sharp decline. For now, the broader downtrend stays in place while USD/CAD holds below the key moving averages, though a break above 1.3735 would shift the near-term tone to consolidation or recovery.
USD/CAD daily chart
Canadian Dollar FAQs
The key factors driving the Canadian Dollar (CAD) are the level of interest rates set by the Bank of Canada (BoC), the price of Oil, Canada’s largest export, the health of its economy, inflation and the Trade Balance, which is the difference between the value of Canada’s exports versus its imports. Other factors include market sentiment – whether investors are taking on more risky assets (risk-on) or seeking safe-havens (risk-off) – with risk-on being CAD-positive. As its largest trading partner, the health of the US economy is also a key factor influencing the Canadian Dollar.
The Bank of Canada (BoC) has a significant influence on the Canadian Dollar by setting the level of interest rates that banks can lend to one another. This influences the level of interest rates for everyone. The main goal of the BoC is to maintain inflation at 1-3% by adjusting interest rates up or down. Relatively higher interest rates tend to be positive for the CAD. The Bank of Canada can also use quantitative easing and tightening to influence credit conditions, with the former CAD-negative and the latter CAD-positive.
The price of Oil is a key factor impacting the value of the Canadian Dollar. Petroleum is Canada’s biggest export, so Oil price tends to have an immediate impact on the CAD value. Generally, if Oil price rises CAD also goes up, as aggregate demand for the currency increases. The opposite is the case if the price of Oil falls. Higher Oil prices also tend to result in a greater likelihood of a positive Trade Balance, which is also supportive of the CAD.
While inflation had always traditionally been thought of as a negative factor for a currency since it lowers the value of money, the opposite has actually been the case in modern times with the relaxation of cross-border capital controls. Higher inflation tends to lead central banks to put up interest rates which attracts more capital inflows from global investors seeking a lucrative place to keep their money. This increases demand for the local currency, which in Canada’s case is the Canadian Dollar.
Macroeconomic data releases gauge the health of the economy and can have an impact on the Canadian Dollar. Indicators such as GDP, Manufacturing and Services PMIs, employment, and consumer sentiment surveys can all influence the direction of the CAD. A strong economy is good for the Canadian Dollar. Not only does it attract more foreign investment but it may encourage the Bank of Canada to put up interest rates, leading to a stronger currency. If economic data is weak, however, the CAD is likely to fall.
Author

Joshua Gibson
FXStreet
Joshua joins the FXStreet team as an Economics and Finance double major from Vancouver Island University with twelve years' experience as an independent trader focusing on technical analysis.

















