Week Ahead on Wall Street (SPY) (QQQ): Only way is up as Fed talks taper, jobs jump and yields slump
- Equity markets look increasingly bullish as everything rallies.
- The Fed does its job in talking the taper but avoiding the tantrum.
- Yields drop, stocks pop, everyone is long, so what can go wrong?

Another week in what is fast becoming the twilight zone markets where we enter an alternative universe in which stocks never go down and shorts and bears get roasted daily. Perhaps that reference is a bit outdated but the current market is more like stranger things. Doesn't this feel a little weird to you? Does anything ever go down? Should you even care? Not really that is not your job. Your job as a trader is to make money, not sit there analyzing the why of it all. Some things do go down if poor old Peloton (PTON) is anything to go by. The former lockdown darling had some tough comparisons to keep up with from last year and fair to say it got dropped off the back of the peloton or spat out the back of the treadmill. Volatility among second-tier stocks or so-called meme names is exorbitant these days and 20-30% moves are not that unexpected. Or even 100% in the case of Avis Budget (CAR) as it went parabolic earlier in the week on the back of strong earnings. Speaking of rental cars, Hertz and Tesla spring to mind and whatever the mechanics of that tit for tat, will they won't they order, Tesla (TSLA) takes the crown for stock of the week in our view. What a move for a mega-cap. The large options expiry today is seeing a little struggle but overall it is the tech titan.
The Fed took to the airwaves on Wednesday with its usual cautious, conservative tone. Markets liked what they heard though as taper was talked but slow slowly was the mantra. Some humour was injected into proceedings when the Fed was asked to explain its definition of transitory but the mood was buoyant afterward as yields fell setting up the equities crowd for more exuberance. The dollar surged as rate hikes are likely and Friday's jobs report put fears of stagflation to the sidelines. This is perhaps the most accommodative background to further gains we have seen this year. Usually, that gives us a little twitch and we do need to wonder what is coming over the horizon. With Evergrande off the table, another Chinese developer took the stage with trading in Kaisa Group suspended overnight as it struggled to fire-sale assets to meet its debt repayments.
We can pretty much call this earnings season now as nearly 450 of the S&P 500 companies have reported. No surprise it is another blowout with 80.7% of companies beating earnings estimates, slightly down from last quarters near 85% beat rate. The long-term average though is more like 65%. Data from Refinitiv Lipper Alpha.
Something may sail over the horizon to torpedo this ridiculously high bullish sentiment. The latest data from the American Association of Individual Investors (AAII) shows bulls in ascendency but levels have been higher in April this year. The long-term average is nearer 7% though so 2021 is a crazily bullish year and so it should be.
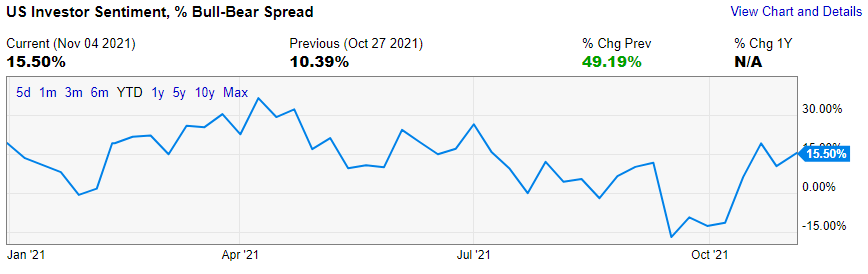
Source: Ycharts
Meanwhile, those fund managers just can't get enough of a good thing as the net equity position heads into heavy longs with a reading over 107% from the National Association of American Investment Managers (NAAIM). It should be noted that the majority are benchmarked to the S&P or Nasdaq so they have to be long. But this is still a reasonable move above 100% long.
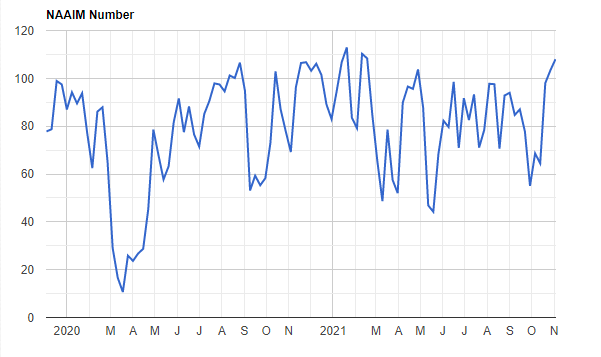
Source: National Association of American Investment Managers
Stock market flows
No surprise to see another week of Exchange Traded Fund (ETF) inflows to the equity space. $8 billion poured in, the fifth consecutive week of gains according to Refinitiv Lipper Alpha. The big winners were the SPDR S&P 500 (SPY) and the Healthcare sector XLV.
SPY stock forecast
We found this interesting if nothing else, with a positive close today that will mark 7 straight days of gains for the S&P 500 (SPY). Statistically, that is low probability so Monday is odds on then for a down day. Also, we found interesting is the retracement to the previous support trendline now acting as resistance. Nothing too significant but an interesting observation on how far the SPY has rallied and perhaps offering some resistance up here. Support on any pullback comes from the previous high at $453 zone. We still feel an imminent 10% pullback coming which should set up a final 20% holiday rally to close out the year on a high.
Earnings due
Disney (DIS) the highlight on Wednesday with retail favourite NIO also up before that on Tuesday.
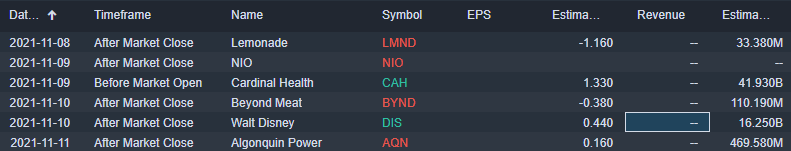
Source: Benzinga Pro
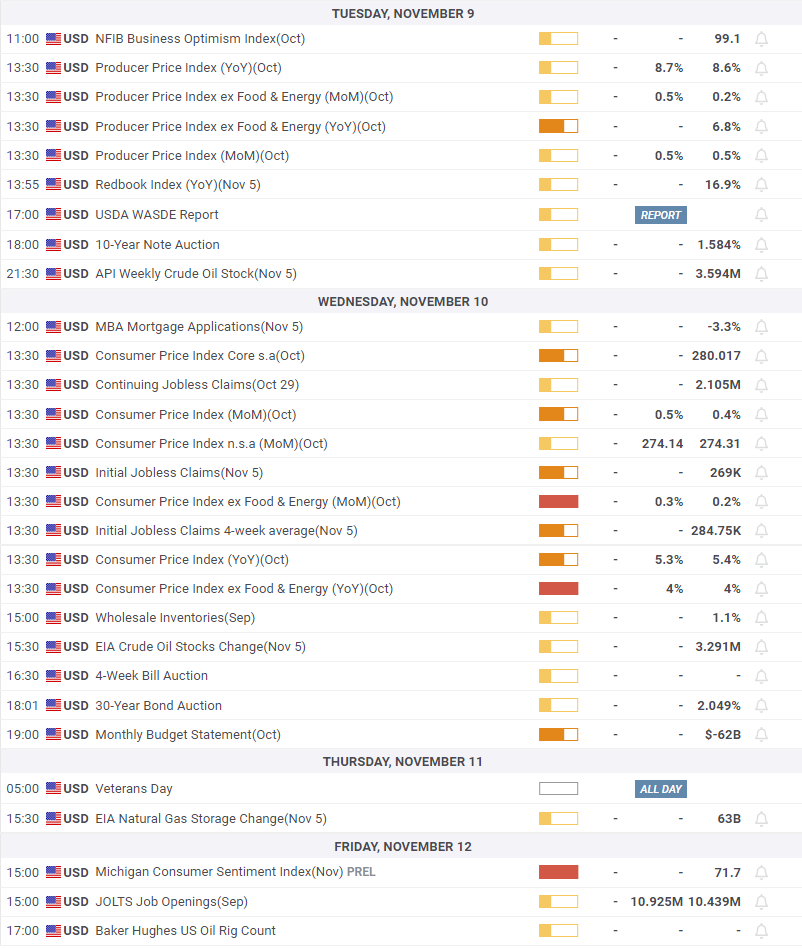
Economic releases
You're still reading down here? Wow, thanks for making it this far. Ok, there's nothing more to do. It's the weekend!
Author

Ivan Brian
FXStreet
Ivan Brian started his career with AIB Bank in corporate finance and then worked for seven years at Baxter. He started as a macro analyst before becoming Head of Research and then CFO.
















