US-Iran war lifts Oil as Yen carry unwind risk grows
The US-Iran ceasefire has effectively broken down after another weekend of attacks around the Strait of Hormuz.
Iran said the waterway was closed to unauthorised vessels after another commercial ship was hit. The United States answered with a larger wave of strikes on Iranian military targets, while Iran retaliated against facilities linked to US forces across the Gulf.
The immediate market response was familiar: oil rose, equity futures weakened and bond yields moved higher. Markets have repeatedly seen this pitter-patter sequence of attack, retaliation and eventual negotiation.
That history explains why traders are reluctant to price a complete shutdown. Previous oil spikes have faded quickly once talks resumed or escorted shipping continued.
This episode still deserves more attention. The ceasefire is formally over, commercial traffic has slowed and the central dispute remains unresolved: Iran wants authority over passage, while Washington is demanding free access through recognised lanes.
The more likely near-term outcome remains another narrow shipping arrangement rather than permanent peace or an uncontrollable closure. However, each temporary deal now looks less durable than the one before it.
Oil becomes an inflation story again
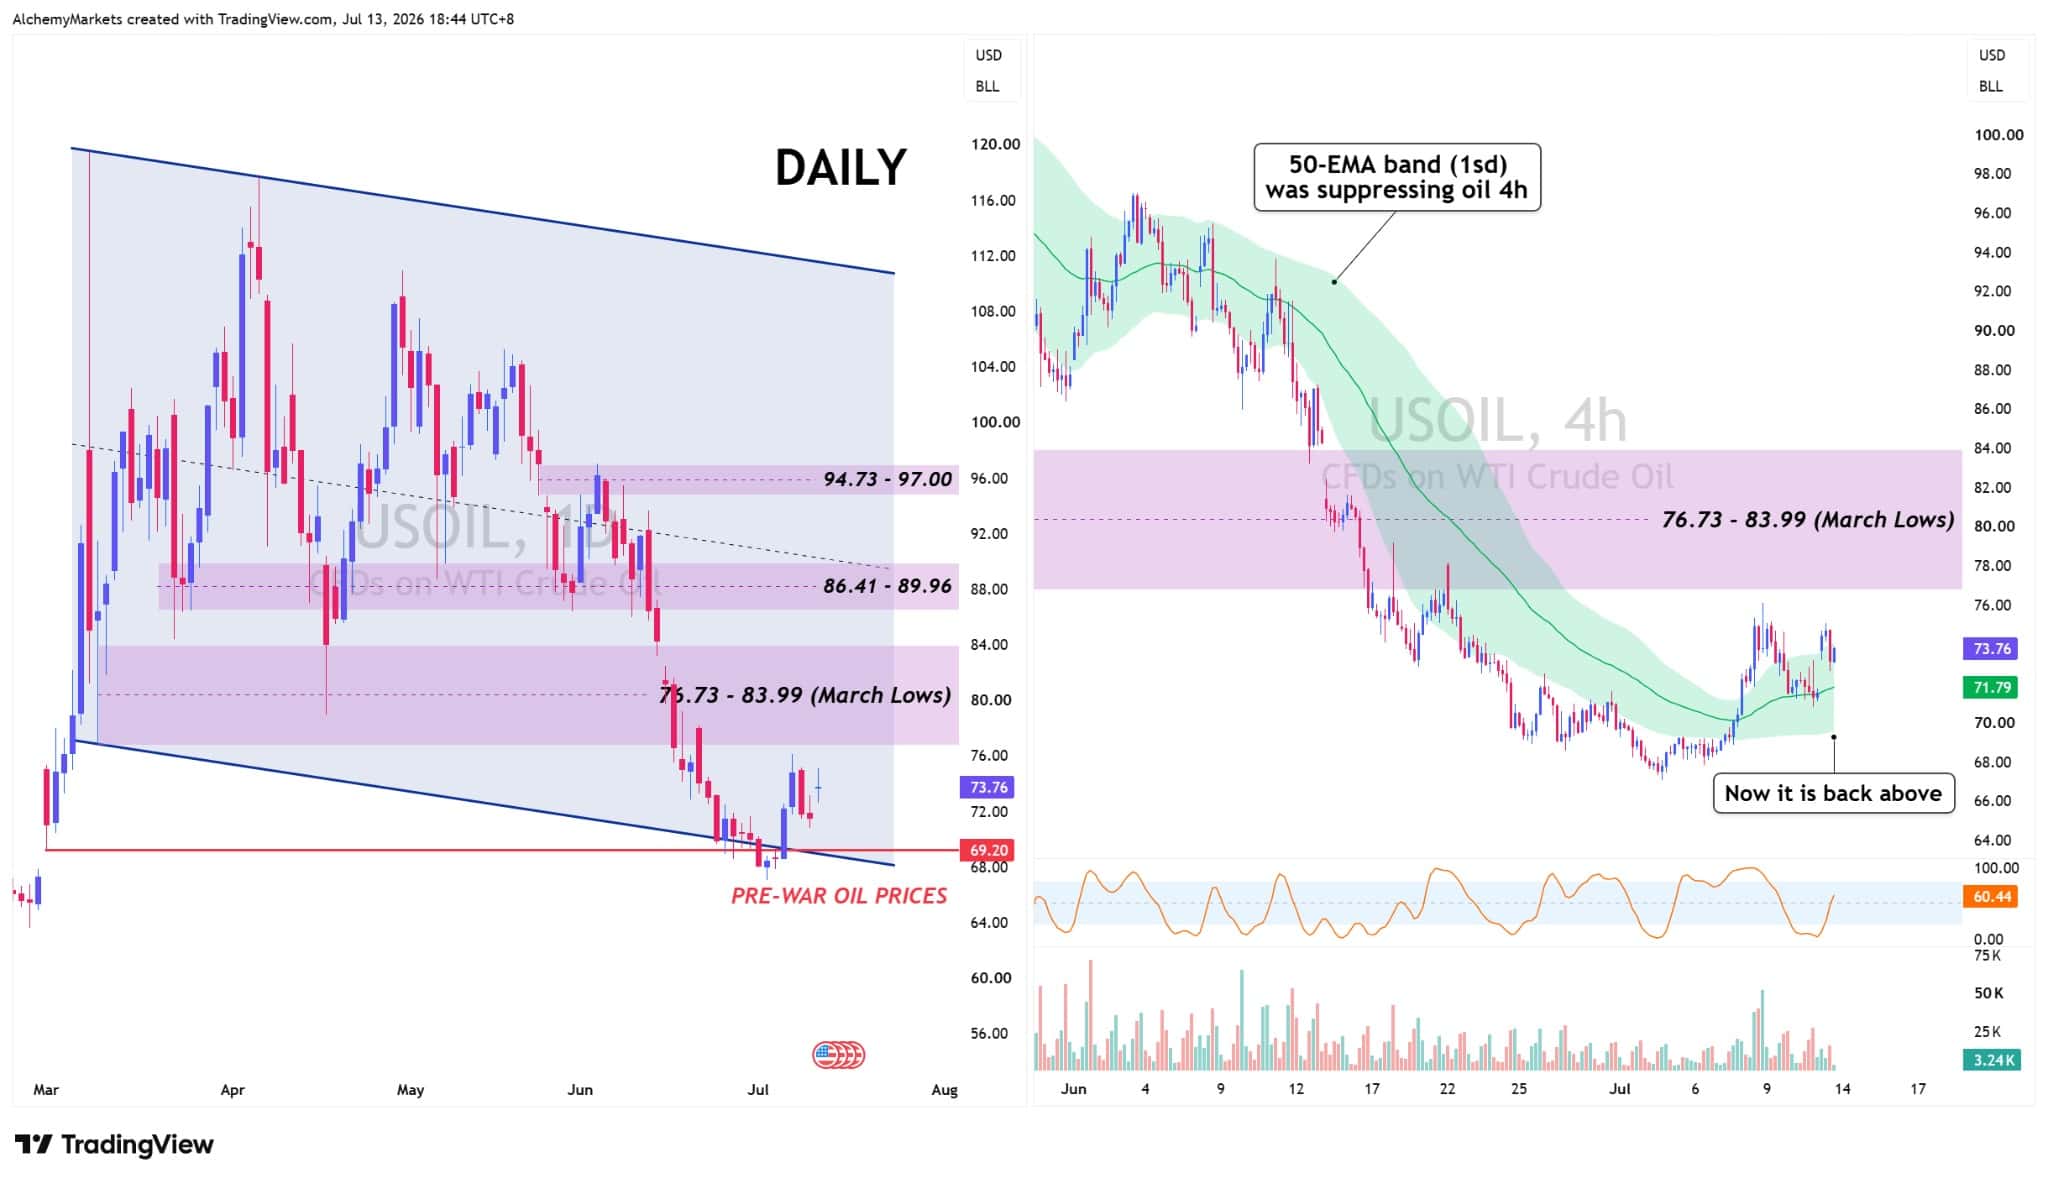
WTI has rebounded from the $69.20 pre-war area and moved back above its four-hour 50-EMA band. Price is improving, but the $76.73 to $83.99 resistance zone remains the main test.
Oil does not need to return to $100 to influence markets. A sustained move into that zone could slow the decline in headline inflation, keep the Federal Reserve cautious and place upward pressure on short-term Treasury yields.
Energy producers may benefit from stronger realised prices, while airlines and other fuel-sensitive businesses face higher costs. Expensive technology and semiconductor stocks are also exposed if firmer oil pushes yields higher.
If WTI spikes and fades, markets may treat the move as another temporary war premium. Holding above the reclaimed trend band would suggest the conflict is becoming an inflation and policy story.
USD/JPY adds a second market risk
Higher oil initially works against the yen because Japan imports most of its energy. It raises the country’s import bill while inflation risk can keep US yields elevated, preserving the rate advantage behind USDJPY.
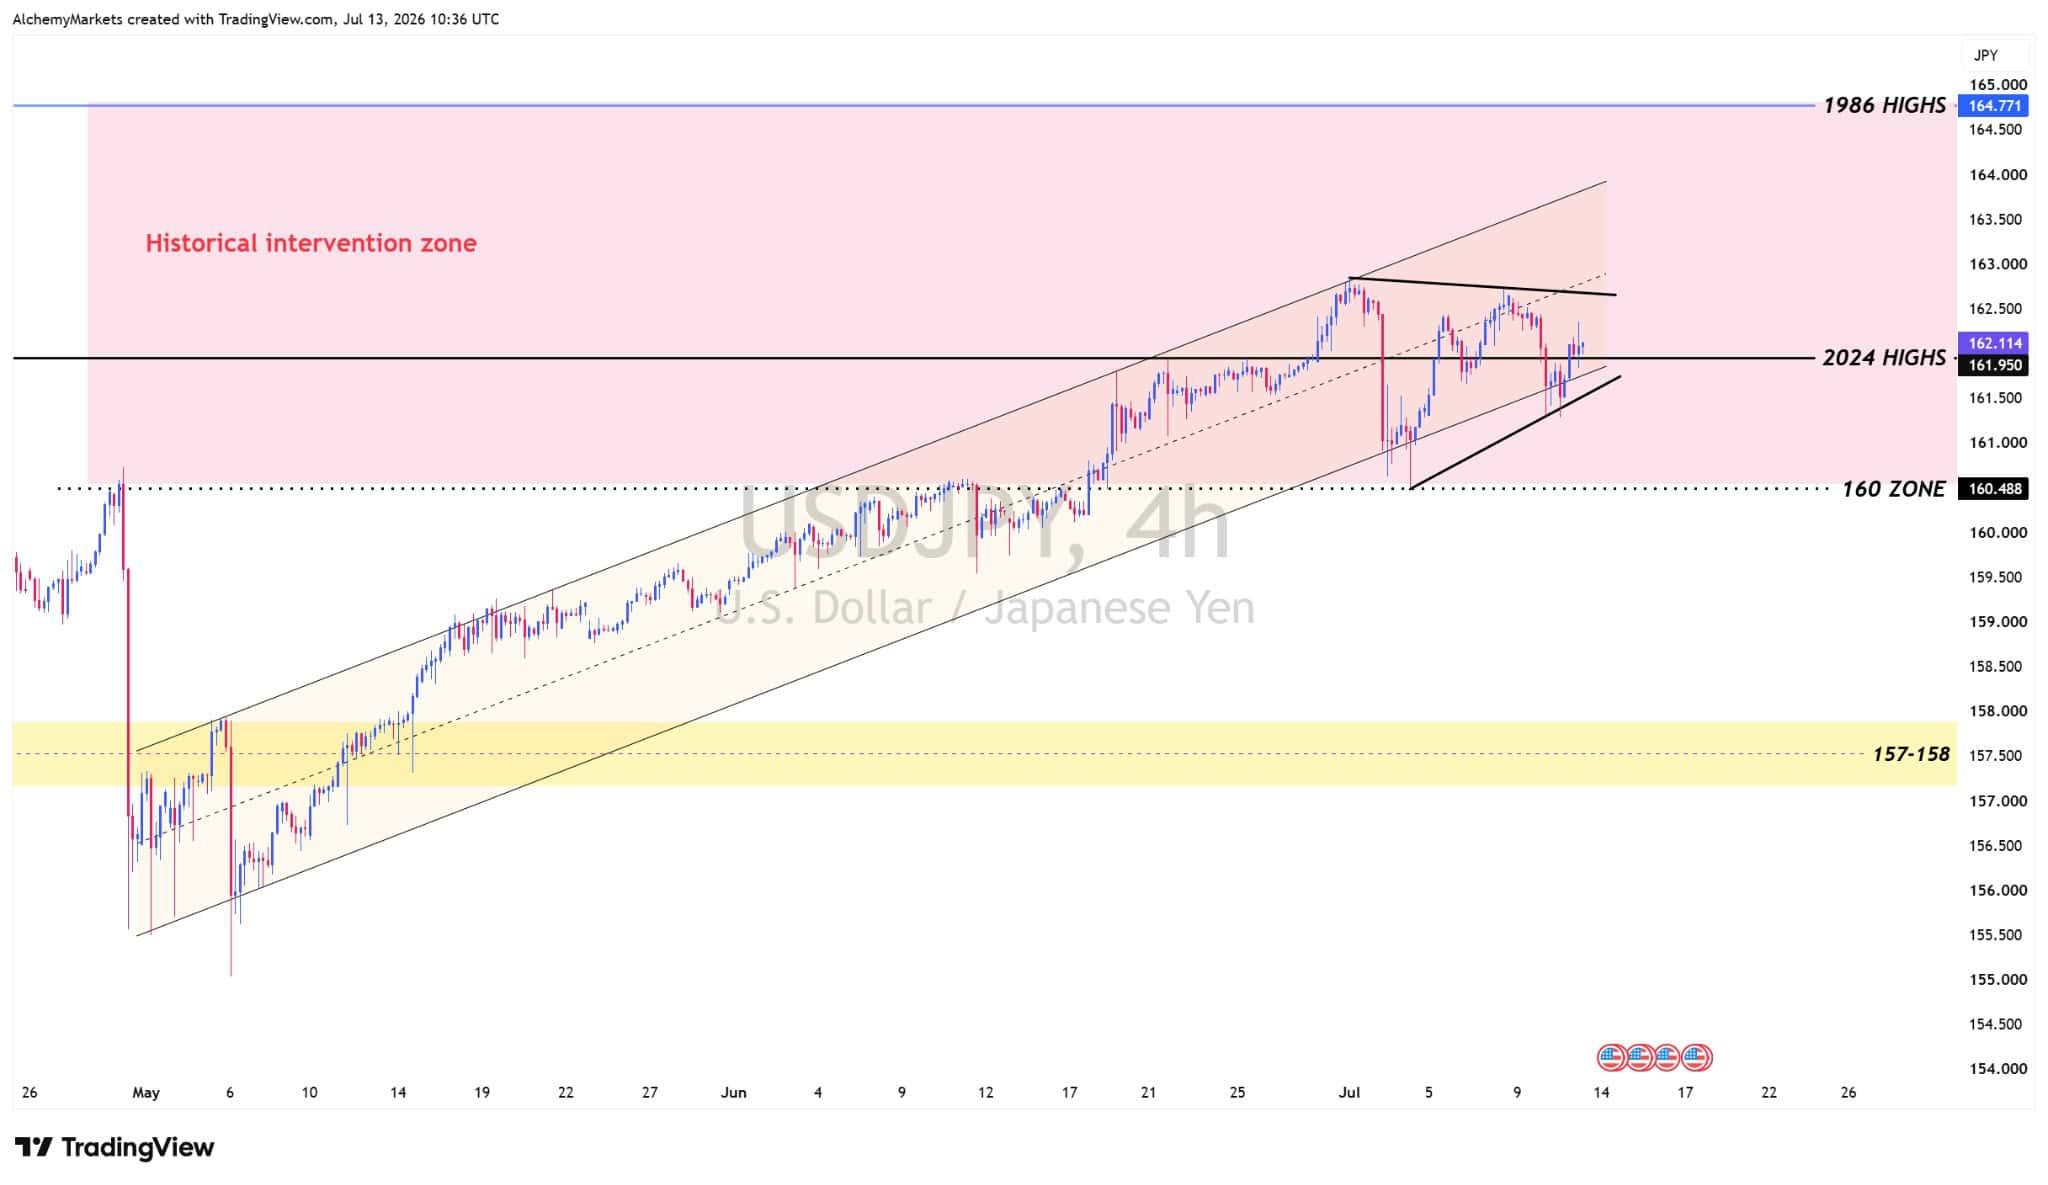
That combination has kept USDJPY close to 162, around the 2024 high at 161.95 and inside a historically sensitive intervention zone. The next major upside reference is the 1986 high near 164.77.
A second yen risk emerged when Japan’s finance minister urged households and pension funds, including the Government Pension Investment Fund, to increase investment in domestic assets. The figure attracting attention is roughly $900 billion, close to the value of GPIF’s foreign holdings.
That does not mean Japan has ordered an immediate $900 billion dump of US stocks and Treasuries. Government sources said there was no immediate plan to overhaul the fund’s strategic allocation, which still targets 25% in each of domestic bonds, foreign bonds, domestic equities and foreign equities.
The market impact is therefore more about repatriation risk than a confirmed liquidation. Even a smaller shift, combined with intervention or falling equities, could force investors to close yen-funded positions, sell foreign assets and buy the yen back.
What matters today
The base case remains managed escalation, firm but volatile oil and an elevated USD/JPY. Another diplomatic patch remains more likely than a lasting closure of Hormuz or an abrupt pension-led liquidation.
The more damaging scenario begins if WTI holds above its reclaimed trend band while USD/JPY fails near recent highs and loses rising support. That would suggest oil inflation pressure and yen carry-unwind risk are beginning to converge.
For the opening bell, oil is the first confirmation and USD/JPY is the second. Until both move together, markets are dealing with two connected risks rather than a full cross-asset stress event.
Author

Zorrays Junaid
Alchemy Markets
Zorrays Junaid has extensive combined experience in the financial markets as a portfolio manager and trading coach. More recently, he is an Analyst with Alchemy Markets, and has contributed to DailyFX and Elliott Wave Forecast in the past.