US Dollar Weekly Forecast: Softer jobs test Fed’s inflation resolve
- The US Dollar closed its second consecutive week of losses.
- The labour market report showed an unexpected drop last month.
- Next of relevance for the Greenback is next week’s CPI data.
The week that was
The geopolitical landscape has remained the almost exclusive driver of the sentiment surrounding the global markets this week.
Against that backdrop, the US Dollar (USD) has been suffering from rising optimism over a potential US-Iran peace agreement that would not only end the current crisis but also reopen the Strait of Hormuz. The likelihood of such a scenario has re-emerged following news that US President Donald Trump called off an imminent attack on Iran over the last weekend, setting free speculations that a deal might be just around the corner… again, and again, and again.
Then, Federal Reserve (Fed) rate hike bets entered the building. Indeed, expectations for extra tightening by the Fed have been receding until they have declined markedly after the US labour market report unexpectedly showed the economy lost 23K jobs last month.
Another driver behind the heightened volatility around the Greenback has come from Japan, after last week’s joint FX intervention to support the Yen left the door open for similar moves in case of further need.
That said, the US Dollar Index (DXY) retreated to as low as the 99.40 region on Friday, or seven-week lows, just to recover some ground afterwards.
Looking at the US money market, the performance of US Treasury yields broadly mirrored that of the buck, drifting lower across the spectrum while tempering at the same time the upside momentum in place since July.
Fed officials retain a clear tightening bias
Fed officials struck a broadly hawkish tone this week, maintaining that inflation remains too high and signalling that interest rates may need to rise again if price pressures persist. While most supported keeping rates unchanged at the latest meeting, none made a convincing case for near-term easing.
Alberto Musalem (St. Louis) and Jeff Schmid (Kansas City) delivered the strongest tightening signals. Musalem revealed that he favoured raising rates at the latest FOMC meeting, arguing that gradual increases would be less disruptive than more abrupt action later. Schmid similarly maintained that current policy was not restrictive enough and that tighter monetary conditions were needed to return inflation to 2%.
Lisa Cook (Board of Governors) and Mary Daly (San Francisco) backed the latest hold but retained a clear tightening bias. Cook warned that the Fed was running out of time for disinflation to resume and stood ready to support another increase. Daly also favoured patience while the Fed gathered more data, but she said policymakers should respond aggressively if inflation accelerated again.
John Williams (New York), Anna Paulson (Philadelphia) and Neel Kashkari (Minneapolis) appeared more comfortable with the current stance. Williams and Paulson supported leaving rates unchanged while assessing whether existing restraint was sufficient. Kashkari prioritised returning inflation to target, but he showed little appetite for a sharp increase in rates.
Overall, the message was one of patience with a hawkish skew. Rate setters generally favoured holding rates steady while monitoring incoming data, but persistent inflation, resilient economic activity and limited labour-market weakness left the door open to further tightening. The week’s remarks offered little support for rate-cut expectations and suggested that the policy debate has shifted towards whether another increase will be required.
Bullish positioning continues to build; conviction remains measured
Speculative sentiment on the US Dollar improved further in the week ending July 28, with data from the Commodity Futures Trading Commission (CFTC) showing net long positions jumped to almost 17.2K contracts from 15.6K previously. The weekly increase slowed to 1.6K contracts, but the figures suggest a continued but more measured rebuilding of bullish exposure.
The latest increase was accompanied by stronger market participation after open interest climbed to around 58.3K contracts (from nearly 54.0K), while Speculative Exposure edged up to 29.5%. The increase in open interest along with the rise in net longs indicates investors continue to add new longs, not just close out shorts.
The bigger picture is also constructive, as the 4-week change in net positioning has moved up to around 4.2K contracts, suggesting bullish positioning has been building over the past month. Even so, historical measures suggest the Greenback remains far from crowded: the Net Position Percentile rose to 64.3, while the Speculative Exposure Percentile edged up to 47.5, highlighting that speculative exposure remains broadly around its 5-year average despite the recent accumulation.
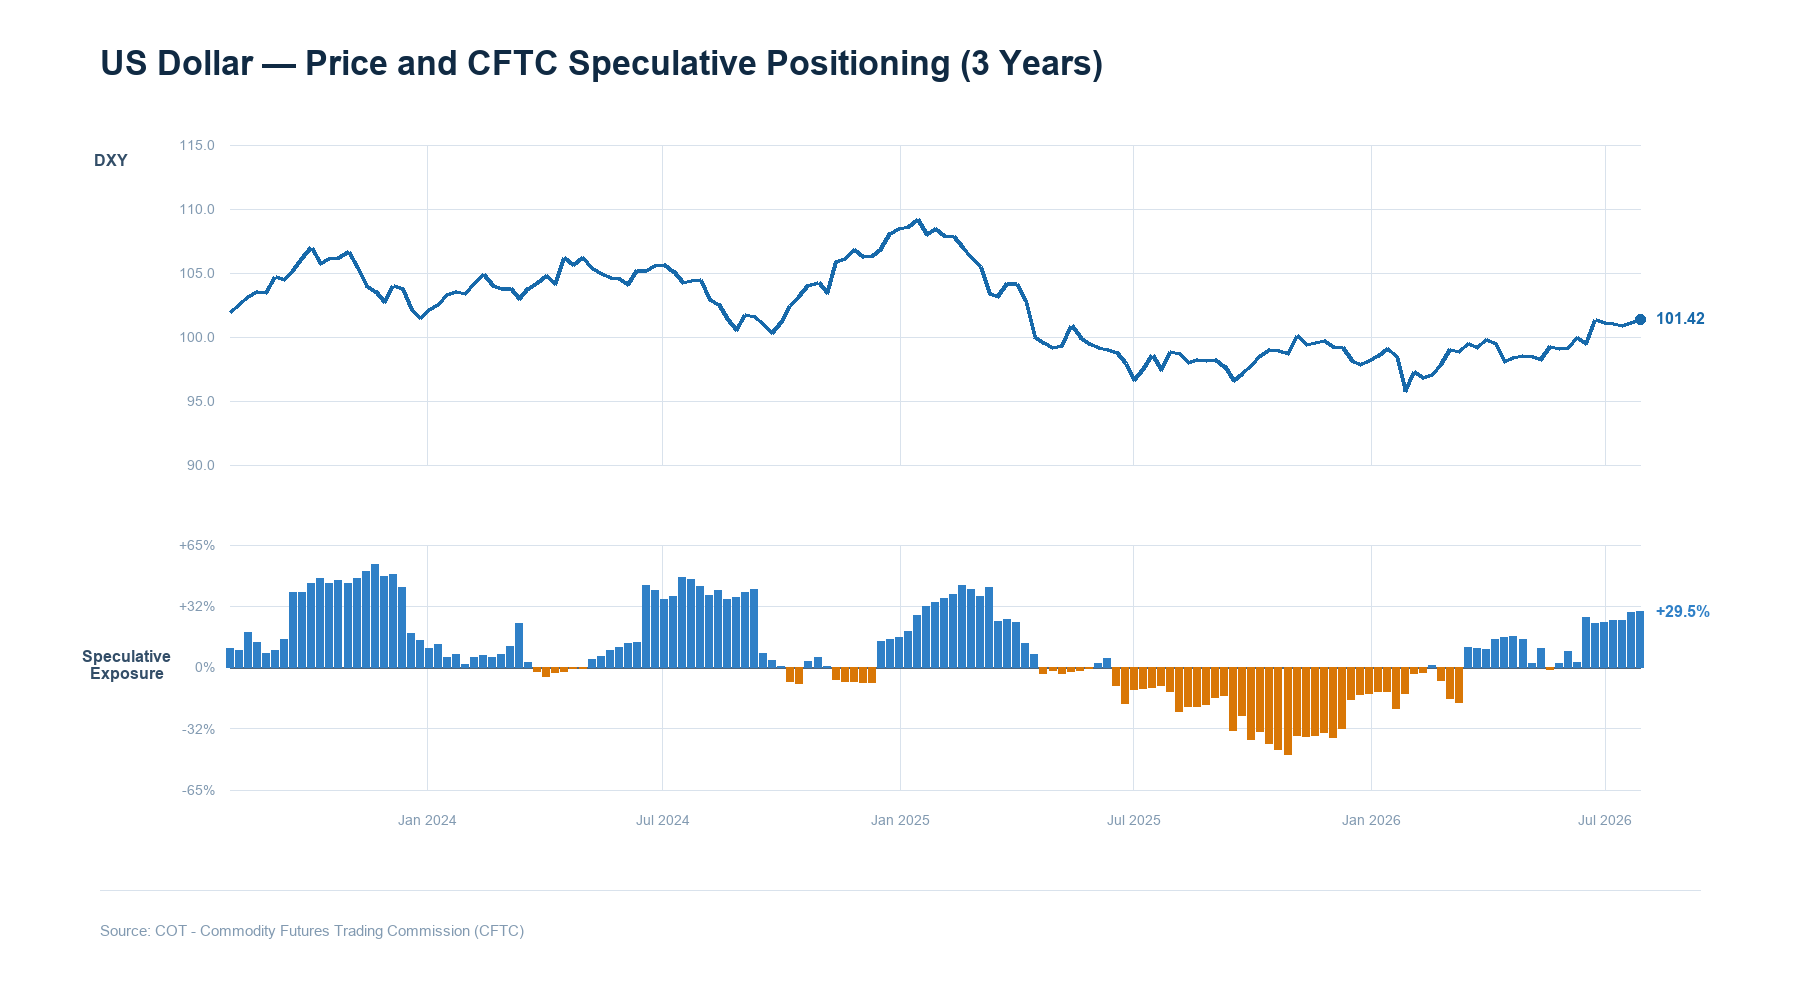
To sum up, the latest CFTC data suggest confidence in the US Dollar continues to improve. While the pace of weekly buying has moderated, the combination of rising open interest, positive 4-week momentum and still-neutral historical positioning indicates there remains scope for further accumulation should US economic data and Fed expectations continue to support the buck.
Sticky inflation meets a cooling labour market
The US Dollar remains baffled by conflicting economic signals.
On the one hand, inflation remains stubborn. Both the Consumer Price Index (CPI) and the Personal Consumption Expenditures (PCE) Price Index showed some cooling in June, but underlying price pressures remained persistent, giving the Federal Reserve (Fed) another reason to keep policy restrictive for longer.
On the other hand, the Greenback has come under renewed pressure following a disappointing July Nonfarm Payrolls (NFP) report. The US economy shed 23K jobs, while June’s increase was revised sharply lower to 20K from 57K. The Unemployment Rate offered a silver lining, easing to 4.1%, although the decline once again appeared partly driven by a drop in labour-force participation (61.4% vs 61.5%).
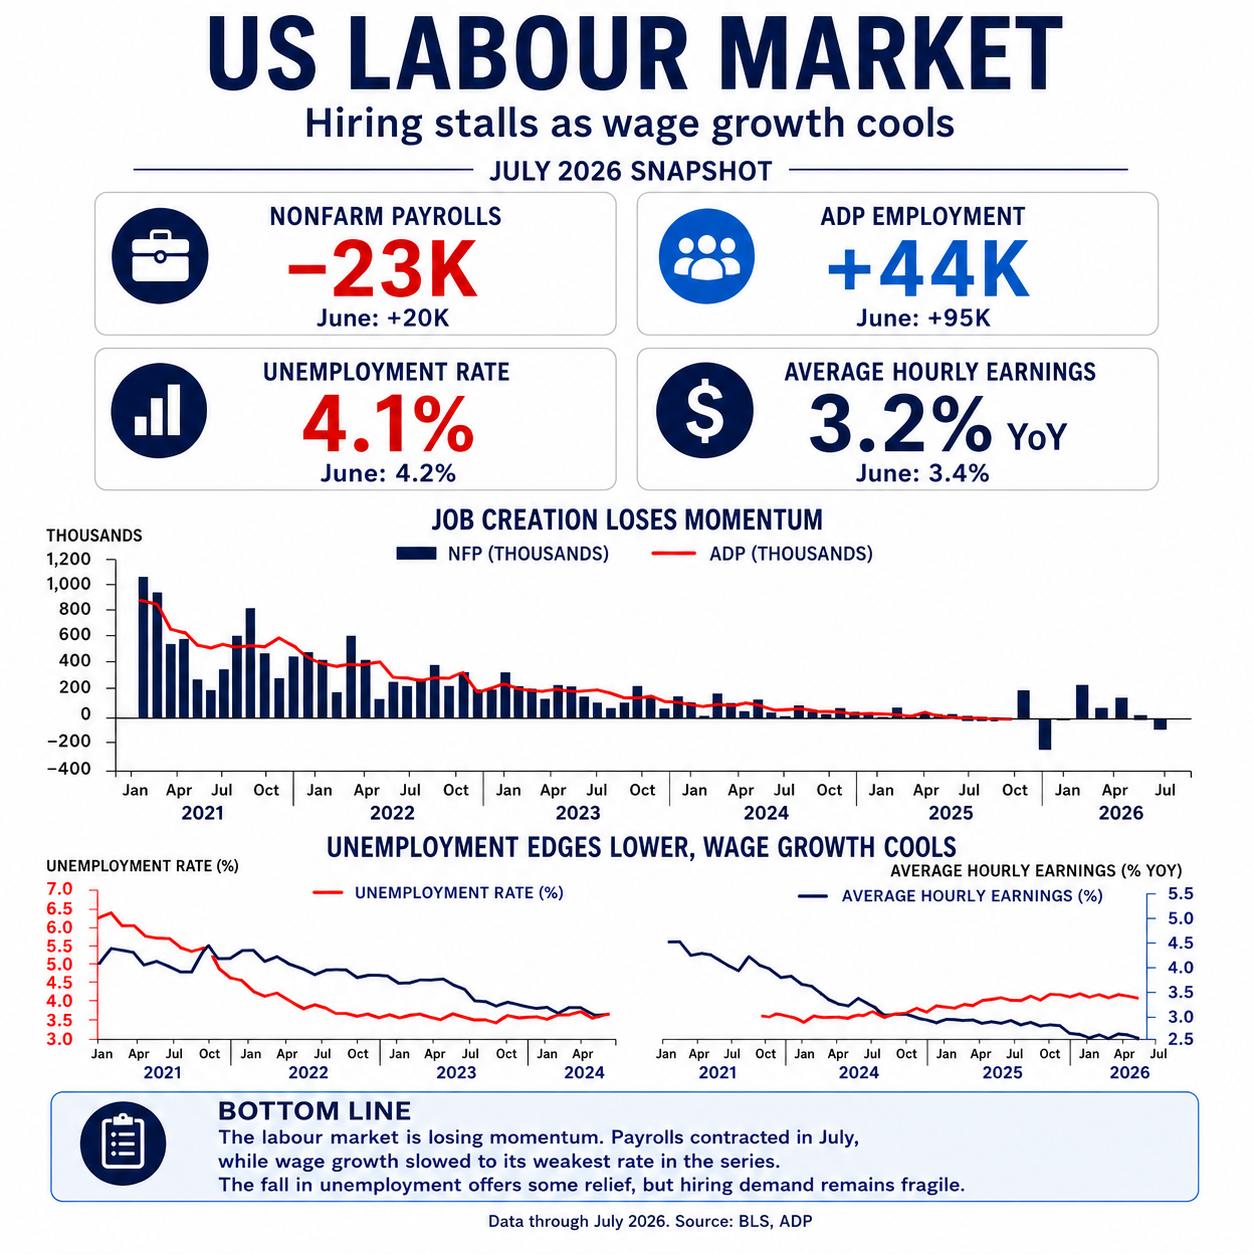
Despite mounting evidence that the labour market is losing momentum, Fed Chair Kevin Warsh has shown little appetite for shifting the focus away from inflation. That has left investors questioning whether the recent weakness in employment will be enough to change the central bank’s policy stance.
The broader market mood remains cautious as well, with investors trying to assess the uncertain outlook for the Middle East and the White House’s still-unsettled approach to resolving the conflict with Iran.
Inflation takes centre stage
Next week, attention on the US economic calendar will centre almost exclusively on Wednesday’s Consumer Price Index (CPI) report. The inflation figures could provide the next major catalyst for the US Dollar and shape expectations for the Fed’s next policy moves. In addition, another revision of US Q2 GDP is due ahead of the flash U-Michigan Consumer Sentiment gauge for the month of August.
Meanwhile, Fed officials are likely to keep their remarks focused on domestic inflation and the evolving geopolitical landscape.
The last mile of disinflation could underpin the Dollar
Recent months have highlighted a familiar challenge: bringing inflation down from its peak is one thing, but returning it all the way to target is proving far more difficult.
That final stretch of the disinflation process could become an important source of support for the US Dollar in the months ahead, particularly if markets have been too optimistic about how quickly the remaining price pressures will fade.
As long as underlying inflation remains persistent, expectations that interest rates will stay higher for longer should continue to provide a firm footing for the Greenback.
Inflation FAQs
Inflation measures the rise in the price of a representative basket of goods and services. Headline inflation is usually expressed as a percentage change on a month-on-month (MoM) and year-on-year (YoY) basis. Core inflation excludes more volatile elements such as food and fuel which can fluctuate because of geopolitical and seasonal factors. Core inflation is the figure economists focus on and is the level targeted by central banks, which are mandated to keep inflation at a manageable level, usually around 2%.
The Consumer Price Index (CPI) measures the change in prices of a basket of goods and services over a period of time. It is usually expressed as a percentage change on a month-on-month (MoM) and year-on-year (YoY) basis. Core CPI is the figure targeted by central banks as it excludes volatile food and fuel inputs. When Core CPI rises above 2% it usually results in higher interest rates and vice versa when it falls below 2%. Since higher interest rates are positive for a currency, higher inflation usually results in a stronger currency. The opposite is true when inflation falls.
Although it may seem counter-intuitive, high inflation in a country pushes up the value of its currency and vice versa for lower inflation. This is because the central bank will normally raise interest rates to combat the higher inflation, which attract more global capital inflows from investors looking for a lucrative place to park their money.
Formerly, Gold was the asset investors turned to in times of high inflation because it preserved its value, and whilst investors will often still buy Gold for its safe-haven properties in times of extreme market turmoil, this is not the case most of the time. This is because when inflation is high, central banks will put up interest rates to combat it. Higher interest rates are negative for Gold because they increase the opportunity-cost of holding Gold vis-a-vis an interest-bearing asset or placing the money in a cash deposit account. On the flipside, lower inflation tends to be positive for Gold as it brings interest rates down, making the bright metal a more viable investment alternative.
Author

Pablo Piovano
FXStreet
Born and bred in Argentina, Pablo has been carrying on with his passion for FX markets and trading since his first college years.















