Too good to cheer
Unexpectedly strong PMI data from Europe and the US rattled markets yesterday.
In the US, flash PMI figures for September showed activity expanding at the fastest pace in more than five years. New orders grew at the fastest pace since April 2022, while manufacturing hiring was the strongest since February 2021. Massive AI investment and resilient consumer spending outweighed energy-price-led worries, though supplier delivery times stretched, according to the same data, while input costs remained elevated due to high energy prices and supply-chain pressures.
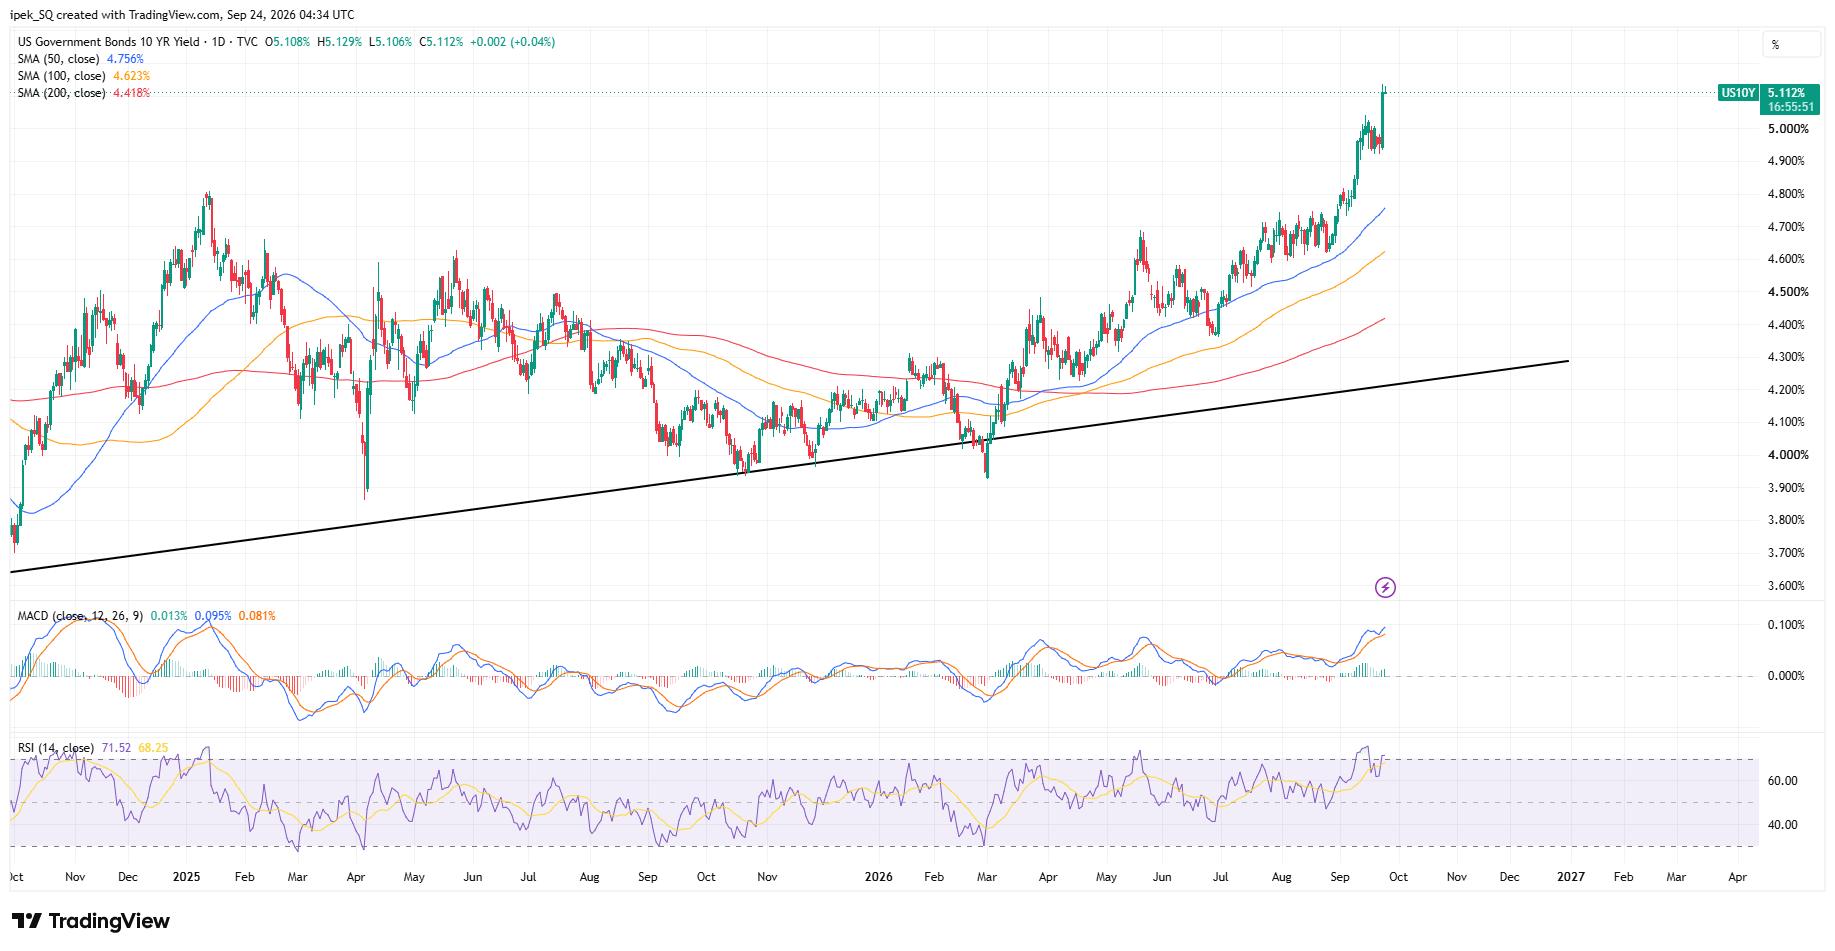
In other words, economic activity expanded strongly while price pressures remained elevated. That’s the perfect combination for fuelling further rate-hike expectations. The US 2-year yield – which best captures Federal Reserve (Fed) rate expectations – spiked past 4.94%, the highest since June 2024; the 5-year spiked past 5% for the first time since 2007, also hammered by a weak 5-year bond auction; the 10-year yield spiked past 5.10%; and the 30-year yield returned above 5.40%. The bond selloff spilled over to Japanese bonds. The Japanese 10-year JGB returned from holiday with a jump above 3%. Equities are hammered, of course, with the US Nasdaq 100 taking the biggest hit after hitting a record high the day before.
Read the full article here.
Author

Ipek Ozkardeskaya
ipekScope
Ipek Ozkardeskaya began her financial career in 2010 in the structured products desk of the Swiss Banque Cantonale Vaudoise. She worked in HSBC Private Bank in Geneva in relation to high and ultra-high-net-worth clients.