The week ahead: Key test for Warsh, but can a rate hike combat the energy price spike?
- Stocks sink to start the week.
- Oil price surge adds to market challenges.
- Kevin Warsh expected to hike, as markets figure out their own forward guidance.
- AI warnings weigh on tech trade.
- Is this the end of hyperscaling?
- Can Treasuries benefit?
- The benefits of a slower pace of AI development.
- A rotation in the AI trade.
- Oil price pressures heat up.
- Why central bankers are more interested in fuel prices.
- What to watch in the year ahead.
At the start of a new week, there are some key tests for a market that is facing mounting challenges. Can calls to slow down the pace of AI actually dent the tech trade? Rising energy prices have knocked global sentiment, however, tech stocks have been one of the more resilient sectors as inflation and interest rate concerns started to bite and hit the bond market. Strong tech earnings have protected this sector, but can they fight the challenge from within now that Dario Amodei, Sam Altman and Elon Musk are urging the pace of AI development to slow?
Stocks sink to start the week
At the start of trading on Monday, stock futures are falling, the S&P 500 Is down 0.5%, and Nasdaq futures are tumbling more than 1%, as chip stocks sell off sharply. Nvidia is down 1%, but SanDisk is trading lower by 4% in the pre-market, Micron is down 3.5% and AMD is lower by 3%. In Korea, the Kospi is down more than 2.5%, and SK Hynix, a major semiconductor maker, is lower by more than 5%. It could be a rough day for the tech sector, and stocks with little exposure to AI could be better protected on Monday. European futures are pointing to a slight decline at the open, although the low-tech FTSE 100 is managing to eke out a gain in the futures market.
Oil price surge adds to market challenges
The oil price has also jumped at the start of the week, Brent crude is higher by 2.5% and is above $107 per barrel in early trading. This is an elevated level, however, the oil price is still below the $114 highs from May.
A shake up of the AI trade combined with soaring oil prices are a challenging backdrop to the main event this week: the Federal Reserve’s interest rate decision. After last week’s hot inflation report and surging energy prices, especially fuel prices, the market is now pricing in a 86% chance of a 25bp hike, the first time the Fed will have hiked rates for 3 years.
Kevin Warsh expected to hike, as markets figure out their own forward guidance
While the new Governor, Kevin Warsh, has been at pains to state that he does not provide forward guidance, the market seems certain that a hike is on the cards. If the Fed fails to raise rates on Wednesday, they will have a lot of explaining to do.
AI warnings weigh on tech trade
Aside from the Fed, the other main topic at the start of this week will be the tech trade, in particular, the AI trade, after the CEOs of Anthropic, OpenAI and Tesla/ SpaceX all called for the pace of AI development to slow. This is a highly unusual unified message from a group of tech CEOs, and it is weighing on the AI trade this morning.
Is this warning about AI a sign that hyper scaling AI compute and infrastructure has reached its end point? If so, this will have massive repercussions for financial markets, and it could also lead to a sharp sell off in chip stocks and other components of the AI trade at the start of the new trading week.
It is worth remembering that over 50% of the S&P 500’s sectors are AI-linked, and the top hyperscalers make up a third of the weighting of the main US blue chip index. Any change in the AI trade will have big ramifications for US indices.
Is this the end of hyperscaling?
If we take a step back, the end of the hyperscaling narrative had to happen at some point. The big four hyperscalers, which include Amazon, Microsoft, Meta and Alphabet, have spent roughly $900bn in the last 2 years on Capex for AI.
These numbers are huge, and frankly ridiculous. Every quarter the number got bigger, and the market kept going up. To highlight the extent of the growth, in 2023, the big four hyperscalers spent a combined $155bn on Capex, which highlights the steep increase in the Capex binge.
Some analysts are wondering if this ‘warning’ about AI is actually a convenient excuse for them to scale back their spending, which was always likely to happen. If the warning from these AI CEOs is a convenient off ramp for them to bring spending back into historical norms, then what will it do to financial markets?
The most obvious move would be a reduction in hyperscaler debt issuance. This has surged in the last 12 months to $300bn across Amazon, Meta, Alphabet and Oracle. There is also a growing off-balance sheet layer of financing of approximately $65bn, which doesn’t show up in headline bond issuance.
Can Treasuries benefit?
If there are fewer hyperscalers issuing debt, then this could mean that there are more buyers for US Treasuries and other sovereign debt. Global sovereign bonds sold off sharply last week, US 10-year yields jumped 18bps, and 2-year yields rose by 25bps, there were larger gains fro UK Gilt yields as borrowing costs jumped. On the back of this news, we could see perceived demand for Treasuries and other sovereign bonds rise, at the same time as chip stocks sell off, and the bond market is worth watching on Monday.
While the irrationality of the pace of Capex spending may slow down on the back of this warning, we think that the impact on the AI trade could be short term. Corporate spending remains strong, and AI developments are at a relatively early stage, with plenty to go. There are also many thousands of AI projects that are currently ongoing, so demand could remain strong for the foreseeable. Even so, a more cautious approach to AI development could lead analysts to trim their earnings forecasts, which could weigh on stocks with elevated valuations.
The benefits of a slower pace of AI development
Overall, we think that a slower pace of AI investment is no bad thing. Firstly, it could increase free cash flow and take up less space on the balance sheet if Capex slows down in the coming years. Also, it could allow companies like Amazon, Meta, Microsoft and Alphabet to spend more time on extracting returns from Capex that has already been spent, which may boost productivity and the attractiveness of these stocks.
Expect a rotation in the AI trade
As we move through the year, the focus could shift from capex spend to the monetisation of AI, which is seen as the holy grail. It could also lead to a rotation in tech spend, now that the focus is on a push for safe guards. For example, this could lead to less money spent on chips and memory, and more spent on cyber security and AI monitoring tools. This could benefit other AI-linked stocks like Palo Alto Networks, CrowdStrike Holdings, Fortinet, CyberArk, Check Point Software and Gen Digital. Microsoft and Broadcom also have significant cyber security businesses, although they play into the diversified tech giant basket.
Chart 1: Palo Alto Networks
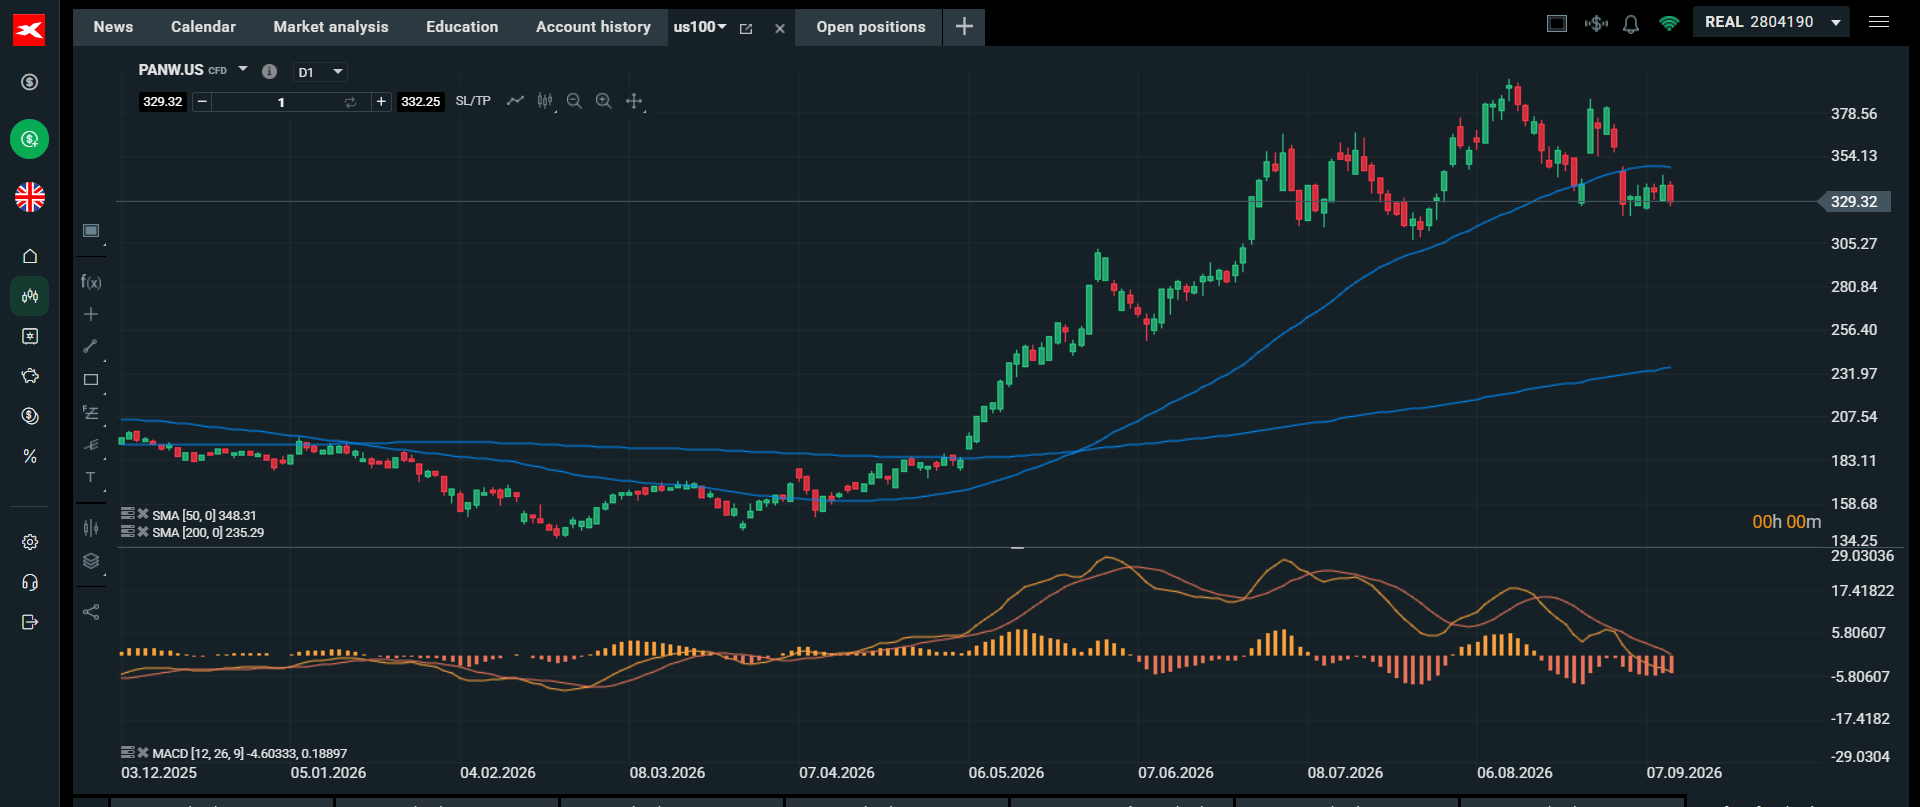
When the narrative changes, traders have to react. Although chip stocks may tumble at the start of this week, the tech trade remains compelling.
Oil price pressures heat up
Elsewhere, energy is going to remain in focus this week, after more ships were attacked in the Strait of Hormuz on Sunday. Drone attacks on a key Saudi Arabian East-to-West pipeline forced its closure on Friday, which could impact 4-5% of the world’s oil supply.
There are genuine fears that Saudi could run out of oil storage at one of its biggest ports in the next week, which could mean that it will have no choice but to halt oil exports. If this happens, and it looks likely that it will, then it could worsen the supply crunch which has pushed some fuel prices to record highs and sent bond yields to multi-decade highs in the past few weeks.
The economic damage caused by surging energy prices is starting to add up. There are growing attacks in the Middle East and no sign of a diplomatic solution appeared during the weekend. Middle East oil supplies are threatened, China is buying up more oil, Ukrainian strikes on Russian refiners have slowed a big source of global diesel, and the Northern hemisphere moving into winter could make for a very tough few months.
Why central bankers are more interested in fuel prices
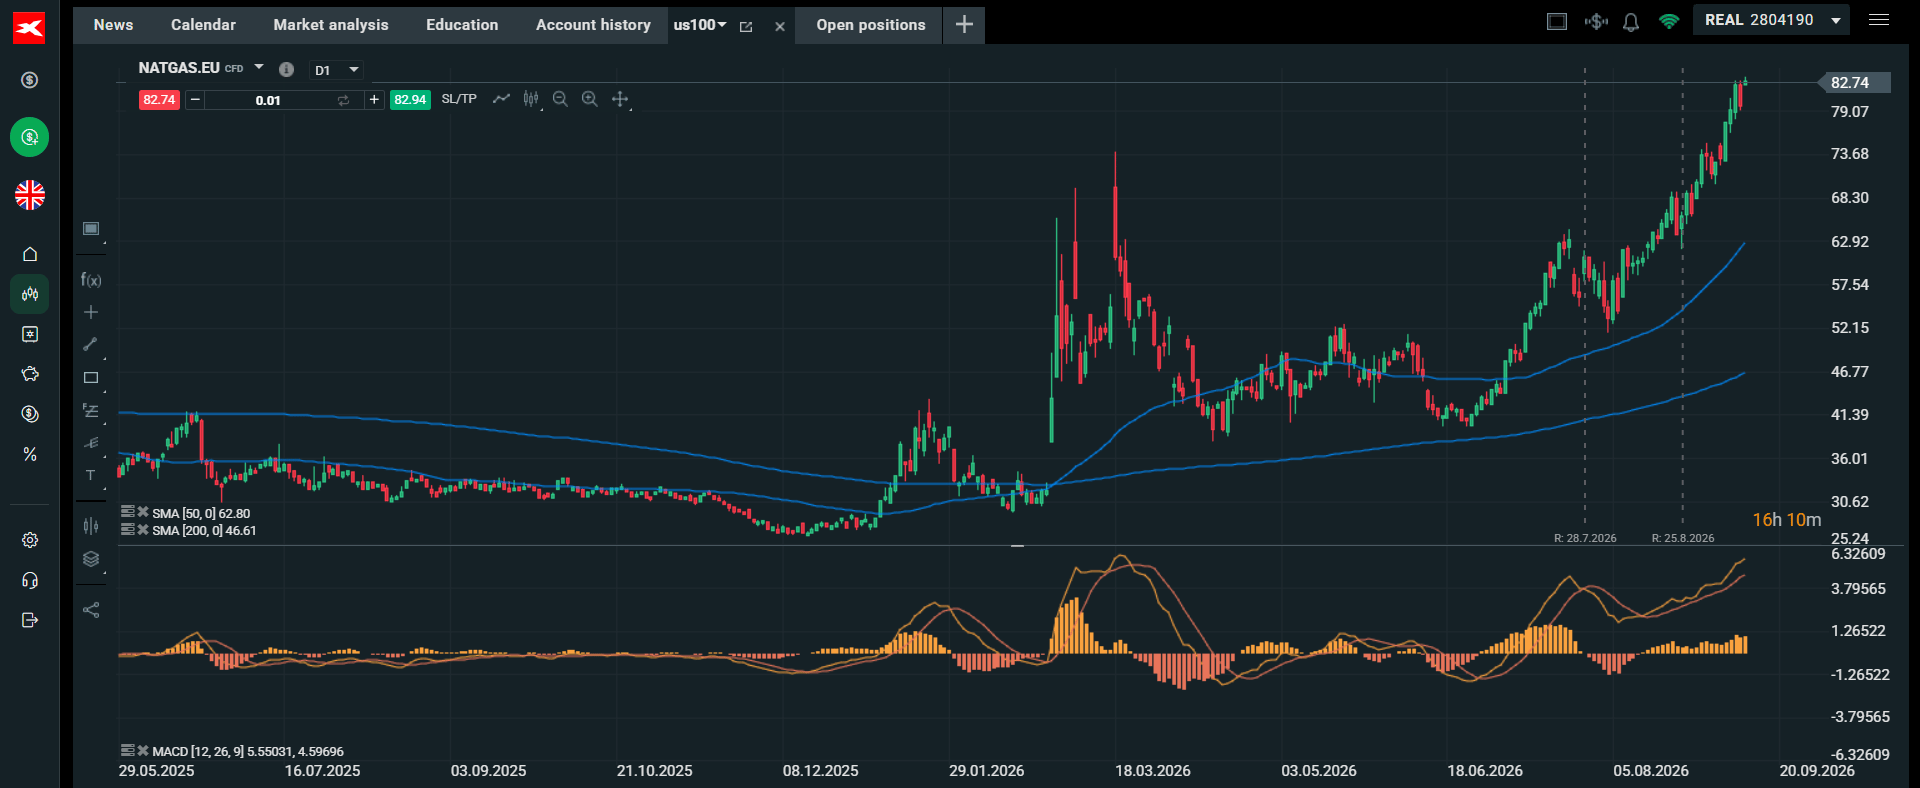
While financial markets tend to focus on the oil price, this is not the main driver of global inflation. The price of diesel and natural gas in Europe are climbing at faster rates than the oil price, for example, Brent crude futures climbed 13% last week, and Brent is above $107 per barrel, this is the highest level since May. In contrast, the price of European Natural Gas is at its highest level since 2023.
Gas stocks are low in Europe, winter is coming and supply is contained. Diesel prices in the US are now at a record, and unleaded petrol in the UK hit a 4-year high last week. The prices of these fuels are surging relative to the oil price, and they are likely to rise further until we get an end to one of the supply constraints mentioned above. The US and Iran look like they are bedding down for a prolonged conflict, which could push up prices further and have a major impact on the global economy.
When energy prices become a political problem
As we move towards Q4, there will be growing pressures for governments to help provide assistance for households during this rough patch. However, that will be tricky for fiscally constrained countries that have seen their borrowing costs surge in recent weeks, which includes the UK, the US and most of Europe.
Although stocks have had a rough time in recent days, the Nasdaq is still only 4% away from its record high set in June, and the S&P 500 is less than 2% away from its all time high. However, the surge in fuel prices, and the threats to economic growth could see investors grow nervous, after US and most global stocks posted another loss for last week.
What to watch this week
1. A big test for Kevin Warsh
The backdrop for this week may be dominated by the AI trade and commodity prices, but the main event is the Fed meeting on Wednesday. This is the most highly anticipated meeting of Warsh’s tenure so far, and the market is fairly certain the Fed will hike rates, there is currently an 86% probability priced in by the Fed Fund Futures market.
Wednesday’s expected decision will set the tone for the rest of the week and the month, in our view. The last time Warsh spoke after a Fed rate meeting, Treasury yields spiked and he spooked financial markets. Investors and traders are having trouble getting used to Warsh’s stance on forward guidance. He says that he doesn’t like forward guidance, yet at every opportunity he speaks out about inflation. Is it any wonder that the market is rushing to price in a rate hike when the Fed’s preferred measure of inflation, the core PCE, has been well above the 2% target every month this year?
This is a big test for Warsh. A rate hike from the Fed could put some of the inflation concerns to one side, and help long-end bond yields to recover, as it would show the market that the Fed is serious about inflation. A failure to hike could lead to another bond market sell off, as investors fret that the Fed is not in control of inflation.
One thing is almost certain, if Warsh and co do hike rates, President Trump could go ballistic. Trump is correct in one way, a rate hike is not a magic wand and it cannot control an international energy price spike, added to this it can be a sickly cure for an economy. However, cutting rates now, as Trump has demanded, would be economically unfeasible and a terrible idea.
Due to this, this week’s decision is also a test of the Fed’s independence, as well as its inflation-fighting credibility.
2. Will the Bank of England follow suit?
We do not think so, for several reasons, firstly the UK economy is not yet as strong as the US, although the pace of growth surprised on the upside for July. Added to this, while the surge in natural gas prices, and the lack of natural gas storage in the UK, which makes us vulnerable to the spot price, are a headache for the BOE, there is no sign yet that price pressures are broadening out beyond energy. Private sector wage growth is likely to remain negative in real terms if the inflation stays elevated.
The hawks at the BOE may want an insurance rate hike before inflation surges, however, we think the medicine is too costly for the UK economy at this juncture. The BOE could vote to keep rates steady at 3.75% by a 6-3 margin. This is a divided bank, but it would suggest that the hawks are not in control of the BOE yet.
Andrew Bailey has also said that they are focused on the length of time that energy prices remain elevated, which is why it makes sense for the BOE to remain on hold at this meeting, and potentially hike in November, after the Budget. Although it is not a ‘no brainer’ that the BOE hikes on Thursday, if they do surprise the market, the pound could surge, although bond yields at the long end of the Gilt curve could fall.
Chart 1: Brent Crude Oil
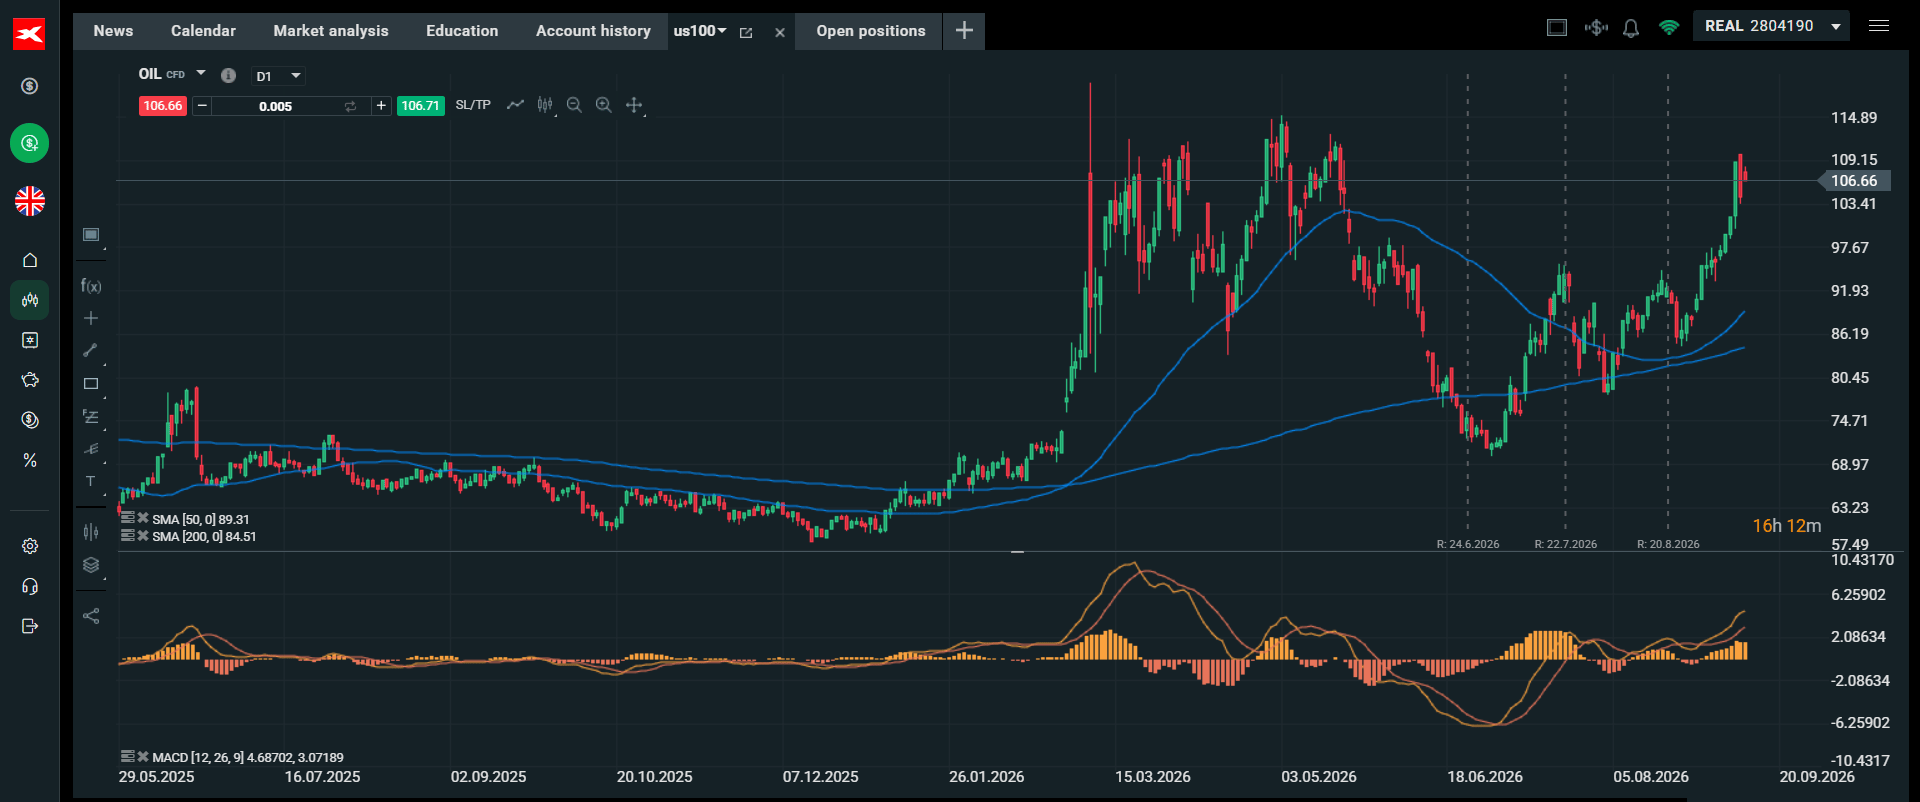
Chart 2: European Natural Gas: Fuel prices are outpacing gains in the Oil price
Author

Kathleen Brooks
XTB UK
Kathleen has nearly 15 years’ experience working with some of the leading retail trading and investment companies in the City of London.

















