Tesla a particular benefactor amid Trump’s manufacturing focus
-
European markets jump after Trump full sweep.
-
Tesla a particular benefactor amid Trump’s manufacturing focus.
-
Qualcomm earnings in view given reliance on Asian manufacturing.
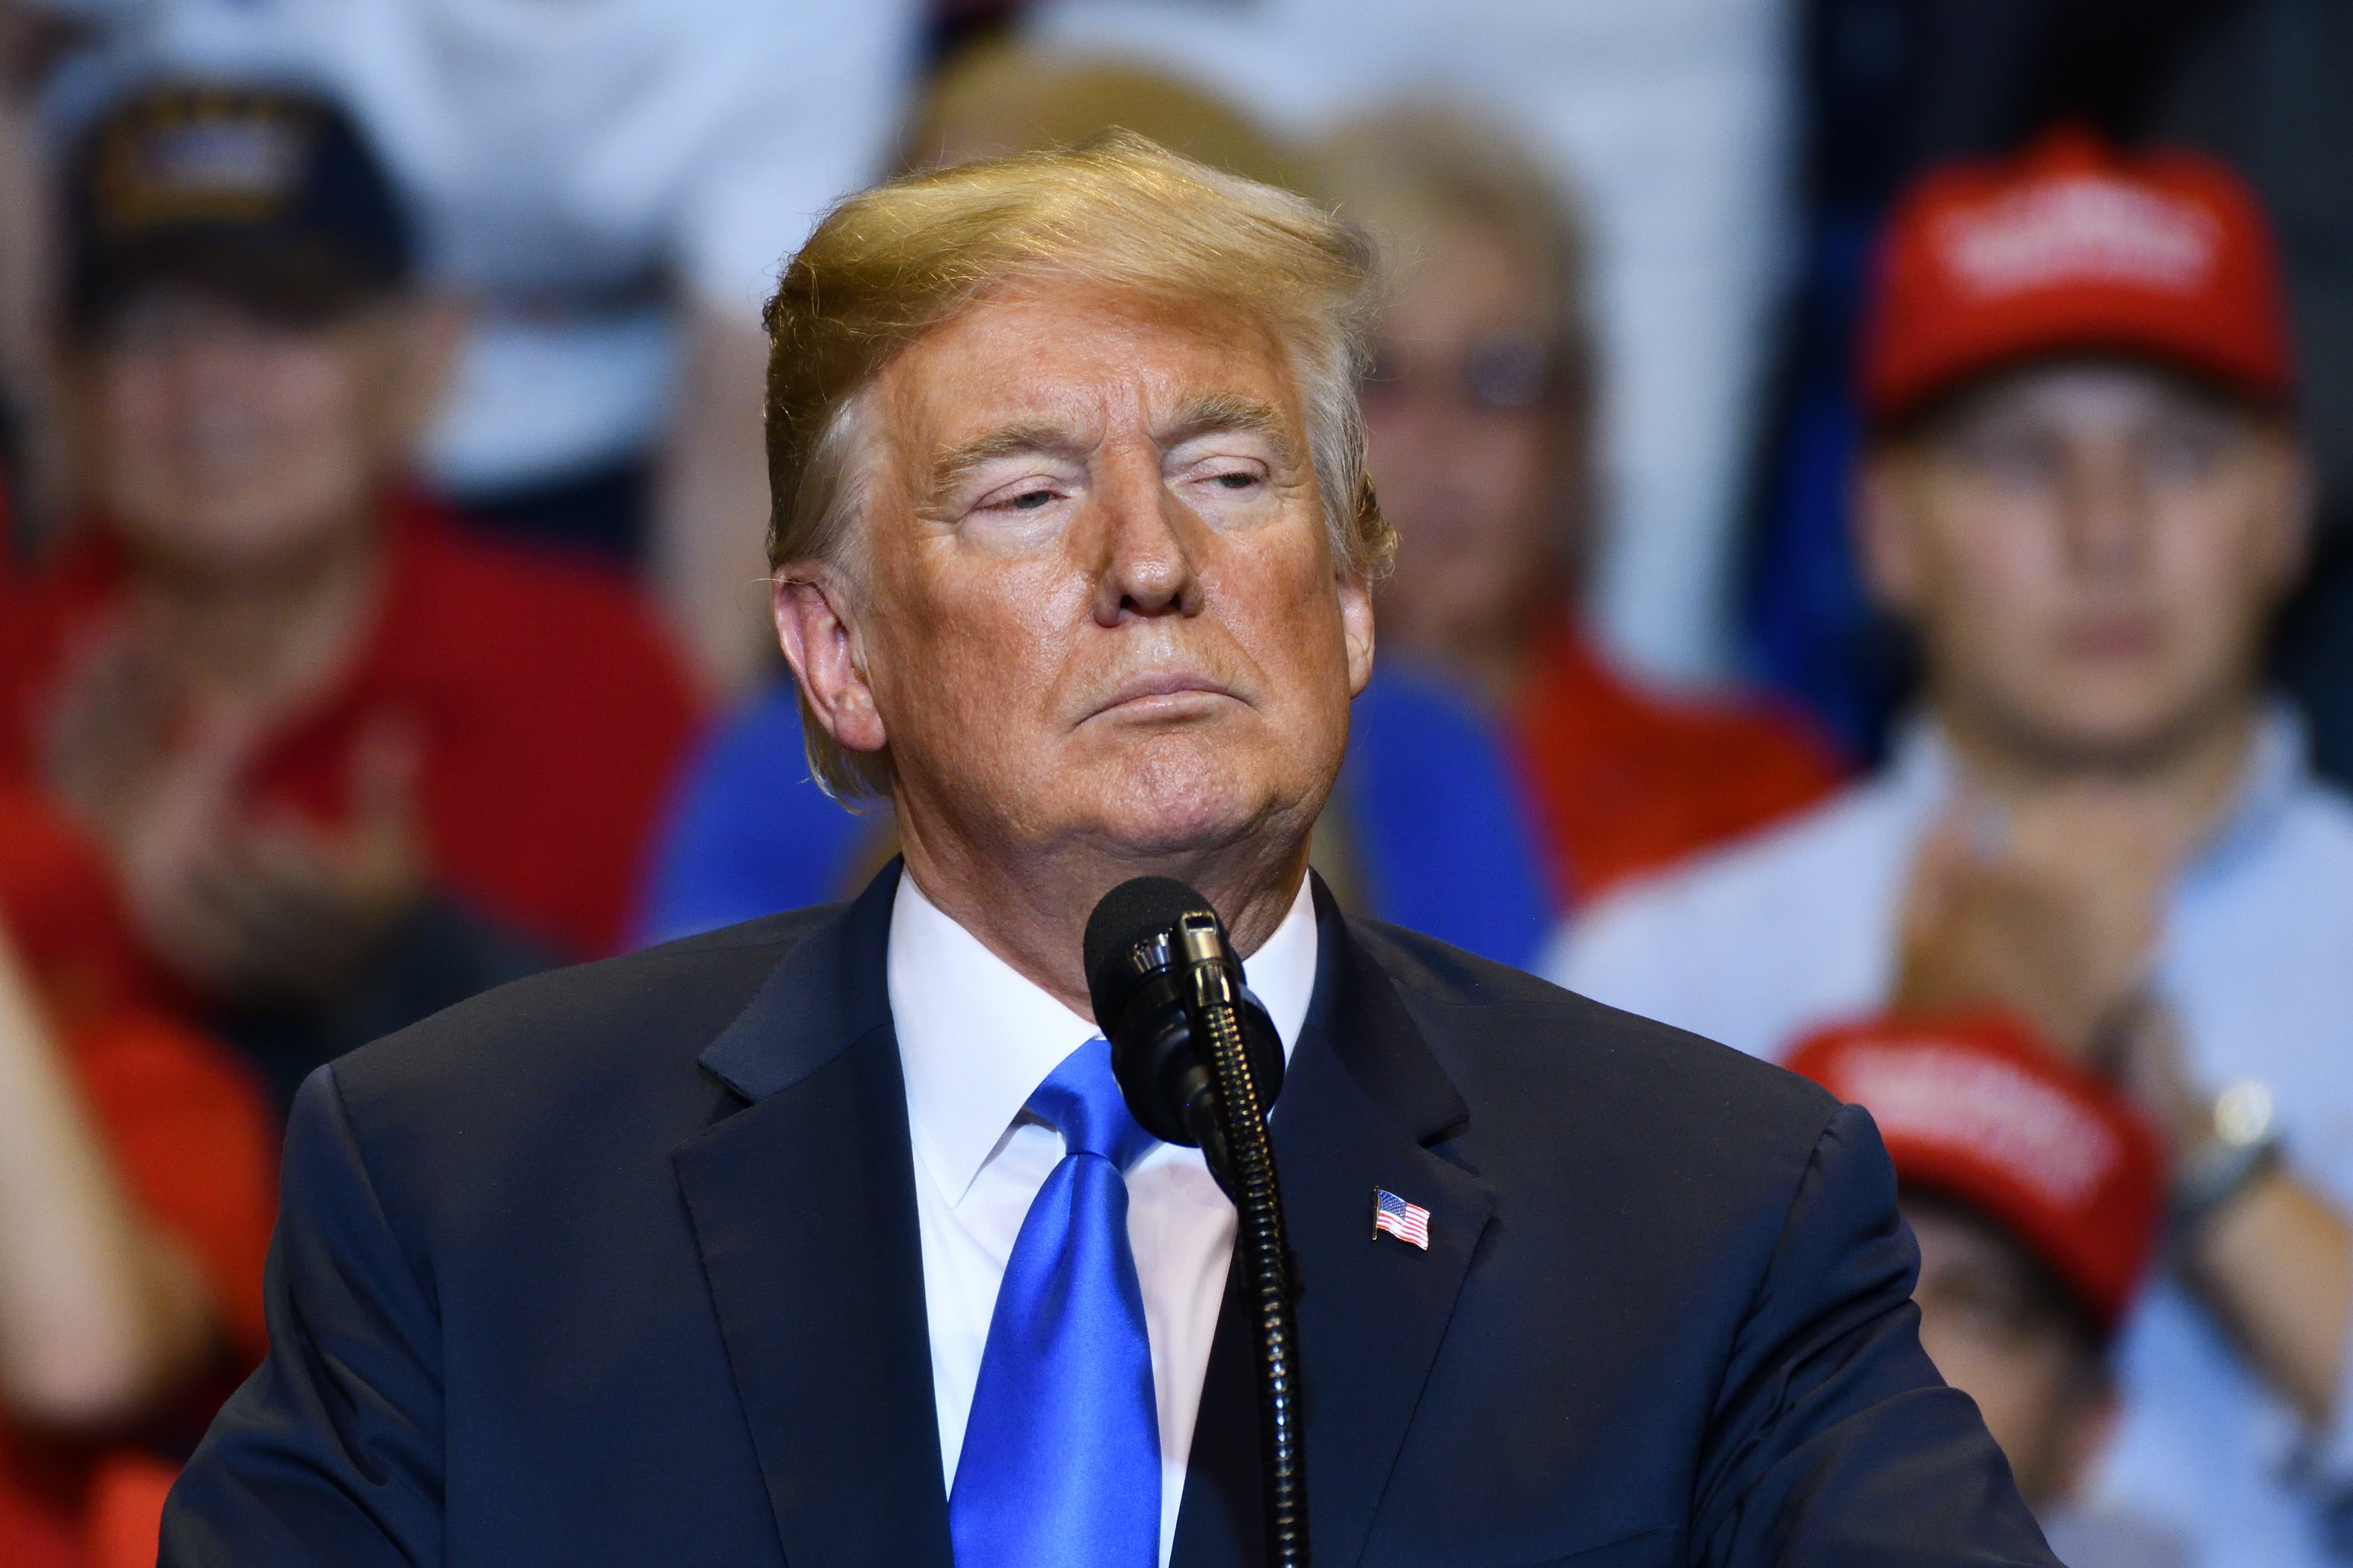
European markets are in a buoyant mood following a US election that saw Donald Trump sweep to power, casting aside any of the polling doubts that had recently emerged. Despite concerns around the potential implications for trade between the countries, we have seen widespread optimism that Trump’s pro-business stance will lift all boats. However, the one standout loser in all of this comes from the China region, with the Hang Seng falling over 2% as traders reacted to the increased chance that we will see a raft of protectionist tariffs imposed on exports into the US. One of the biggest winners from Trumps first stint as President was the financial sector, and it is the UK-listed banks which have been a standout performer in early trade. With tariffs on goods unlikely to hurt UK banks, the prospect of strong economic growth and higher interest rates bring a goldilocks scenario for the financials.
With Trump looking to have taken a full sweep of both the House and Senate, markets are faced with the prospect of an unrestricted period of leadership that many had penciled in as the best-case scenario for equities. In particular, the focus on traditional industries such as US manufacturing and energy provide the basis for a redistribution of US economic strength after a period where tech has been the only show in town. Tesla straddles the two perfectly, with Elon Musk’s position within Trump’s administration only serving to further enhance optimism for a company that benefits from being both a growth/tech stock and US-based manufacturer. With China EV imports likely to suffer from huge tariffs, Tesla shareholders are in confident mood as we look ahead to a predicted 13% pop at the open.
The strength of the US dollar and rising treasury yields highlight the mix of a less dovish pathway for US rates and increased borrowing that will come under Trump. With the Federal Reserve expected to announce a likely 25 basis point cut tomorrow, we are already seeing expectations reigned in for the December meeting given the perception that Trump’s policies are inherently inflationary. Looking ahead, earnings from Arm Holdings and Qualcomm provide the first releases in the wake of the election result. With Trump pushing for manufacturers to relocate production facilities into the US, Qualcomm commentary will be particularly interesting given the fact that many of their Chips are imported from Taiwan and China.
Author

Joshua Mahony MSTA
Scope Markets
Joshua Mahony is Chief Markets Analyst at Scope Markets. Joshua has a particular focus on macro-economics and technical analysis, built up over his 11 years of experience as a market analyst across three brokers.

















