Oil hits one-month high as blockade continues, more risks emerge
- Trump sticks with blockade to squeeze Iran, and global consumers.
- US GDP could disappoint expectations.
- Why volatility may spike as we move into May.
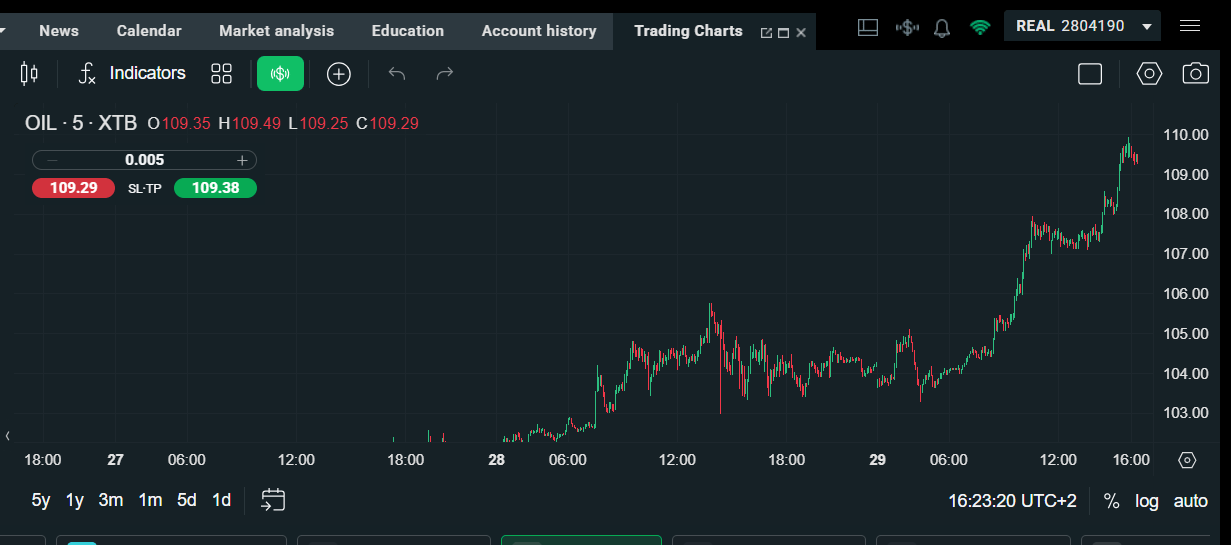
The mood is souring on Wednesday as markets digest another leg higher in the oil price. Crude is higher by more than 4% today and Brent is above $116 per barrel, a one month high. Big tech is selling off, and the narrative around AI spending and investment has become less supportive for stocks in the last 24 hours after OpenAI missed internal revenue targets.
As we move through the week, three themes are impacting market sentiment.
1. The blockade in the Strait of Hormuz
Anyone hoping for the blockade to come to an end this week have been deeply disappointed. The latest news from the White House suggests that President Trump is looking at measures to maintain the blockade for an extended period if necessary. The President met with oil company executives, presumably to boost US refinery production, especially for diesel and jet fuel. Financial markets will now need to price in the prospect of a prolonged blockade. This is obviously impacting on the oil price, which is higher by nearly 10% in the past 5 sessions. It could also lead to higher futures prices, as the market adjusts to a long-term closure of the Strait.
We assume the President wants US oil companies to boost production, however, if US oil refineries focus on ramping up production of jet fuel and diesel, it could reduce output of other products, which may lead to broader inflationary pressures for the global economy. This is a new phase of the war in Iran, and we could now see oil prices go back to the March highs around $120 per barrel for Brent.
As always with President Trump, his rhetoric on Truth Social may not reflect reality. The President has also urged Iran to sign a deal to end the US blockade. The US is using the blockade to squeeze Iran, we will now find out how long they can hold out.
If this is a long-term blockade, we will find out whether financial markets are underpricing the risks of the war in the Middle East.
2. US GDP
The market is also waiting for US GDP for Q1, which will be released on Thursday. The market is expecting a 2.3% increase in GDP, and core prices are expected to have surged to 4.1% last quarter, from 2.7% in Q4 2025. However, after Wednesday’s raft of economic data from the US, there are some who are concerned that the growth rate could disappoint expectations after weakness in housing starts and building permits in February. A weaker than expected GDP reading, or a stronger than expected rise in the prices index, could knock confidence in financial markets, which is already roiled by events in the Middle East.
The Atlanta Fed GDPNow estimate is also expecting a weaker reading for US GDP vs analyst estimates. Its model predicts a 1.2% growth rate for Q1. The Citi economic surprise index has also trended lower in recent weeks, although it remains in positive territory, suggesting that US economic data is just about meeting analyst expectations.
The latest data releases suggest that the US economy may not be as robust as the expectation for the GDP growth rate suggests. If we get a weaker reading for GDP, this could fray the market’s nerves even more.
3. Central banks: could they skew hawkish?
The FOMC meeting later this evening will give us a view about how central bankers see the energy price spike impacting the global ecomomy, now that we are close to the third month of the conflict. Consensus is for a hawkish hold from the Fed and other central banks including the BOE. However, the market impact from these meetings may be small for a few reasons. Firstly, this is expected to be Jerome Powell’s last meeting as governor, with Kevin Warsh expected to take over next month. Secondly, there are no economic projections or Dot Plot included with tonight’s decision.
This matters as Powell is unlikely to give forward guidance without the latest staff forecasts for growth and inflation. This means that the impact on financial markets could be minimal, but we will be watching the dollar, as a hawkish hold could boost the greenback at the margin.
We expect the Fed to set the tone for Thursday’s BOE and ECB meetings. The Bank of Canada also kept rates on hold on Wednesday and suggested that the future outlook for policy remains unclear due to trade talks with the US, the Middle East war and the impact of US tariffs. However, it is worth noting that the BOC said that the impact of the Middle East war on Canadian growth is expected to be small, which could shift the focus to inflationary risks. If this happens at the Fed, the BOE and the ECB then it could act as another constraint on risk sentiment as we move to the end of the month.
Chart 1: Brent Crude Oil price
Author

Kathleen Brooks
XTB UK
Kathleen has nearly 15 years’ experience working with some of the leading retail trading and investment companies in the City of London.