Nvidia: How will the company perform as its switches from a chip maker to an AI finance house?
The main event for markets this week takes place this evening, after US markets close. Nvidia, the AI giant, will report results for last quarter. Another monster report is expected. Revenues could come in above $92bn, and earnings per share could come in at $2.09.
Last quarter, Nvidia guided that Q2 revenue would be $91bn, +/- 2%. However, revenues for the first quarter of the year were higher by 85% on a YoY basis. There is no sign that the pace of growth for Nvidia is slowing down, so an earnings beat is expected by the market.
Leading up to this report, the focus is on the earnings beat,and whether Jensen Huang and his team will project the potential for $100bn quarterly revenues in the near future; after all Jensen Huang said in the last Nvidia earnings report that demand for Nvidia’s products and GPU’s is ‘parabolic’.
Nvidia’s shifting business model
The strength of Nvidia’s primary business, producing the components that are necessary for the AI build out, is strong. It is hard to deny this. Even with growing competition from China, Nvidia still holds the monopoly on GPUs. However, Nvidia has rapidly changed its business model this summer. It has gone from chip seller supremo to an AI financier. It is now essentially a chip seller, a mega AI investor and a private bank to the AI/ tech industry.
This month alone Nvidia and OpenAI finalised a deal on the Ohio data center project, with Nvidia agreeing to provide a $105bn finance package to back the world’s largest data center, which will be leased to OpenAI, the parent company of ChatGPT, for 20-years. Nvidia is also investing $1.5bn directly into SB Energy, who will provide the energy needs for the data centre.
Believe it or not, this is a scaled back version of the project, but it builds on a $100bn equity and infrastructure partnership between Nvidia and OpenAI that was signed earlier this year, where Nvidia has pledged $100bn to create 10 gigawatts of future data centres.
Nvidia is one of the world’s largest financiers of data centres, alongside being the largest producer of GPUs by a wide margin.
Nvidia: The private bank for the AI ecosystem
August was a busy month for Nvidia, it also announced a $500bn AI financing platform with 5 other financial institutions. Nvidia is moving rapidly into financing the AI build out and brushing off criticism that it is engaging in circular financing. However, in this earnings report, Nvidia’s assets and liabilities will look very different from previous quarters.
Q2 results not only about revenues
In the near term, we expect demand for its products to remain robust, but going forward, the long term profitability of the company could depend on how these investments play out. Its net income will be more closely scrutinized than before, in our view, and tonight’s results will not only be about revenues.
Key metrics to watch for in this report
This is not the only metric that is worth watching in tonight’s report. Other Net Income will include unrealised gains in its multiple AI investments, Also worth watching is The Non-Marketable Securities section, which includes Nvidia’s investments in private companies. This needs to be watched closely to see the pace of Nvidia’s investment growth. Last quarter it was $43bn, a year ago this was $3bn. We expect it to grow significantly in the coming quarters.
Nvidia’s changing risk profile
Nvidia is the world’s largest company, it is worth $5.2 trillion, and so its performance matters for global stock markets. As the company transitions from a pure chip and GPU maker to a financier for the AI revolution, investors need to assess the risk of default on these investments, the ROI, and how much net income is generated from its financing plans and equity stakes.
Questions such as the future of demand for AI, the depreciation trajectory of data centres, and the normalization of capex spend are starting to matter more than Nvidia’s GPU growth profile.
Ultimately, investors want to know if these investments will pay off, although it could take years to find the answer.
The impact on its future valuation
Nvidia is still a reasonably priced AI stock. Its forward P/E ratio is 23 times earnings, which is just above 20x for the S&P 500. However, this may not sway investors later tonight. If its investments are seen as jeopardising future profits, then its valuation metrics could deteriorate. Of course, if they pay off, then Jensen Huang’s prediction that Nvidia could become the first $20 trillion company may come true.
The technical outlook
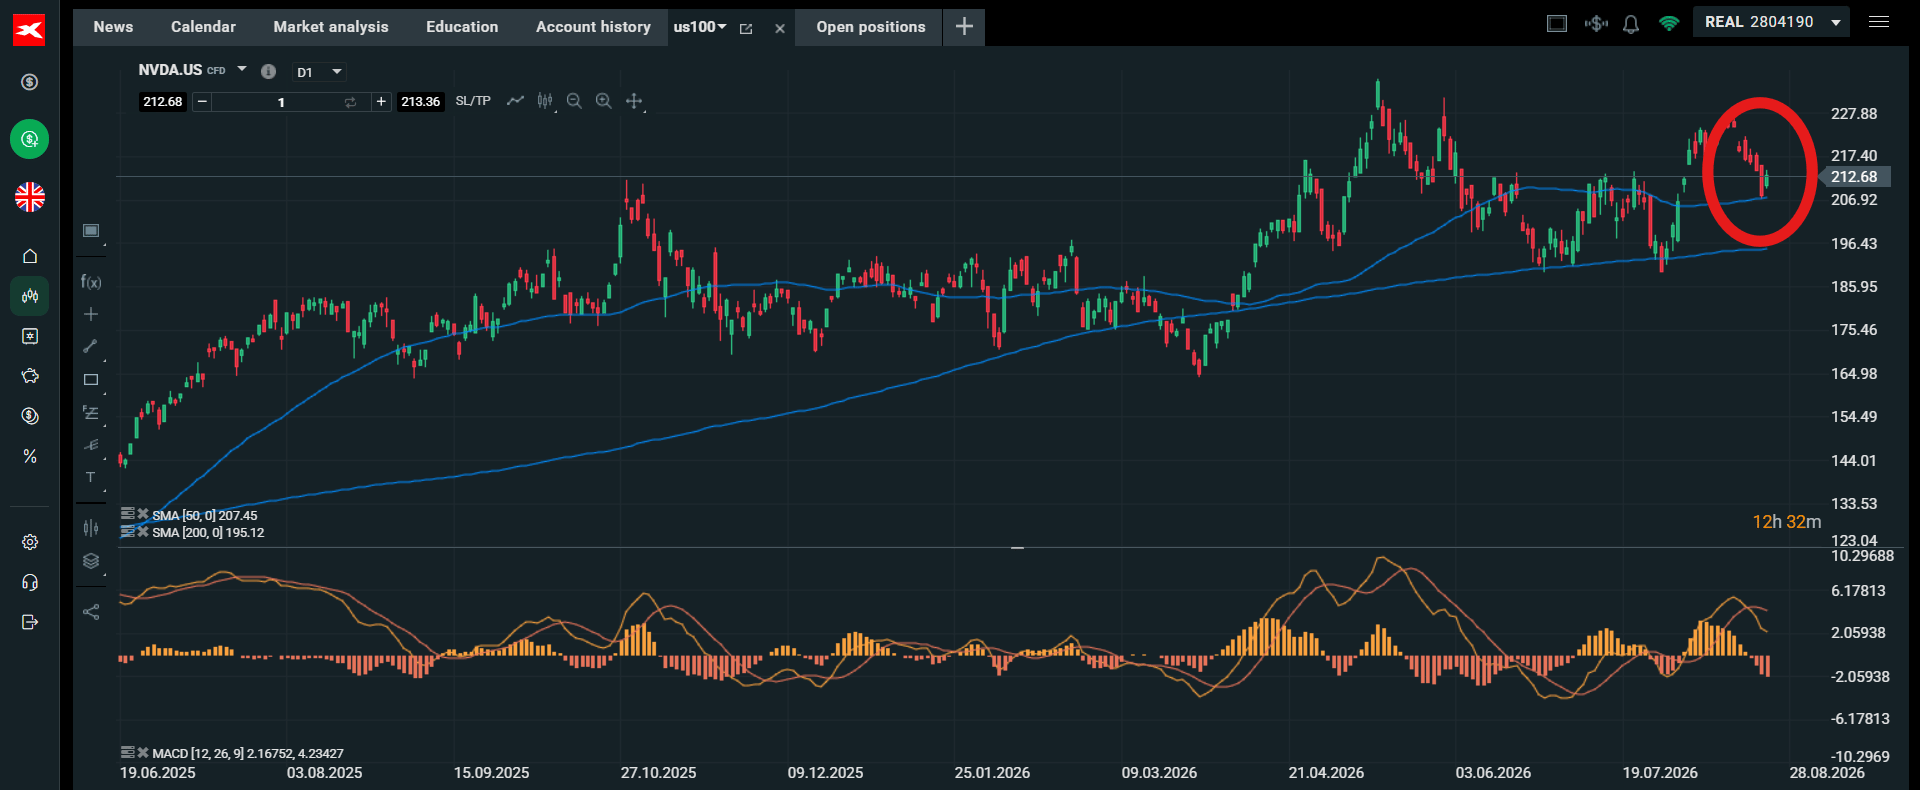
From a technical perspective, the stock price jumped by 2% on Tuesday, and bounced off its 50-day sma support at $207, rising to $213, it is also slightly higher in the pre-market on Wednesday. A break above $216 is a bullish development, while a break below $195 could signal further losses back towards $190 lows from the end of July.
Chart 1: Nvidia daily chart
Author

Kathleen Brooks
XTB UK
Kathleen has nearly 15 years’ experience working with some of the leading retail trading and investment companies in the City of London.

















