Non-Farm Payrolls August Preview: US dollar is waiting for good news
- Payroll expected to dip to 1.4 million from 1.763 million in July.
- Unemployment rate to drop to 9.8% from 10.2%.
- Dollar boosted by better than forecast August manufacturing ISM.

The long-awaited US economic slowdown from the second Covid wave never arrived but the absence of dire statistics has not been enough to lift the dollar from its five week slough. Good news is required and the best would be a surging job market.
Non-farm payrolls are forecast to rise 1.4 million in August, down from 1.763 million in July and the smallest gain since the recovery began in May.
NFP
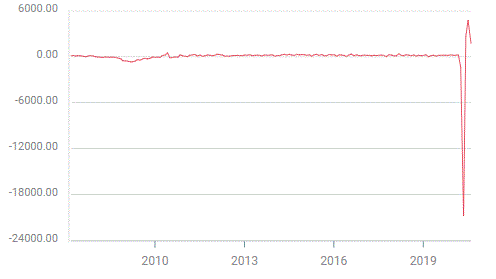
The unemployment rate (U-3) is predicted to fall to 9.8%, the lowest since the pandemic shutdowns peaked in April, from 10.2% in July. The underemployment rate (U-6) is projected to rise to 17.3% in August from 16.5% for July. It would be the first increase since April.
Average hourly earnings are estimated to be flat in August after July’s 0.2% gain. Annual wages should fall to 4.5% from 4.8%.
ADP payrolls
The private payrolls from Automatic Data Processing that are issued the Wednesday before the Employment Situation Report are generally considered the best indicator for the national list from the Labor Department. Assembled from the about 500,000 companies whose payrolls are processed by ADP, they represent a smaller version of the non-governmental jobs tracked by Labor.
These firms are projected to add 950,000 new employees in August, far more than the 167,000 reported in July.
Despite their relatively close historical association with non-farm payrolls the estimates for the ADP employment change figures from the Reuters survey of economists have been uncharacteristically wayward for the past three months, the correlation to the non-farm payrolls numbers have been weak and the revisions to ADP have been uncommonly large.
In July the estimate for ADP’s payrolls was 1.5 million. The actual figures was, as above, just 167,000. The NFP figure was 1.763 million on a 1.6 million forecast.
In June the ADP forecast was 3 million, the first release was 2.369 million and the revision was to 4.314 million. The NFP estimate was 3 million with 4.8 million and a 4.791 revision.
May had similar problems. The consensus ADP estimate was -9 million, initial release was -2.760 million and the adjustment one month later was to 3.341 million, a swing of 6.101 million. The NFP forecast was -8 million, reality was 2.509 million revised to 2.699 million.
The labor market has been particularly hard to gauge through the enormous layoffs of March and April. May’s surprise resumption of hiring was foreseen by very few analysts.
Nonetheless with the faltering accuracy of the ADP forecast of late and the declining correlation with NFP, the relative importance of this statistic and its possible market impact is diminished.
Manufacturing PMI
More evidence of the difficulty analysts are having in estimating the strength of the recovery comes from purchasing managers’ indexes. Manufacturing PMI’s have out-performed estimates for three months running. In June the forecast was 49.5, the result was 52.6. In July it was 53.6 and 54.2 and in August the prediction was 54.5 and the reality 56.
Manufacturing PMI
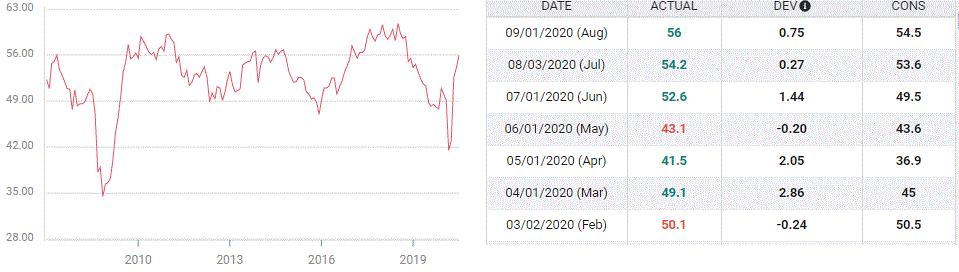
The discrepancy was even greater for the new orders index. In June the estimate was 36.1 the result 56.4; in July it was 46.8 and 61.5 and for August the gap was 53.5 and 67.6.
Only employment has lagged in two of the last three months and remains in contraction: June estimate 43, result 42.1; July estimate 48.3, 44.3; august estimate 45.8, result 46.4.
Initial jobless claims
Jobless claims are a third indicator where the standard correlation has faltered.
If we assume that NFP will rise as expected in August that would be four months of payroll gains accompanied by average initial claims of well over a million each week. Such would be a near impossibility in any prior economy.
Claims are expected to drop to 950,000 in the August 28 week, from 1.006 million previously. This would be just the second week below 1 million in the last six months. Continuing claims at estimated to fall to 14 million on August 21 from 14.535 in the prior week.
Conclusion and the dollar
The predictive correlations between ADP payrolls, PMI employment indexes and initial jobless claims with non-farm payrolls have fallen considerably since economic closures in March and April.
Overall US job hiring has continued at a strong pace for four months despite indicators that in normal labor markets would have pointed at a stall or contraction in job creation.
The US is experiencing an unusual two-tier labor market with continuing layoffs as some businesses, restaurants and small retail stores that depend on foot traffic, continue to fail and lay-off workers and the overall economy which is rapidly returning to normal.
Despite the five week decline in the dollar, the market appears to be reassessing the state of the US economy and responding to statistical improvements.
Tuesday’s August manufacturing PMI, 56 on at 54.5 forecast and the highest reading since November 2018 is an example. Just after the release the euro soared 1.2011, its highest in over two years but the surge was brief and unsustained with the united currency closing at 1.1912, below its open at 1.1936.

The dollar has not reversed but it may have reached its negative limit on current US conditions. From here it follows the course of the American economy.
Author

Joseph Trevisani
FXStreet
Joseph Trevisani began his thirty-year career in the financial markets at Credit Suisse in New York and Singapore where he worked for 12 years as an interbank currency trader and trading desk manager.
















