New Zealand Dollar slumps against US Dollar amid firm hawkish Fed bets
- The New Zealand Dollar slides to near 0.5895 against the US Dollar due to upbeat Fed interest rate hike expectations.
- Investors keenly await the US Manufacturing PMI and Job Openings data.
- The RBNZ is anticipated to raise its cash rate in the policy meeting on Wednesday.
The New Zealand Dollar (NZD) is down 0.35%, marginally below 0.5900 against the US Dollar (USD) during the European trading session on Tuesday. The Kiwi pair weakens as the US Dollar outperforms its peers, with financial markets becoming increasingly confident that the Federal Reserve (Fed) will raise interest rates at its policy meeting this month.
As of writing, the US Dollar Index (DXY), which gauges the Greenback’s value against six major currencies, trades 0.2% higher to near 99.60.
US Dollar Price Today
The table below shows the percentage change of US Dollar (USD) against listed major currencies today. US Dollar was the strongest against the New Zealand Dollar.
| USD | EUR | GBP | JPY | CAD | AUD | NZD | CHF | |
|---|---|---|---|---|---|---|---|---|
| USD | 0.23% | 0.13% | 0.24% | 0.13% | 0.34% | 0.38% | 0.23% | |
| EUR | -0.23% | -0.10% | 0.02% | -0.10% | 0.10% | 0.14% | -0.01% | |
| GBP | -0.13% | 0.10% | 0.11% | 0.00% | 0.20% | 0.24% | 0.09% | |
| JPY | -0.24% | -0.02% | -0.11% | -0.10% | 0.10% | 0.15% | -0.02% | |
| CAD | -0.13% | 0.10% | -0.01% | 0.10% | 0.20% | 0.23% | 0.08% | |
| AUD | -0.34% | -0.10% | -0.20% | -0.10% | -0.20% | 0.05% | -0.12% | |
| NZD | -0.38% | -0.14% | -0.24% | -0.15% | -0.23% | -0.05% | -0.15% | |
| CHF | -0.23% | 0.00% | -0.09% | 0.02% | -0.08% | 0.12% | 0.15% |
The heat map shows percentage changes of major currencies against each other. The base currency is picked from the left column, while the quote currency is picked from the top row. For example, if you pick the US Dollar from the left column and move along the horizontal line to the Japanese Yen, the percentage change displayed in the box will represent USD (base)/JPY (quote).
USD steadies as Fed pricing stays firm
Strategists at Brown Brothers Harriman note that the "USD recovered most of yesterday’s pullback" as Fed expectations remain firmly embedded in futures pricing. They highlight that "Fed funds futures price in 67% odds of a 25bps hike on September 16 and imply 60bps of tightening over the next twelve months," adding that this elevated pricing is likely to persist into the September meeting, with "the August CPI on September 11 the decisive test."
In Tuesday’s session, investors will pay close attention to the US ISM Manufacturing PMI data for August and the US JOLS Job Openings data for July, which will be published at 14:00 GMT.
Analysts at BBH see the headline reading "at 55.2 vs. 55.6 in July consistent with resilient manufacturing activity." More importantly for the policy outlook, the "Prices Paid index is seen falling to a six-month low at 70.8 vs. 71.1 in July signaling diminishing upside inflation risk."
On the labor side, BBH flags the "July Job Openings and Labor Turnover Survey (JOLTS) "is expected to reinforce the US labor market’s low hire, low fire backdrop."
According to the FXS Economic Calendar, US employers are expected to have posted 7.3 million fresh jobs, slightly lower than 7.359 million in June.
“Together, these data points are seen as key inputs for the Fed and potential drivers of further Dollar moves into the September decision,” BBH added.
On the New Zealand Dollar front, investors await the Reserve Bank of New Zealand’s (RBNZ) monetary policy decision on Wednesday.
RBNZ hike seen as fully priced, focus shifts to hawkish tone and projections
Analysts at ING expect the Reserve Bank of New Zealand to deliver a “25bp” rate increase “to 2.75%” at tomorrow’s meeting, noting that “consensus is unanimous and markets are fully pricing in the move.” With the hike largely anticipated, ING argues that the reaction in the New Zealand Dollar will hinge on the policy communication, stressing that “the impact on the New Zealand dollar will be highly dependent on whether the statement will still include firmly hawkish guidance, and on updated rate/economic projections.”
NZD/USD Technical Analysis
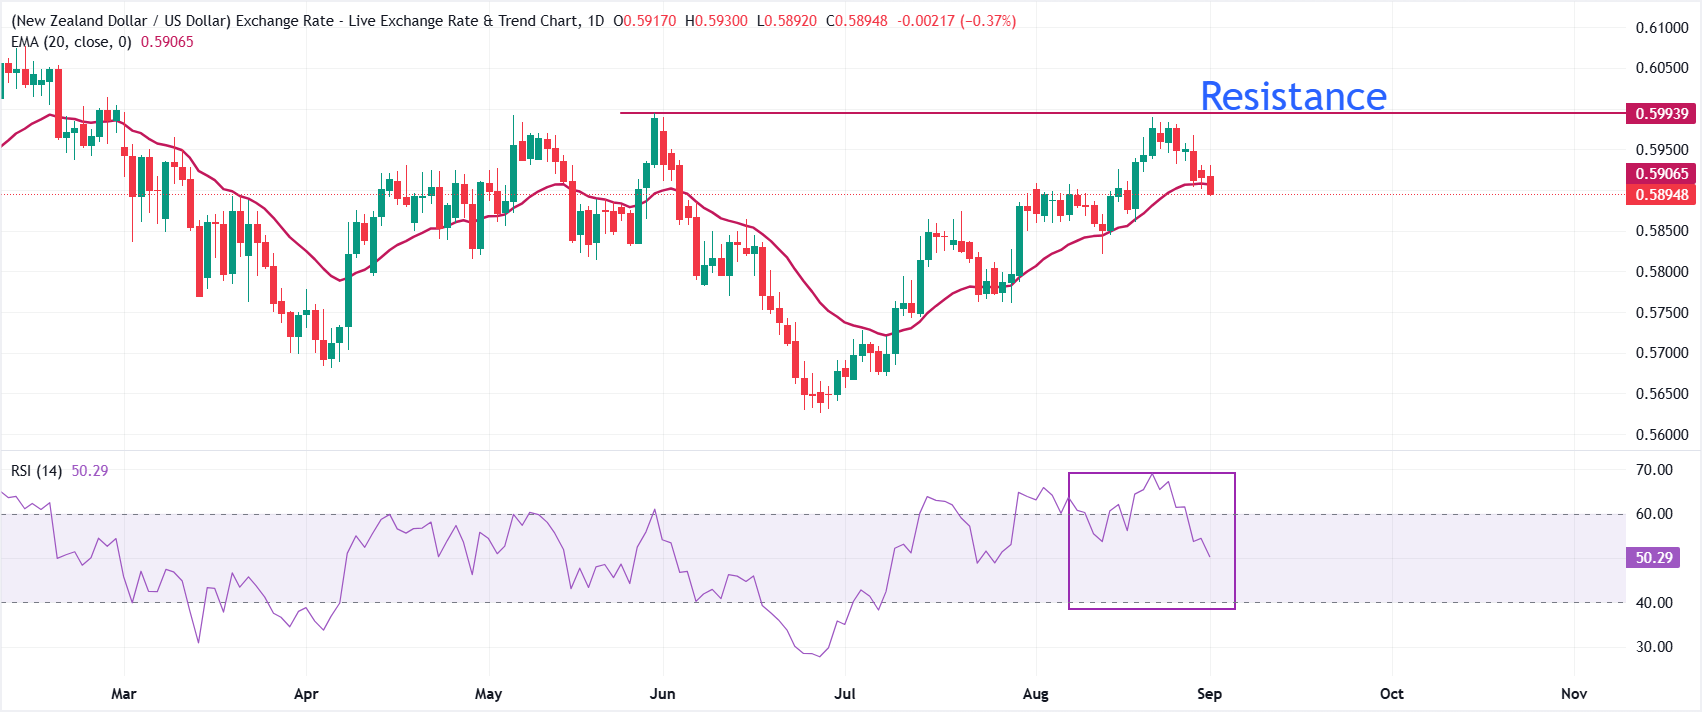
In the daily chart, NZD/USD trades at 0.5894, maintaining a mildly bearish near-term bias as it holds just beneath the 20-day Exponential Moving Average (EMA) at 0.5907, which acts as immediate overhead resistance. The Relative Strength Index (RSI) at 50 suggests neutral momentum after the recent pullback, hinting that directional conviction is currently driven more by the pair’s position under the short-term trend barrier than by momentum signals.
On the topside, initial resistance is defined by the 20-day EMA at 0.5907; a daily close above this level would ease downside pressure and open the path for a more sustained recovery. With no clear nearby structural supports derived from the provided data, traders may look to prior lows on the chart as potential demand zones, while the current configuration leaves NZD/USD vulnerable to further slippage as long as it remains capped below the short-term EMA.
(The technical analysis of this story was written with the help of an AI tool. Know more.)
Economic Indicator
RBNZ Interest Rate Decision
The Reserve Bank of New Zealand (RBNZ) announces its interest rate decision after each of its seven scheduled annual policy meetings. If the RBNZ is hawkish and sees inflationary pressures rising, it raises the Official Cash Rate (OCR) to bring inflation down. This is positive for the New Zealand Dollar (NZD) since higher interest rates attract more capital inflows. Likewise, if it reaches the view that inflation is too low it lowers the OCR, which tends to weaken NZD.
Read more.Next release: Wed Sep 02, 2026 02:00
Frequency: Irregular
Consensus: 2.75%
Previous: 2.5%
Source: Reserve Bank of New Zealand
The Reserve Bank of New Zealand (RBNZ) holds monetary policy meetings seven times a year, announcing their decision on interest rates and the economic assessments that influenced their decision. The central bank offers clues on the economic outlook and future policy path, which are of high relevance for the NZD valuation. Positive economic developments and upbeat outlook could lead the RBNZ to tighten the policy by hiking interest rates, which tends to be NZD bullish. The policy announcements are usually followed by interim Governor Christian Hawkesby's press conference.
Author

Sagar Dua
FXStreet
Sagar Dua is associated with the financial markets from his college days. Along with pursuing post-graduation in Commerce in 2014, he started his markets training with chart analysis.
















