GBP/USD Weekly Forecast: Where next for the pound after the Downing Street debacle
- GBP/USD hit 28-month lows below 1.1900 on recession fears, UK political woes.
- The US dollar emerged an undisputed winner amid growth fears, hawkish Fed minutes.
- Cable is ‘sell on bounce’ while below 21 DMA, ahead of UK GDP, US inflation.

Another down week for the GBP/USD pair, as the high beta currency was thrown under the bus amidst UK political drama, looming recession fears and Brexit concerns. Cable tested levels unseen since March 2020 but managed to recover some ground, with attention now focussed on the UK monthly GDP and the US inflation data due in the week ahead.
GBP/USD: A brutal week
Amid a quiet start to a new week, GBP/USD snapped the previous slump and staged a decent comeback, as the US dollar paused its upsurge. The Independence Day holiday in the US kept the dollar bulls sidelined, although the discouraging Brexit news over the weekend checked cable’s rebound. On Sunday, Germany and Ireland told Britain there was no legal or political justification for Prime Minister Boris Johnson's plan to override parts of the current Brexit trade deal with Northern Ireland (NI).
The limited recovery stint faded and the currency pair extended the previous week’s sell-off on Tuesday, as well as, on Wednesday, cracking the mid-June low of 1.1933 to record fresh 28-month troughs at 1.1876. Hell broke loose across the financial markets while liquidity returned along with the US traders, which bolstered the demand for the US dollar as an ultimate safe-haven asset. Markets began pricing in a 70% chance of a global recession, as the European gas crisis heightened growth worries for the UK and Europe. Meanwhile, aggressive Fed rate hike expectations fuelled fears over the US economy tipping into recession, especially in light of the recent series of weak US macro data.
The UK political uncertainty gripped sterling mid-week after speculation surrounding UK PM Boris Johnson’s resignation built up after the leader was abandoned by over 50 ministers and Tory lawmakers, as they withdrew support following his involvement in many scandals. The Bank of England’s (BOE) biannual Financial Stability Report (FSR) showed that the global and the UK economic outlook deteriorated materially, adding to the pound’s pain. Meanwhile, stronger UK S&P Global/CIPS Composite PMI failed to lure GBP bulls, as risk-off flows dominated.
The major witnessed a turnaround Thursday after GBP bulls were rescued by the announcement of PM Johnson’s resignation. Johnson said, in his press conference, that he will remain in his position until a new leader for the Conservative Party is selected in late summer or early fall. Although Johnson’s stepping down created a void, it was welcomed by the pound market, as it will likely reduce the ongoing tensions with the European Union (EU) surrounding the Brexit trade deal. The dollar also eased and global stocks embarked on a relief rally, as investors reassessed risks of an incoming recession. Separately, BOE policymaker Catherine Mann said that inflation uncertainty had strengthened the case for front-loading rate rises. The hawkish comments also lent support to the spot.
GBP/USD returned to the red zone on Friday after the greenback picked up bids on a wave of renewed risk-aversion, following news that the former Japanese Prime Minister Shinzo Abe was shot during his election campaign speech in Nara. Buyers also remained cautious amid looming UK political uncertainty, with the search for a new leader leaving them anxious.
The pair managed to stage a rebound and steadied above 1.2000 as the greenback lost strength during the American trading hours on Friday. The US Bureau of Labor Statistics' monthly publication showed that Nonfarm Payrolls in the US rose by 372,000 in June, beating analysts' forecast for an increase of 268,000. The Unemployment Rate remained unchanged at 3.6% as expected and the Average Hourly Earnings rose by 5.1% on a yearly basis, down from 5.3% in May. The US Dollar Index erased its daily gains after the US jobs report but ended up closing the week more than 1% higher.
Week ahead: Is all about US inflation
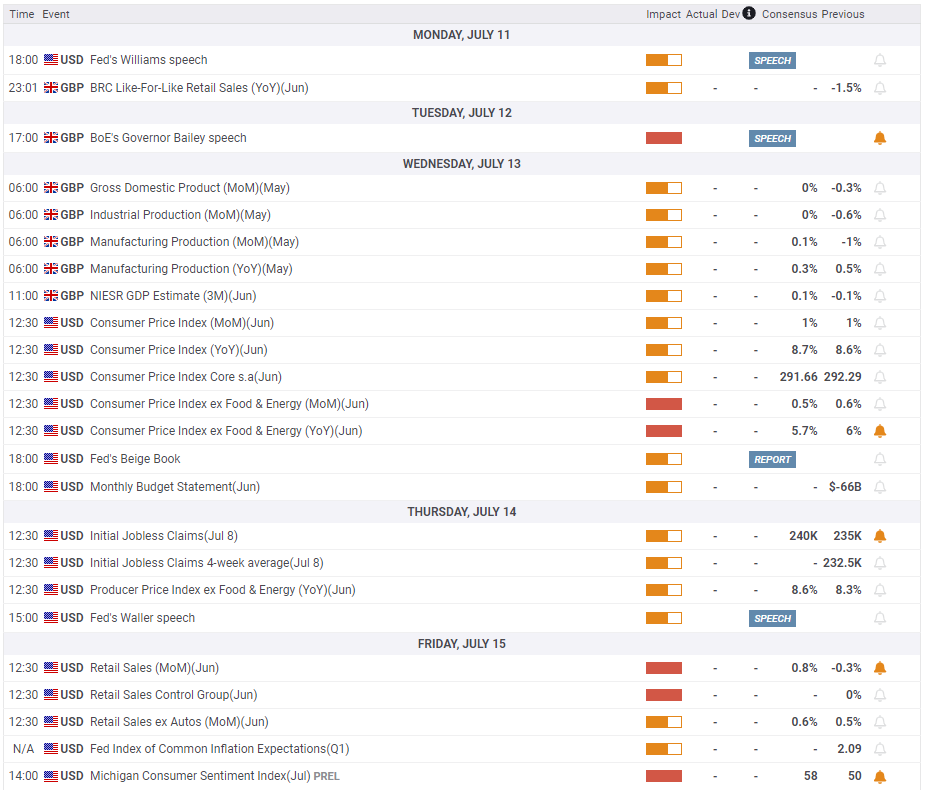
UK politics will continue to drive sentiment around the pound, investors will brace for UK GDP and US Consumer Price Index (CPI) data for the next direction in GBP/USD. Monday is data-sparse on both sides of the Atlantic and hence, attention shifts towards Tuesday’s appearance by BOE Governor Andrew Bailey. Bailey is due to speak about the economic landscape at an event hosted by the Official Monetary and Financial Institutions Forum, in London.
Wednesday stands out amid a relatively data-light week, as the UK monthly GDP and Industrial data will be published, followed by the critical US CPI release. The US Producer Price Index (PPI) will drop in on Thursday alongside the weekly Jobless Claims report.
The US Retail Sales and Prelim UoM Consumer Sentiment data will bring an eventful end to the week. The most significant on the final trading of the week, however, remains the Fed’s Index of Common Inflation Expectations, which is developed and watched by the world’s most powerful central bank to determine its rate hike outlook.
GBP/USD: Technical outlook
Following the price action witnessed in the second half of the week, the Relative Strength Index (RSI) indicator on the daily chart rose to 40, suggesting that the bearish bias stays intact while the pair stages a technical correction.
1.2150 (21 DMA) aligns as first resistance. In case the pair rises above that level and starts using it as support, it could extend its recovery toward 1.2200 (psychological level) and 1.2300 (50 DMA, Fibonacci 23.6% retracement of the downtrend that started in late February).
On the downside, GBP/USD could target 1.1875 (July 6 low), 1.1800 (psychological level) and 1.1750 (static level from March 2020).

GBP/USD: Sentiment poll
A large portion of experts polled by FXStreet expects GBP/USD to remain bearish next week. On the one-week view, the average target is located at 1.1950.

Author

Dhwani Mehta
FXStreet
Residing in Mumbai (India), Dhwani is a Senior Analyst and Manager of the Asian session at FXStreet. She has over 10 years of experience in analyzing and covering the global financial markets, with specialization in Forex and commodities markets.

















