GBP/USD Weekly Forecast: Pound Sterling recovery at risk ahead of fresh batch of US data
- Pound Sterling clinched monthly highs above 1.3250 against the US Dollar on a buying resurgence.
- GBP/USD braces for a bunch of top-tier US economic data releases, following the Autumn Budget announcement.
- The pair’s recovery appears at risk amid a Death Cross pattern, even as the daily RSI stays above the midline on the daily chart.
The Pound Sterling (GBP) staged an impressive recovery against the US Dollar (USD), as GBP/USD clinched fresh monthly highs above the 1.3250 psychological level.
Pound Sterling capitalized on the UK Budget relief
Amidst increased odds of interest rate cuts by the Bank of England (BoE), GBP/USD found its feet, thanks to the UK Autumn Budget and growing expectations surrounding a US Federal Reserve (Fed) December rate reduction.
The CME Group’s FedWatch Tool showed an 85% chance of the Fed lowering rates next month against a 40% probability seen a week ago. Dovish commentary from Fed officials and mixed US data ramped up odds for such a move by the central bank.
New York Fed President John Williams said on November 21 that “US interest rates could fall without putting the Fed's inflation goal at risk, while helping guard against a slide in the job market,” per Reuters.
Earlier in the week, Fed Governor Christopher Waller also favored a rate cut before the end of the year and expressed concerns about a "still fragile" labor market.
San Francisco Fed President Mary Daly also noted that “the Fed shouldn’t hold off on cutting rates now out of fear it may need to reverse course later."
Later in the week, the Pound Sterling recovery gained traction due to the UK Budget announcement, which eased pressures surrounding fiscal concerns and bolstered GBP/USD.
Citing analysts, Reuters reported, “fears about slow growth, weak productivity and sticky inflation are not reflective of an attractive investment backdrop.”
Chancellor of the Exchequer Rachel Reeves' budget was well received by markets despite the Office for Budget Responsibility (OBR) downward revision of the economic growth for 2025.
However, the pair’s upswing remained restricted because of the details of the Budget, entailing back-loaded tax measures.
Week ahead: US data to dominate
The week kicks off with the US ISM Manufacturing PMI on Monday.
Next of note for markets remains the monthly ADP Employment Change report on Wednesday, followed by the US ISM Services PMI release.
On Thursday, the weekly Unemployment Claims will be reported ahead of the release of the Fed’s preferred inflation measure, the Personal Consumption Expenditures Price Index, on Friday.
Besides the economic data, speeches from BoE policymakers and updates on the US-Ukraine discussions on the potential peace deal will also be closely followed.
GBP/USD Technical Analysis
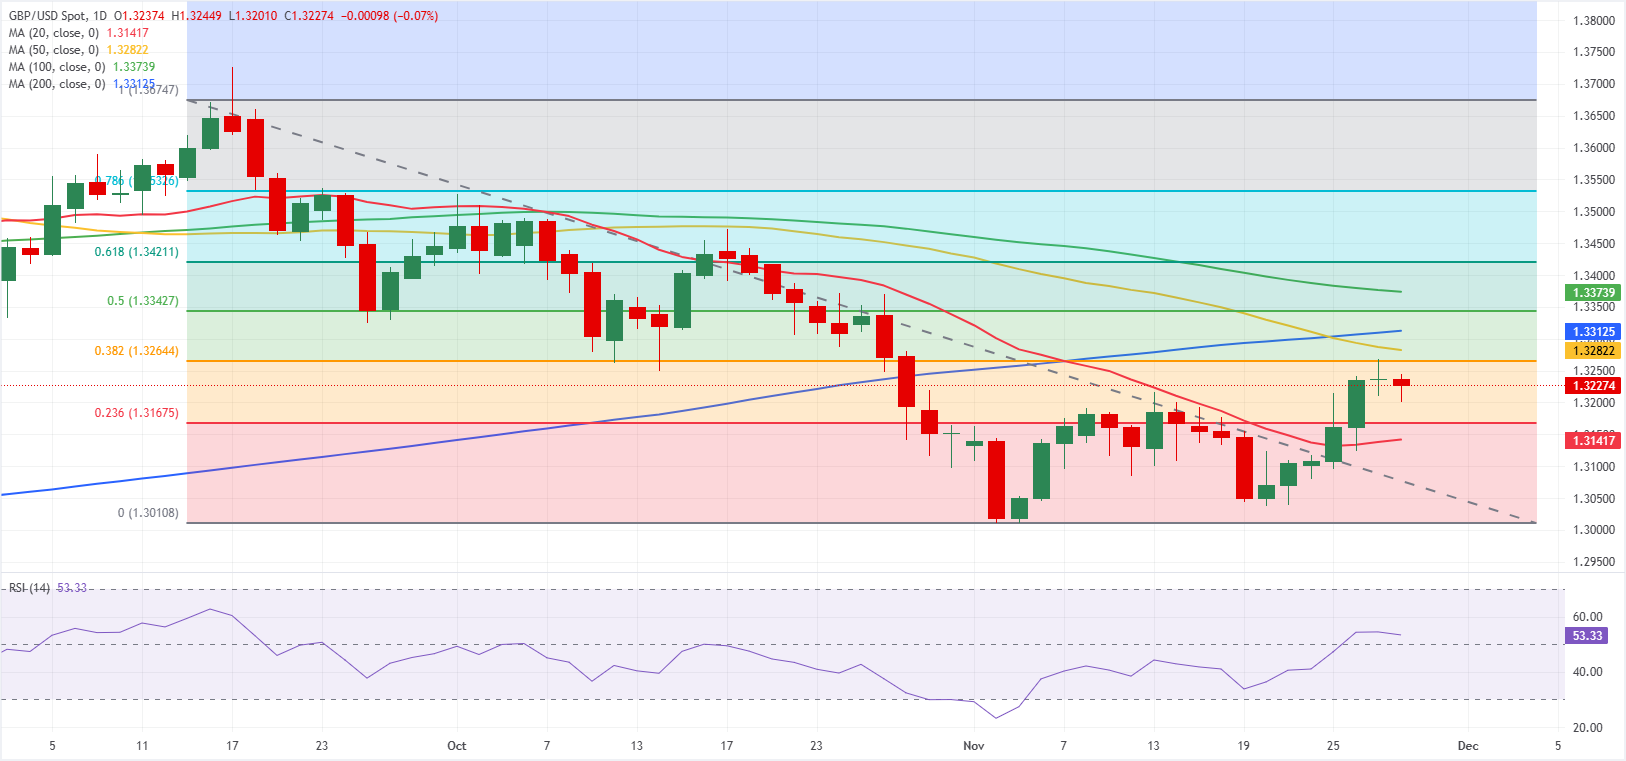
The 20-day Simple Moving Average (SMA) has started to turn higher but remains below the 50- and 100-day SMAs. The 50- and 100-day SMAs extend their decline, while the 200-day SMA rises; price stays below the 50-, 100- and 200-day SMAs but above the 20-day. The Relative Strength Index (14) prints at 53 (neutral), signaling modest momentum recovery. Measured from the 1.3675 high to the 1.3011 low, the 38.2% retracement at 1.3264 acts as near-term resistance, with the 50% at 1.3343 above.
Bias remains uneven, with improving short-term momentum yet persistent overhead hurdles. The 20-day SMA currently stands at 1.3142 and offers nearby support, while the 200-day SMA at 1.3313 acts as dynamic resistance; the 50- and 100-day SMAs continue to slope lower. RSI holding above 50 would increase the odds of an upside extension, while a pullback would expose the 20-day SMA as the first line of defense.
(The technical analysis of this story was written with the help of an AI tool)
BoE FAQs
The Bank of England (BoE) decides monetary policy for the United Kingdom. Its primary goal is to achieve ‘price stability’, or a steady inflation rate of 2%. Its tool for achieving this is via the adjustment of base lending rates. The BoE sets the rate at which it lends to commercial banks and banks lend to each other, determining the level of interest rates in the economy overall. This also impacts the value of the Pound Sterling (GBP).
When inflation is above the Bank of England’s target it responds by raising interest rates, making it more expensive for people and businesses to access credit. This is positive for the Pound Sterling because higher interest rates make the UK a more attractive place for global investors to park their money. When inflation falls below target, it is a sign economic growth is slowing, and the BoE will consider lowering interest rates to cheapen credit in the hope businesses will borrow to invest in growth-generating projects – a negative for the Pound Sterling.
In extreme situations, the Bank of England can enact a policy called Quantitative Easing (QE). QE is the process by which the BoE substantially increases the flow of credit in a stuck financial system. QE is a last resort policy when lowering interest rates will not achieve the necessary result. The process of QE involves the BoE printing money to buy assets – usually government or AAA-rated corporate bonds – from banks and other financial institutions. QE usually results in a weaker Pound Sterling.
Quantitative tightening (QT) is the reverse of QE, enacted when the economy is strengthening and inflation starts rising. Whilst in QE the Bank of England (BoE) purchases government and corporate bonds from financial institutions to encourage them to lend; in QT, the BoE stops buying more bonds, and stops reinvesting the principal maturing on the bonds it already holds. It is usually positive for the Pound Sterling.
Author

Dhwani Mehta
FXStreet
Residing in Mumbai (India), Dhwani is a Senior Analyst and Manager of the Asian session at FXStreet. She has over 10 years of experience in analyzing and covering the global financial markets, with specialization in Forex and commodities markets.

















