Forex market report: Currency movements and November risks

Elev8, a global CFD broker, continues its Traders Outlook article series. This issue focuses on the most significant currency changes in October and outlines the main events to watch for in November 2026.
What happened in October
The chart below shows how selected currencies performed in October 2026. Deep teal marks major currencies and the U.S. Dollar Index (DXY). All currencies' performance is measured against their relevant benchmark USD exchange rate. For the Chinese renminbi, the onshore rate (USDCNY) is used.
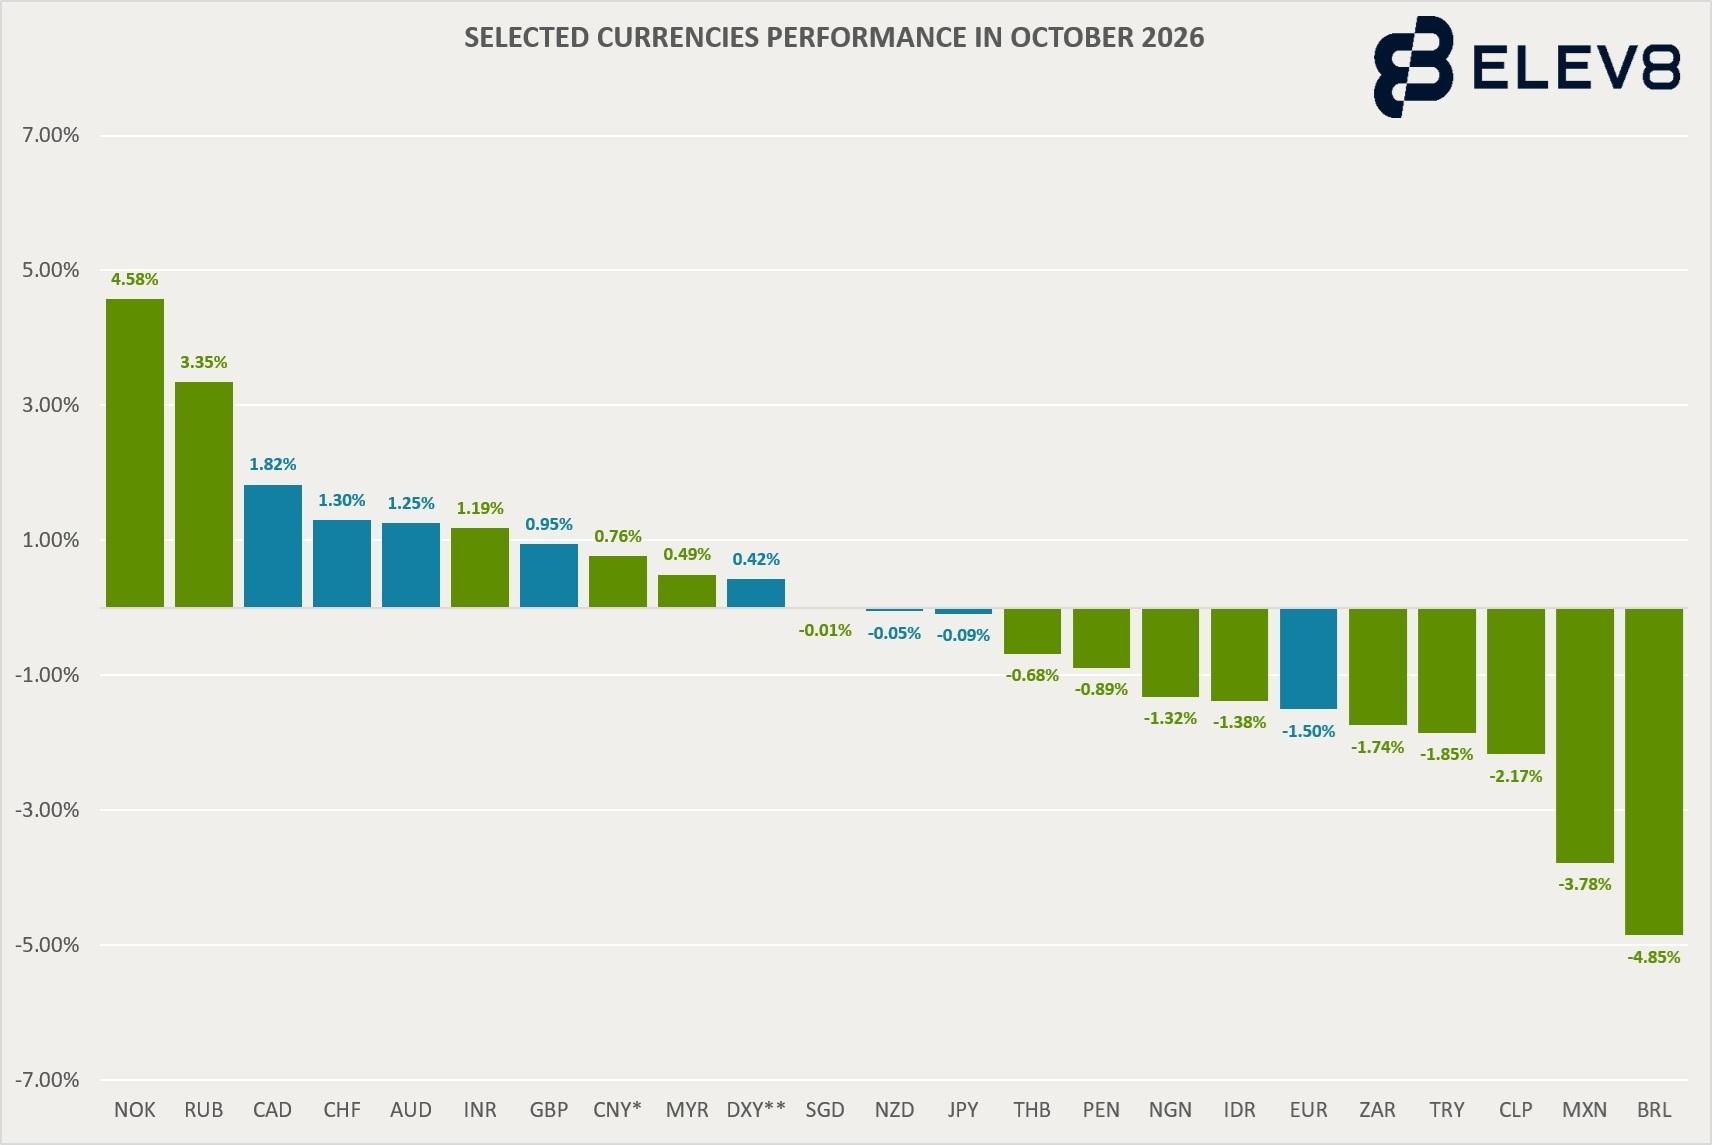
* USDCNY, onshore rate
** DXY (U.S. Dollar Index)
Introduction
In October, we saw choppy price action across major currency pairs. Major Latin American (LatAm) currencies—Brazilian real (BRL), Mexican peso (MXN), and Chilean peso (CLP)—weakened, while oil-correlated commodity currencies, such as Norwegian krone (NOK), Russian rouble (RUB), and Canadian dollar (CAD), rallied. The common driver for best performers was the surge in oil prices: Brent crude oil price rallied approximately 15% in October due to escalating conflict in the Middle East and attacks on shipping through the Strait of Hormuz. As for the LatAm currencies, they all suffered for their own specific, mostly local reasons.
In this article, Elev8 broker provides retail traders with market data and analytics to see more market context so they can respond effectively to changing conditions.
What happened in October
NOK, RUB, and CAD
The conflict in the Strait of Hormuz, through which around one-fifth of global oil supplies pass, has been a persistent theme in October. It continued to hurt oil importers—notably, European countries—pushing inflation expectations higher, increasing the probability of higher interest rates, and raising the risk of a potential recession in 2027. Unsurprisingly, the euro (EUR) was the worst-performing currency among the majors in October. At the same time, elevated oil prices had a direct boost on current account surpluses and government revenues of major energy producers.
Norwegian Krone, Russian Rouble and Canadian Dollar
NOK, RUB, and CAD were the best-performing currencies among the 23 currencies tracked by Elev8 broker. As already said, oil was a key driver here.
For example, Russia's oil and gas tax revenue was projected to rise 10% year-on-year in October to approximately 1 trillion roubles (USD 11.97 billion), boosted by higher global oil prices and quarterly tax payments. In fact, revenue was expected to more than double compared with September, though cumulative January-October revenue was still estimated to be down 14% year-on-year. Diplomatic signals around potential trilateral U.S.-Russia-Ukraine talks also improved the sentiment.
Apart from the energy windfall, NOK received an additional boost from an indirect demand for the krone as traders piled into EURNOK short trade, after political turbulence in France hit the bond market. Indeed, at one point, the EURNOK pair was down some 16% since late April.
As for the CAD, it is worth remembering that Canada is the world's fourth-largest oil producer, so its export revenues were certainly boosted by the rally in crude oil. An additional bullish factor was in monetary policy. The Bank of Canada (BoC) raised its benchmark interest rate by 25 basis points (bps) to 2.50% on 28 October, its first hike in more than three years. Governor Tiff Macklem said that 'there could be a need to raise the policy rate further'. Moreover, the BoC sharply revised higher its 2027 inflation forecast from 2.0% to 3.1%.
Brazilian Real, Mexican Peso, and Chilean Peso
LatAm currencies suffered greatly in October, but each for its particular reasons.
BRL performance was dominated by a single event: presidential elections. The Brazilian stock market rallied aggressively before the vote (scheduled on 25 October) on expectations that Senator Flavio Bolsonaro would defeat incumbent President Luiz Inacio Lula da Silva. However, Lula's re-election triggered an immediate and violent reversal. USDBRL surged from 4.98 on 23 October to 5.41 on 26 October, a single-weekend devaluation of approximately 8.7%. In addition, Brazil's fiscal challenges were hurting investors' sentiment. Reuters reported that the country's debt reached $1.8 trillion as interest costs surged.
MXN dropped sharply in October as investors rapidly exited the popular 'carry trade' amid rising market volatility and growing expectations that the Federal Reserve (Fed) may have to remain hawkish for longer. At the same time, hints that Mexico's central bank was leaning dovish reduced the currency's appeal compared to the U.S. dollar. So did the uncertainty over the country's trade negotiations with the U.S. (a resolution to the USMCA free trade renegotiation is yet to emerge).
CLP was in trouble due to local specifics. Local mining disruptions, including labour strikes and a scandal over fake production numbers at state miner Codelco, hurt investor sentiment. At the same time, Chile's domestic unemployment climbed to its highest point since 2021, dampening confidence in the broader economy. In addition, as the world's largest copper producer, the Chilean currency is particularly vulnerable to fears of a global recession, which have intensified recently amid surging oil prices.
What to expect in November
Elev8 broker highlights six main themes for traders to watch out for in November:
- The fallout from the U.S. midterm elections
- Crude oil price (Middle East conflict)
- Monetary policy divergence
- China slowing yuan appreciation
- Inflation risks
- Cash deficit
First, the recent victory of the Democratic Party in the U.S. midterm elections has already weakened the dollar. Investors now expect less government spending, cooler inflation, and an easier path for the Fed. The key risk here is that investors may prove to be too optimistic.
Second, a Democratic sweep of Congress does not automatically solve the conflict in the Middle East. Therefore, the recent 8% drop in crude oil prices is based largely on hopes. Still, should energy prices continue to decline, oil-importing regions such as Europe and Japan will benefit, which may boost their currencies.
Third is what we at Elev8 broker call 'central banks clash'. Right now, major central banks seem to be heading in different directions. While the Fed held rates steady, markets anticipate potential rate hikes from the Bank of England (BoE), the European Central Bank (ECB), and the Bank of Japan (BoJ). This divergence has the potential to create sharp swings across currency pairs.
Fourth, it is worth watching how China's decision to devalue the yuan will impact other major currencies. China's central bank (PBoC) raised the foreign exchange reserve requirement for local banks to cool down the yuan after months of steady gains against the greenback. This requirement may provide an indirect boost to other major currencies, notably USD, GBP, and EUR.
Fifth, despite the recent drop in crude oil prices, inflation risks are not going away. Consumer prices remain stubbornly high worldwide—especially in the Eurozone—keeping pressure on policymakers to maintain elevated interest rates. Furthermore, high consumer prices create political risks as social unrest may erupt over the rising cost of living, undermining government stability and influencing election outcomes.
Sixth is the cash deficit. It may sound strange, but the competition for capital is actually intensifying. Governments need investors' money to cover their huge deficits (U.S. debt alone is $40 trillion; with France, the UK, and Japan, the figure goes to $57 trillion). At the same time, global tech giants have pledged to spend more than $1 trillion on artificial intelligence. This competition for cash is pushing borrowing costs higher and fuelling market volatility.
Key data and events calendar for November
Date | Event | Most affected currencies |
5 November | BoE rate decisions; Norges Bank decision; ECB speeches | GBP and EUR pairs |
6 November | U.S. October nonfarm payrolls; multiple Fed speakers | All—via USD channel |
9 November | BoJ summary of opinion from October meeting | JPY pairs |
15 November | PBoC forex reserve ratio increase takes effect | CNY pairs (also, indirectly—EUR, GBP, and USD) |
17 November | RBA minutes; Hungary and Indonesia rate decisions | AUD pairs |
18 November | FOMC October meeting; APEC Leaders' Meeting (Shenzhen) | All—via USD channel |
19 November | SARB rate decision | ZAR and other African currencies |
25 November | Fed Beige Book | All—via USD channel |
Source: Elev8 broker
Disclaimer:This article does not contain or constitute investment advice or recommendations and does not consider your investment objectives, financial situation, or needs. Any actions taken based on this content are at your sole discretion and risk—Elev8 does not accept any liability for any resulting losses or consequences.
Elev8 is a licensed global broker serving 18+ million traders in 100+ countries. It offers market access through 3 platforms: Elev8Trader, MetaTrader 4, and MetaTrader 5. Operating under licences from Mauritius and Seychelles, Elev8 provides traders with the tools to help spot and capture more market opportunities. The broker received the 'Best Trading Experience Broker 2026' and the 'Best Trading Platform Provider 2026' awards from FxDailyInfo.
One of Elev8's key features is Space, an analytics hub within the Elev8Trader platform that helps traders expand their market horizons. With its personalised feed, daily expert analytics, and community content, Space facilitates faster access to information and market data.
Author

















