DXY rebounds off lows, ends flat; AUD, NZD tumble; Risk-off

Mixed data, lower yields, Fed uncertainty weigh on sentiment
Summary:
The Dollar Index, a popular gauge of the Greenback’s value against a basket of 6 major currencies ended flat at 104.35, after dropping to 104.00, it’s lowest level since September 2023.
A fall in US Inflation numbers earlier this week failed to push the US currency lower after Cleveland Fed President Loretta Mester said that the lower levels of inflation were not enough to convince her that the central bank had won its battle against higher prices.
Claims for Unemployment benefits in the US climbed to 231,000, its highest in three months. The rise in Jobless Claims added to data indicating some cooling in the labor market.
The Aussie (AUD/USD) underperformed, tumbling to 0.6470 (0.6510), following a rise in Australia’s October Unemployment Rate to 3.7% from 3.6%. The Kiwi (NZD/USD) slid to 0.5975 (0.6020).
Sentiment in Asia remained sour on lingering Chinese property concerns. Despite robust Chinese October Retail Sales, Fixed Asset Investment slumped to 2.9% from 3.1% previously. The drop in Chinese total spending (encompassing property) weighed on risk sentiment.
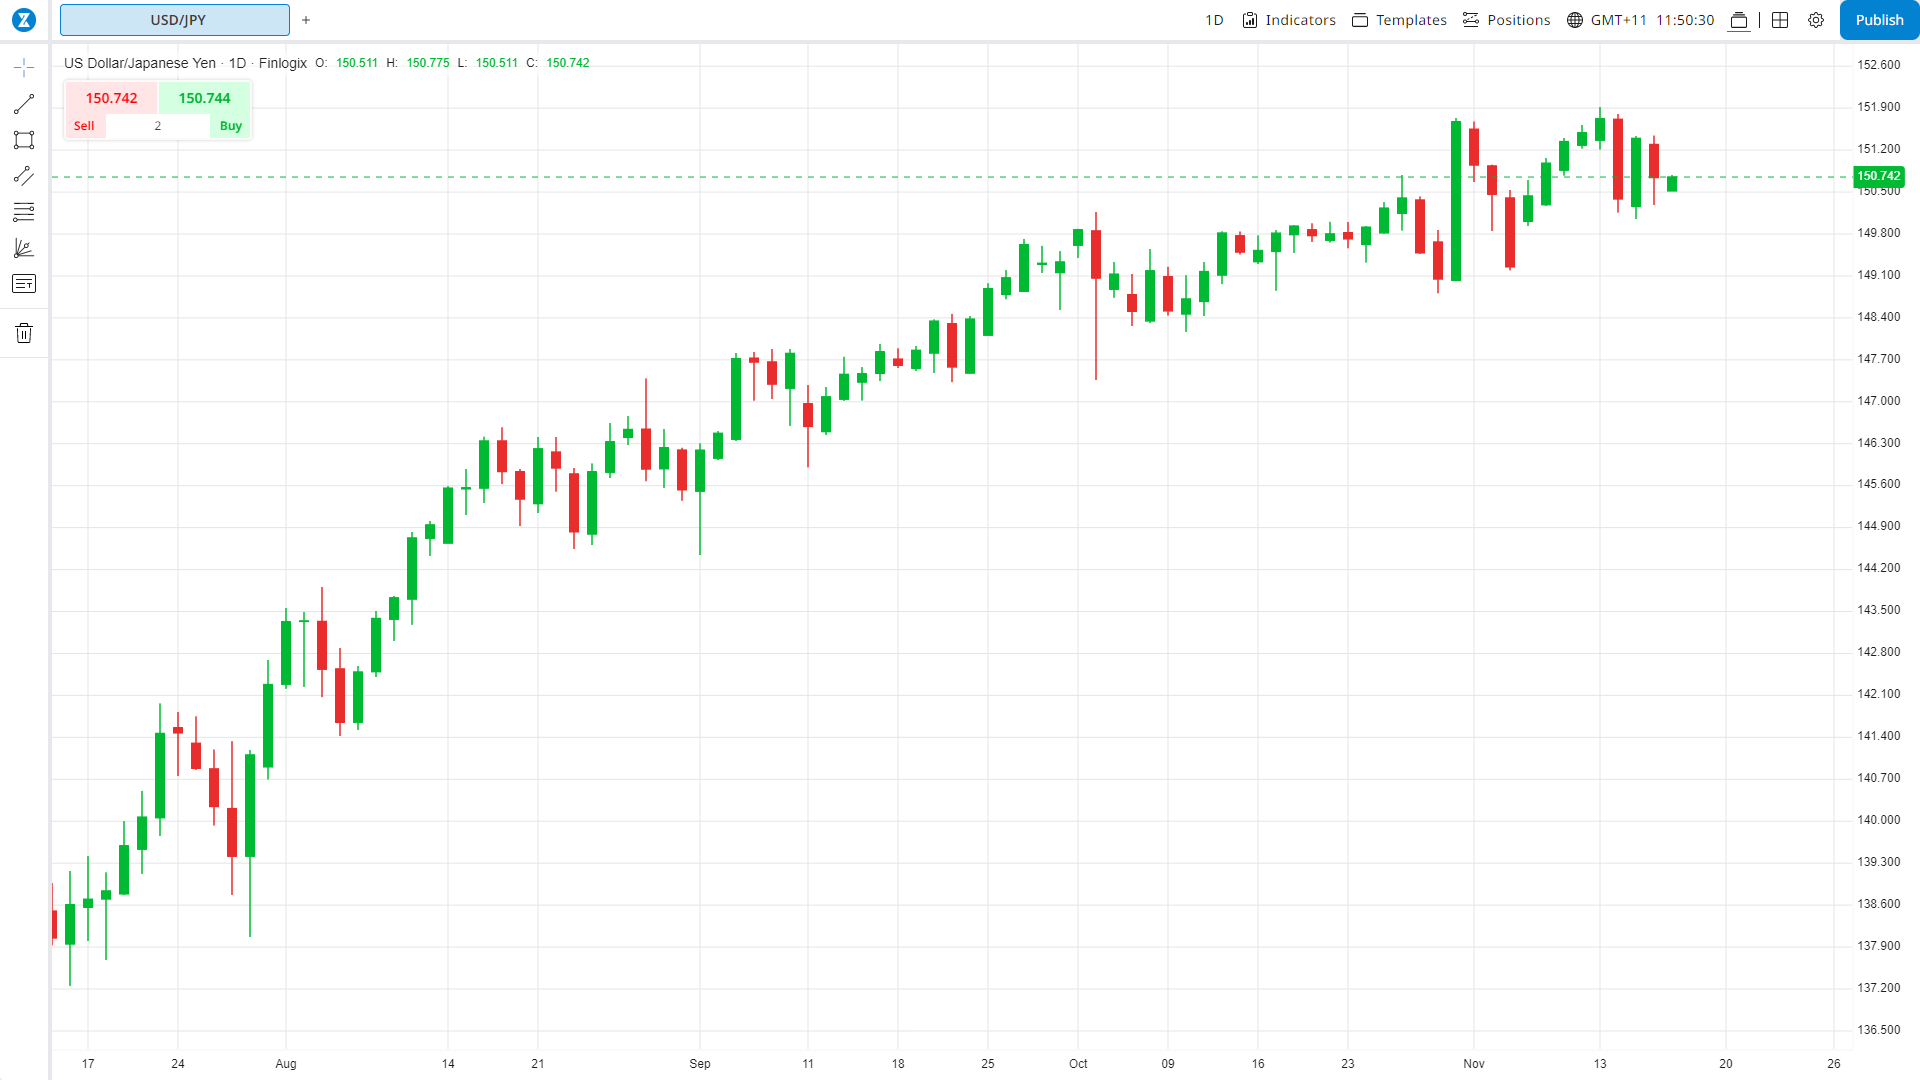
The USD/JPY pair finished at 150.60 after plummeting to an overnight low at 150.29. The Greenback saw a high at 151.43 Yen in choppy conditions. Lower US bond yields weighed on the USD/JPY pair.
The Euro (EUR/USD) steadied to 1.0853 against yesterday’s finish at 1.0835. The shared currency soared to an overnight high at 1.0896 before easing. Sterling (GBP/USD) was little changed at 1.2410.
Global bond yields were lower. The US 10-year treasury bond rate slid to 4.44% (4.53%). Germany’s 10-year Bund yield fell to 2.59% from 2.64%. Japan’s 10-year JGB yield dipped to 0.78% (0.79%).
Wall Street stocks slid. The DOW closed at 34,870 (35,010) while the S&P 500 ended 0.08% lower at 4,503 (4,515). Other global share prices were mixed.
Other economic data released yesterday saw US October Industrial Production (m/m) fall to -0.7% from 0.1% previously and lower than expectations at -0.3%. US Capacity Utilization eased to 78.9% from 79.5% previously. US Manufacturing Production (y/y) fell to -1.7% (-0.9% previously).
- USD/JPY – The Dollar initially soared to an overnight high at 151.43 in volatile trade before easing to 150.60 in late New York. The USD/JPY pair saw an overnight low at 150.29. Japan’s 10-year bond yield finished lower, at 0.78% from 0.87%.
- AUD/USD – The Aussie Battler was pummeled lower to 0.6470 at the close against a previous finish at 0.6510. In choppy trade, the overnight high traded was 0.6517 while the overnight low recorded was at 0.6461. Higher US bond rates also weighed on the Aussie.
- EUR/USD – The shared currency eased to 1.0855 at the close of trade in New York. Earlier, the Euro rallied to 1.0896 before sliding lower. The overnight low traded for the EUR/USD pair was at 1.0896, just below that 1.0900 level.
- GBP/USD – The British Pound finished little-changed at 1.2410 (1.2390). Overnight, the high traded for Sterling was at 1.2456 while the overnight low recorded was at 1.2376. The British currency benefitted from the overall weaker Greenback. UK Retail Sales are due later today.
On the lookout:
Expect more volatility in the markets as we begin the last trading day of this week.
Data releases today kick off with New Zealand’s Q3 PPI Input (f/c -0.6% from -0.2% previously – ACY Finlogix), and New Zealand’s Q3 PPI Output (f/c -0.3% from 0.2% previously – ACY Finlogix).
China follows with its FDI (Foreign Direct Investment), which is forecast at -9.7% from -8.4% - ACY Finlogix).
The UK starts off Europe with its UK October Retail Sales (m/m f/c 0.3% from -0.9%; y/y f/c -1.5% from -1.0% - ACY Finlogix). UK October Core Retail Sales (m/m excluding fuel - f/c 0.4% from -1.0% - ACY Finlogix).
Switzerland follows with its Industrial Production (y/y f/c -1.7% from -0.8% - ACY Finlogix). The Eurozone follows with its Eurozone Final October Inflation Rate (m/m f/c 0.1% from 0.3%; y/y f/c 4.2% from 4.5% - ACY Finlogix).
Canada kicks off North America with its Canadian October PPI report (m/m f/c 0.3% from 0.4%; y/y f/c -1.2% from 0.6% - ACY Finlogix).
The US round up today’s data releases with its October Housing Starts (m/m f/c 1.35 million from 1.358 million; m/m -1.3% from 7% - ACY Finlogix), US Preliminary October Building Permits (1.45 million from 1.471 million; m/m f/c -1.5% from -4.5% - ACY Finlogix).
US Federal Reserve Heads, Daly and Collins are due to speak at various events.
Trading perspective:
Following two weeks of absence from the markets, this writer has seen the Dollar Index slide from the mid 106 level to the lower 104 levels.
A fall in US CPI and PPI data indicated that inflationary pressures were finally easing.
The strong rise in US Claims for Unemployment Benefits to 3-month highs reinforced the belief that the Fed has completed its monetary tightening cycle.
The Dollar Index rebounded off its lows supported by the market’s risk-off stance.
Expect the Greenback to remain supported today, albeit within wide trading ranges due to heightened volatility. Which is a bonus for FX traders.
- USD/JPY – Having just come from a 2-week holiday in Japan, the one thing that stood out was the rise in visiting tourists. The weak Yen is a bonus for the tourists. What this suggests for traders is that the buying of the Japanese currency will keep the USD/JPY topside limited to the 152-155 level. Today, immediate support lies at 150.30, 150.00 and 149.70. Immediate resistance can be found at 151.00, 151.40 and 151.80. Look for more choppy trade likely between 150.00-151.50. Prefer to sell USD/JPY rallies.
Source: Finlogix.com
- AUD/USD – The Aussie Dollar remained under pressure, tumbling to 0.6470 (0.6520) due to risk-off and broad-based US Dollar strength. Today, look for immediate support at 0.6450 (overnight low traded was 0.6460). The next support level lies at 0.6420. On the topside immediate resistance is found at 0.6500, 0.6540 and 0.6580. Look for more choppy trade, likely between 0.6430-0.6530. Trade the range.
- EUR/USD – The Euro steadied to 1.0855 in late New York from 1.0835. Immediate resistance today in the shared currency lies at 1.0885 followed by 1.0905. On the downside look for immediate support at 1.0830 (overnight low) followed by 1.0800 and 1.0770. Look for the Euro to consolidate in a likely range today of 1.0820-1.0920. Trade the range today.
- GBP/USD – Sterling dipped to 1.2410 in late New York after trading to a high at 1.2450 overnight. The British currency saw an overnight low at 1.2376. Today look for immediate resistance at 1.2430, 1.2460 and 1.2500. Immediate support lies at 1.2375 followed by 1.2345 and 1.2315. Look for more choppy trade in this currency pair, likely between 1.2375-1.2475. Trade the range in this puppy as well… nice and wide.
Happy Friday and trading all, its good to be back. A top weekend too.
Author

Michael Moran
ACY Securities
Michael has over 40 years’ FX experience, including running FX trading desks for some of the largest banks in the world.
















