Did Yellen signal the Fed is worried about overheating?

Treasury secretary Janet Yellen said rates might have to rise to cool an overheating economy. Shock, horror. Did no one give her Powell’s script? “It may be that interest rates will have to rise somewhat to make sure that our economy doesn’t overheat,” Yellen said during an economic forum at The Atlantic. “Even though the additional spending is relatively small relative to the size of the economy, it could cause some very modest increases in interest rates.”
Economics 101 shouldn’t offend markets or perturb investors – stocks hit session lows off the back of the remarks. But this was seen as a significant remark since it is a break with the Fed’s new policy stance. Now what she’s saying is demonstrably true: central banks raise rates to stop economies from ‘overheating’, since this tends to lead to bad things like inflation and misallocation of capital. It’s the kind of thing central bankers would normally say in normal times to signal a tightening cycle is imminent. But we are not in normal times and the Fed has been hammering its message home that its goal is not to quell forecast inflation, but to get back to full employment come-what-may. Some will flag the potential incursion into monetary policy by the Treasury as big no, but in this instance it’s not about central bank independence – Yellen is far too well versed in this topic and far too academic in her approach to be trying to strong arm the Fed.
But it’s very much the antithesis of the way the Fed has been playing things since the pandemic. We’ve all kind of assumed the Fed is happy to let the economy run hot, because it’s implicitly said so: employment is the goal, inflation can be overlooked until enough people have jobs. Now many of us have questioned the sustainability of such a pivot in policy and break with the traditional central bank approach, which has always been to remove the punch bowl before the party got out of hand (overheating). But we’ve assumed that the Fed was so all-in it wouldn’t change course.
Of course, Janet Yellen is no longer ‘the Fed’. That’s now Jay Powell’s purview. Her comments - seen in isolation - are just the same in reverse as Mario Draghi’s persistent calls for economic, structural and fiscal reform in the EU. But she was the Fed chair so her words carry weight. Moreover, Yellen and Powell have been singing from the hymn sheet - they’re not at odds on this, which could lead some to think it’s part of the ‘masterplan’.
So, the question for market watchers is whether what the Treasury says about monetary policy is all that important. Yellen looks more like an interested outsider than a Fed mole. I don’t think it was choreographed to signal a Fed taper. I think it was a genuinely held belief that multi-trillion-dollar stimulus and infrastructure spending coming at a time of a major cyclical recovery and zero percent interest rates could lead the US economy to get a bit warm. Coming from a central bank background, it’s natural for her to think that ‘well we need to spend this money now, so rates might need to go up to compensate for all this extra money we’re printing at a later date’. It’s not, in my view, scripted policy manoeuvring. Just sensible observation – the Fed could do with this.
Indeed, Yellen later made these comments at the Wall Street Journal’s CEO Council Summit: “It’s not something I’m predicting or recommending … If anybody appreciates the independence of the Fed, I think that person is me, and I note that the Fed can be counted on to do whatever is necessary to achieve their dual mandate objectives.”
Market reaction? Rates were unmoved, with the benchmark US 10-year still nestled around 1.60% but richly priced tech stocks fell, leaving the Nasdaq down almost 2%, which would imply that rates might not be moving at the short end (I.e. her comments are not a taper signal), but investors do think cyclical and value areas of the market warrant more attention (rotation). If anything has been clear about the last few months, it’s that some corners of the market that have been overlooked by investors are gaining more kerb appeal as inflation expectations and nominal yields pick up. Yellen’s comments only further underline this trend. The S&P 500 wiped out Monday’s gains, sliding 0.7%. The DAX fell sharply but is up this morning as European markets stage a fightback. The FTSE 100 trades up 1% and making a fist of 7,000 again after pulling back from the 7040 area yesterday to finish well south of 7,000.
Where are stocks headed? We spend a tonne of time chatting about what signals central banks are sending and what vaccines might or might not do for the economy. But all you lot really want to know is where the market is going to be in a week, a month, six months maybe tops.
So given it’s early May and the market is permeated with a sense of trepidation as traders really do take one eye of their screens as summer approaches, now’s as good a time as any to look at the prospects for the broader stock market in the coming months.
The old ‘sell in May’ adage is doing the rounds of course. On seasonality, Stifel says: “We see the S&P 500 flat/down -5-10% May 1st to Oct-31st, 2021: Seasonality is especially applicable at this moment in time". And Bank of America notes that the May-October period has the lowest average and median returns of any equivalent six-month period, looking at data going back to 1928. Maybe there is something in the ‘sell in May’ trope. Certainly, given the run-up in equities we have seen, the well understood macro picture and the propensity for yields to edge higher, a period of cooling off seems reasonable.
Earnings are powering ahead – we're just entering the last stretch of a blowout quarter in both the US and Europe. But this has been largely priced. Can corporates keep up the pace? The second quarter is meant to be even better – stimulus cheques are back, and GDP growth is seen powering ahead. Markets may not truly reflect just how strong this recovery will be. According to the Atlanta Fed Q2 growth is seen at 13.2% and the US economy will exceed its pre-pandemic peak before the quarter is over (as it should when you have pumped something like 20%-30% of GDP into the economy by way of fiscal stimulus and emergency relief packages). The money supply has ballooned; now is the time for the velocity of money to recover. We should be careful; we are already seeing some heinous year-on-year chart crime as economies recover.
Spending seems to be strong as the reopening of the global economy, but companies are experiencing supply chain problems and raw material shortages. This ought to push up inflation, raising nominal bond yields (though not necessarily real rates), which could hinder equity market returns over the coming months.
What about sentiment? Clearly investors are very bullish right now – they’re pretty well ‘all in’. BoA notes that Wall Street bullishness is at a post Financial Crisis high. "We have found Wall Street’s bullishness on stocks to be a reliable contrarian indicator. The current level is 50bp away from triggering a contrarian “Sell” signal,” they write.
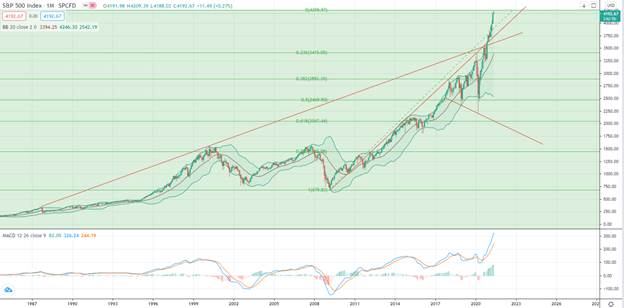
And the technicals? In short, the S&P 500 appears very over-extended at current levels and a retrace of around 400pts to 3,800 would be considered as the first stop in multi-month reversion to more sustainable levels. The Vix does not suggest market participants are overly concerned and some are making big bets on markets remaining tranquil for the next few months.
Valuations are harder to get a handle on – the Case Shiller PE ratio is at 37, its highest since the dotcom boom - indeed it has only ever been this high during that period of ebullience and irrational exuberance. But given the rebound in the economy and earnings taking place and expected to continue, this backwards-looking metric is probably less reliable now than at other times (the Fed has already made somewhat outdated as a gauge of stress in the market). Forward multiples are less exaggerated – about x22 the next 12 months earnings. This is still relatively high but until the Fed removes the punchbowl, it can be sustained. Margin debt has exploded, suggestive of a large amount of leverage in stock markets that could be exposed to a sharp correction, making a pullback self-sustaining.
Should you worry? A lot depends on monetary policy reaction function. In other words, how do central banks respond to changing economic circumstances. More simply, when does the Fed remove the punchbowl? To be even more precise, at what point does the Fed start to signal it might start thinking about turning the music off. Yellen may have fired the starting pistol, but I now think Powell and co will work hard to row that back and reiterate their commitment to employment goals – I don’t think that has changed.
It’s like a game of musical chairs where everyone has worked out that it’s better to rush for a seat when the compere is looking like he might press stop than wait until the music actually finishes. US economic growth and spending this year could be even stronger than expected – this could push the Fed to tighten policy sooner than markets expect - or as we might surmise from Yellen’s remarks, the fiscal impetus could force the Fed to move sooner than it thinks it needs to. But only if employment recovers to pre-pandemic levels. If it does not, the Fed could keep administering kool aid for longer. Inflation remains the big unknown and has the potential to derail growth. Either way, yields should tend to move higher over the summer as data comes in, this could drive up rates and hurt equities even if it also means a weaker dollar as real rates in Europe move up.
Author

Neil Wilson
Markets.com
Neil is the chief market analyst for Markets.com, covering a broad range of topics across FX, equities and commodities. He joined in 2018 after two years working as senior market analyst for ETX Capital.

















