Australian Dollar Price Forecast: Initial support comes near 0.7070
- AUD/USD picks up some renewed upside traction, back above 0.7100.
- The US Dollar faces some profit-taking as markets digest the Fed’s hike.
- Next on tap in the Asia-Pacific region will be the BoJ’s meeting.
The Australian Dollar (AUD) follows the rest of its risk-linked peers and manages to regain part of the ground lost in the last three days, with AUD/USD reclaiming the key 0.7100 hurdle a tad beyond on Thursday.
Indeed, spot sets aside three consecutive daily retracements, gathering fresh impulse on the back of the generalised albeit modest knee-jerk in the US Dollar (USD), as market participants keep digesting Wednesday’s hawkish hike by the Federal Reserve (Fed).
Meanwhile, the ongoing correction in AUD/USD seems to have met some decent contention in the 0.7080-0.7070 band, a region also underpinned by the 61.8% Fibo retracement of the July-September rally.
Looking at the broader picture, however, the pair’s current positive stance still appears propped up by the Reserve Bank of Australia’s (RBA) hawkish policy bias and elevated inflation in Oz.
Australia’s data point to slower but resilient growth
Australia’s economy continues to compare favourably with many of its G10 peers, supported by domestic demand and positive economic growth. Persistent inflation also supports the RBA’s cautious, data-dependent policy stance.
Business activity remained in expansionary territory in August after final Purchasing Managers’ Index (PMI) readings showed the Manufacturing index unchanged at 52.0, while the Services index edged a tad down to 53.2.
Trade data provided another positive signal: Australia recorded an A$1.923 billion surplus in July, adding to the A$2.341 billion surplus registered in June.
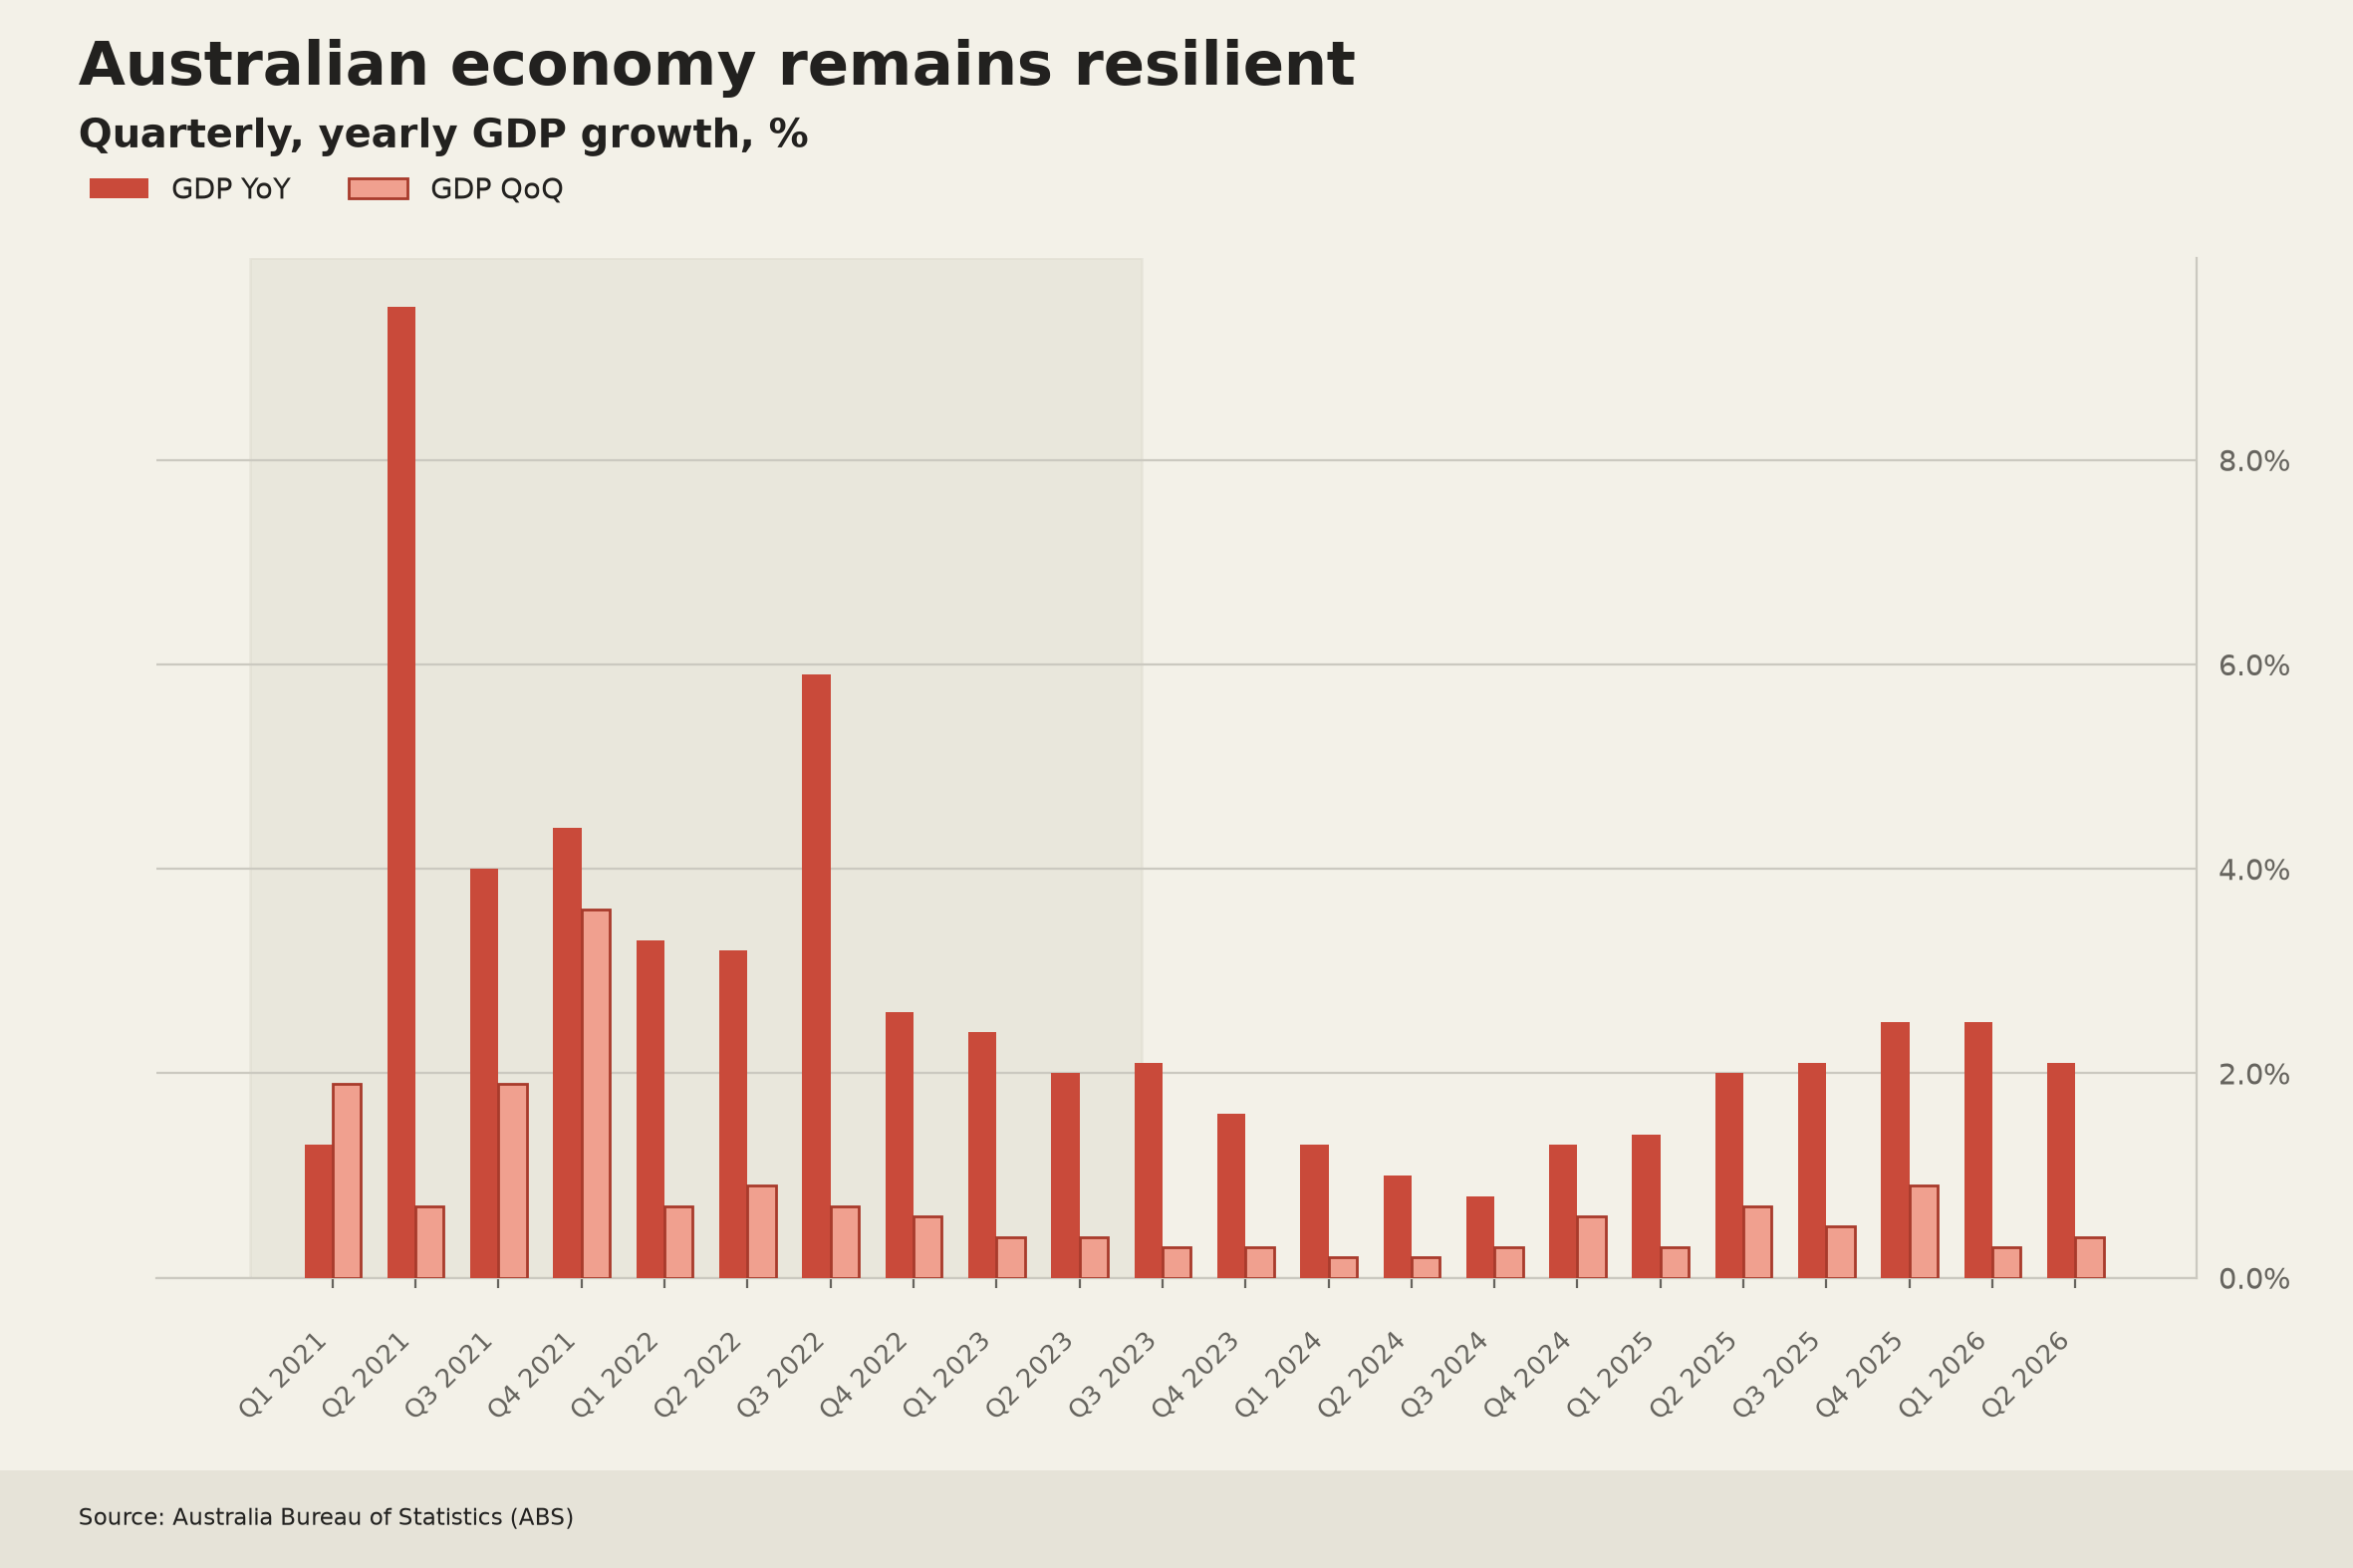
Growth figures were less encouraging, however. Indeed, the Gross Domestic Product (GDP) expanded by 0.4% QoQ in the second quarter of 2026, up from 0.3%, while annual growth came in at 2.1%, down from the previous 2.5% yearly expansion.
The labour market also showed signs of losing momentum in July. The Unemployment Rate rose to 4.5%, while Employment Change declined by 15.8K following a revised increase of 80.3K in the previous month.
Inflation remains the main constraint after July data showed price pressures running well above the RBA’s 2%-3% target band, suggesting that the return to target could remain uneven and prolonged. That said, the headline inflation eased to 3.5% in July (from 3.8%), while underlying price pressures tracked by the Trimmed Mean held steady at 3.6%.
The Melbourne Institute’s Consumer Inflation Expectations measure reinforced that view, holding steady at 4.9% in September.
The figures leave the RBA’s inflation task incomplete. Policymakers expect inflation to return to target only in early 2028, keeping the emphasis on patience rather than an imminent policy pivot.
China stabilises but fails to add momentum
China is providing stability for the Australian economy, but not the growth impulse that has supported the Australian Dollar during previous expansions.
The Chinese economy grew by 4.3% YoY in the April-June period, while Industrial Production growth regained traction, expanding by 5.2% YTD, and the trade surplus widened to $119.1 billion in July, supported by decent increases in both imports and exports. However, on the downside, consumer spending remained sluggish after Retail Sales rose by only 0.4 % from a year earlier.
In addition, business surveys presented a mixed picture: the National Bureau of Statistics reported that the Manufacturing PMI improved to 49.8 in August from 49.2, while the Services PMI remained unchanged at 49.0. On the other hand, private measures like RatingDog remain in expansionary territory, with Manufacturing at 51.5 (from 50.9) and Services at 51.4 (from 50.4).
Disinflationary pressures seem to have taken a breather in August, with the CPI gaining 0.8% YoY, up from 0.5%, while prices rose by 0.4% on a monthly basis. Producer Prices rose by 3.8% over the previous twelve months, down from the 3.5% increase recorded in the previous month.
The People’s Bank of China (PBoC) left its Loan Prime Rates unchanged at its latest event, maintaining the one-year rate at 3.00% and the five-year rate at 3.50%.
China is therefore neither providing a major boost nor creating a significant drag. Unless the data reveal a clearer acceleration or deterioration, its influence on AUD/USD is likely to remain limited.
RBA retains a tightening bias
The RBA left its Official Cash Rate (OCR) unchanged on August 11 and retained a clear tightening bias, citing above-target inflation and upside risks to the outlook. The decision to hold rates was unanimous.
The Minutes maintained that cautious but hawkish stance. Several officials warned that inflation risks could materialise, which would leave the Board prepared to raise rates. Potential sources of pressure include increased investment in data centres, cost pass-through and higher energy prices.
Policymakers discussed a 25-basis-point increase but concluded that the current policy setting was sufficiently restrictive. They also acknowledged more balanced risks, including falling house prices and the possibility that inflation could decline without causing significant damage to employment.
Fresh GDP, labour-market and inflation figures were expected before the September meeting, leaving policy dependent on the incoming data.
Markets are pencilling in roughly 37 basis points of tightening by year-end and expect the RBA to hike the OCR by 25 basis points at its September 29 meeting.
AUD/USD outlook hinges on 0.7200
Base case
The medium-term outlook remains tilted towards further gains, as long as AUD/USD stays above its 200-day Simple Moving Average (SMA), which is currently around 0.7010.
Further progress will still require a quite strong catalyst: without a sustained improvement in risk appetite or continued US Dollar weakness, upward momentum could begin to fade.
Bull case
A stronger risk-on environment and a convincing break above 0.7200 would bring the 2026 high near 0.7280 into view.
Beyond that level, resistance emerges at the 0.7300 round level, followed by the 2022 ceiling at 0.7593.
Bear case
A deterioration in global risk sentiment, renewed strength in the Greenback or further weakness in Chinese data could spark fresh selling interest in spot.
Initial support is located at the September floor at 0.7074 (September 16), seconded by the provisional 55-day SMA near 0.7070. The more important level remains the 200-day SMA.
However, a breach below that area would weaken the broader constructive structure and increase the risk of a deeper short-term decline.
Shorts retreat; conviction cracks
According to the Commodity Futures Trading Commission (CFTC), AUD bearish positioning eased further in the week ending September 8. Indeed, net speculative positioning improved by around 4.5K contracts, reaching nearly 35K contracts. Furthermore, the 4-week change increased by more than 4.3K contracts, signalling a clear improvement in short-term momentum.
Open interest also surged sharply, up nearly 63.8K contracts to about 455.5K contracts, a rise of about 16%. The move points to a combination of short covering and new long exposure rather than a simple pullback from the market, with net shorts declining even as participation grew.
Speculative exposure improved to -7.7%, though its percentile moved up to 84.2. This means that bearish AUD exposure remains historically elevated even with the recent improvement. The net-position percentile also rose to 72.4, indicating that positioning is becoming less bearish but is not yet close to neutral.
Overall, the Aussie’s bearish bias is losing impulse, and the sharp rise in open interest strengthens the significance of the latest improvement. However, the elevated exposure percentile shows that short positions remain substantial. For now, the data point to an ongoing unwinding of bearish conviction rather than a fully confirmed bullish reversal.
What's next for the Aussie
US Dollar dynamics, global risk sentiment and geopolitical developments remain the main near-term drivers of AUD/USD.
Meanwhile, next on tap on the domestic docket will be the release of the preliminary S&P Global PMIs on September 23, which should add further details on how the domestic business activity fared this month. In addition, the Bank of Japan (BoJ) meets tomorrow, and markets should closely watch the bank’s decision on its interest rate for its impact on the carry trade environment (via AUD/JPY).
Beyond the immediate releases, the main risks include a sharper slowdown in China, a persistently cautious Fed, a deterioration in investor risk appetite or a change in the RBA’s current policy stance. Any of these developments could quickly alter the outlook for the Australian Dollar.
Technical levels to watch
In the daily chart, AUD/USD trades at 0.7113, holding a bullish near-term bias as spot remains above the 55-day, 100-day and 200-day simple moving averages (SMAs) clustered between 0.7068 and 0.7010. The Relative Strength Index (14) at 46.1 has eased back toward neutral territory, while the Average Directional Index near 22 suggests a moderately directional but not explosive trend, hinting that upside progress may be gradual rather than impulsive.
On the downside, immediate support is seen at the 100-day SMA and nearby horizontal level around 0.7079, followed by the 55-day SMA at 0.7068 and the longer-term 200-day SMA at 0.7010, before a deeper structural floor emerges at 0.6833. On the topside, AUD/USD faces initial resistance at 0.7278 and 0.7283, with a more distant barrier at 0.7661, where a break would open the way for a broader bullish extension.
(The technical analysis of this story was written with the help of an AI tool. Know more.)
External risks make further gains harder to sustain
The broader picture continues to favour the AUD.
Australia’s domestic backdrop compares favourably with that of many advanced economies, and the RBA is in no hurry to abandon its hawkish stance.
The recovery nevertheless remains vulnerable to renewed strength in the Greenback, persistent geopolitical uncertainty and a Chinese economy that is stabilising rather than accelerating.
The 200-day SMA remains the key level for the medium-term outlook. Holding above it preserves the constructive structure, but a convincing break above 0.7200 will probably This would require a more convincing sell-off of the Greenback, stronger demand for risk-sensitive assets, additional cooling in US inflation, or a (less likely) dovish shift from the Fed.
Until then, external forces are likely to exert more influence over the Australian Dollar than domestic fundamentals.
Author

Pablo Piovano
FXStreet
Born and bred in Argentina, Pablo has been carrying on with his passion for FX markets and trading since his first college years.
















