Asia open: Havens light up, crude pops, but panic button stays untouched
The futures board opened like a gunshot in a marble corridor—sharp, echoing, but not exactly chaotic. E-minis took a 1% stumble out of the gate, shedding 60 handles before traders blinked, but found their footing and tentatively started buying the dip. The scent of panic? Nowhere. This isn’t capitulation—this is the kind of cautious recalibration you get when everyone’s waiting for Act II.
Oil? It did what oil always does when the Middle East tinderbox starts to smoulder—spiked on the B-2 "bombs away" headline, then recoiled. The initial bid was pure reflex—machines chasing healing risk premium—but the fade was classic crude: traders ran the tape, priced the probabilities, and realized Tehran hadn't closed the gates of Hormuz just yet. The chart looked less like breakout territory and more like a classic range trade — hot air above $79, with gravity pulling back toward $77.
Gold, the perennial panic proxy, didn’t flinch—it surged like a paranoid prepper at a flash sale, sniffing last week's highs as geopolitical risk finally gave the yellow metal a real reason to stretch. War drums always grab Gold’s attention, and this weekend’s B-2 strike was a clarion call, yet that bounce is also fading, with risk stabilizing around the thought that Iran’s war-mongering response rhetoric is more bark than bite.
As for yen?, Japan’s oil dependence, coupled with a fiscal hangover equivalent to 200% of GDP, isn’t precisely the safe haven anyone dreams of amid a potential Middle East conflict that could erupt into an oil shock. The yen is no longer a safe haven hedge—it's a liability masquerading as a refuge. In a world where energy insecurity is the new inflation accelerant, nobody is rushing to park cash in a currency that looks one BOJ misstep away from a reverse split.
The dollar tried to flex—classic risk-off muscle memory—but once again, the move lacked conviction. That’s the tell. The greenback’s crown as the world’s untouchable safe-haven is slipping, tarnished by fiscal sprawl and Washington gridlock. It’s still the cleanest shirt in the dirty laundry basket when oil shocks hit—but in their absence, the shine fades fast. Traders aren’t chasing strength—they’re fading the dollar pops and loading up on EUR/USD as if it were discounted volatility ahead of the next event risk, yet another reminder that the greenback’s safe-haven lustre is more smudged than it used to be.
And Iran? Let’s not sugarcoat it—Washington crossed a geopolitical Rubicon this weekend. It wasn’t just a pinprick strike—it was a signal. But markets, ever skeptical, are still waiting for Tehran’s next geopolitical chess move. A full-blown retaliation on U.S. assets would flip the entire cross-asset calculus. And if Tehran reaches for the Hormuz chokepoint—that’s not just a move, it’s the queen’s gambit. A closure would choke off nearly a third of global seaborne oil. $90 crude would be the appetizer; $120 isn’t out of the question, and then the dollar rips higher.
Geopolitics isn’t macro—it doesn’t rely on models, it hinges on "what-ifs." Every trader knows the oil spike was textbook, but the retracement is equally significant. This isn’t about pricing in the bombs—it’s about incorporating odds on the unpredictable blowback.
The odds of a Strait of Hormuz closure on Polymarket are at 31%.
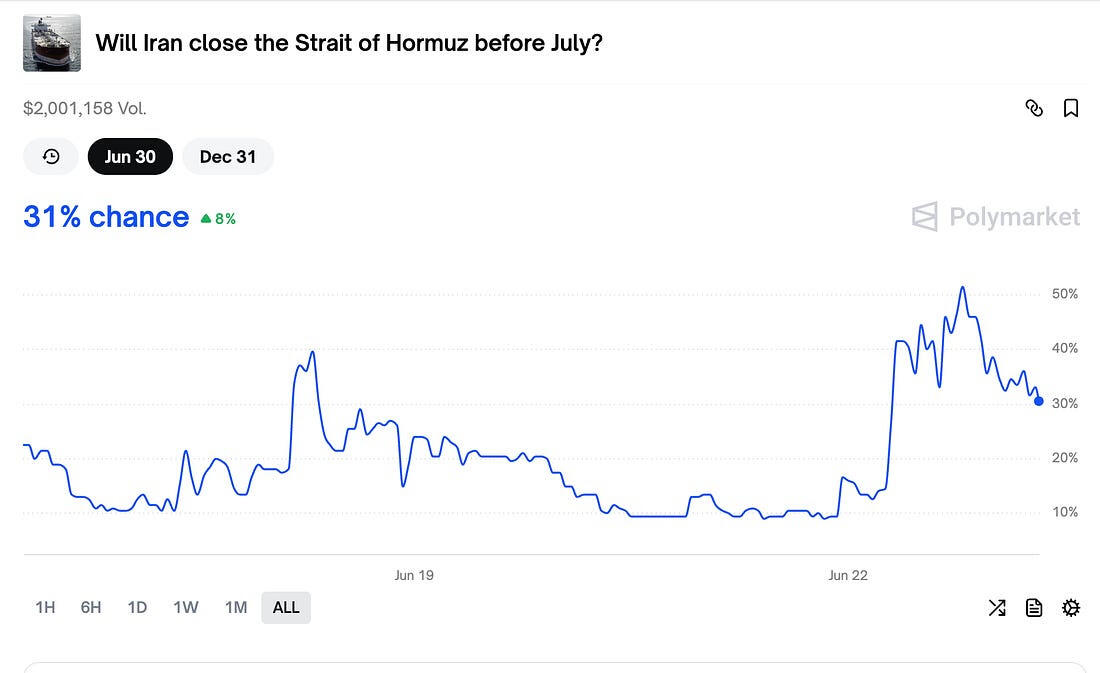
Does Iran dare risk its economic lifeline? Do they push China, the world’s biggest importer, into an energy panic? Do they trigger backlash from Gulf states, already running on fiscal fumes, that can’t easily export seaborne crude? Blocking the Strait causes oil prices to soar—but it won’t shake a shale-rich, energy-independent U.S. nearly as much as it disrupts Asia and Europe, which are not involved in the conflict.
Until the next war-torn escalation headline, we’re in the fog-of-war zone—where futures chop, oil simmers, gold eyes the blast radius, and the dollar sniffs around for traction amid global oil price vulnerabilities. One misstep from Tehran, and this market will reprice everything once again; hence, traders will likely remain in oil market tail risk hedges until a peace pipe starts making the rounds.
Author

Stephen Innes
SPI Asset Management
With more than 25 years of experience, Stephen has a deep-seated knowledge of G10 and Asian currency markets as well as precious metal and oil markets.

















