USD/CHF Price Forecast: Bearish flag keeps 0.8145 in focus
- USD/CHF maintains a bullish sequence of higher highs and lows.
- Flat RSI warns buyers against chasing bearish-flag resistance.
- Break above 0.8145 exposes 0.8200 and 0.8215 next.
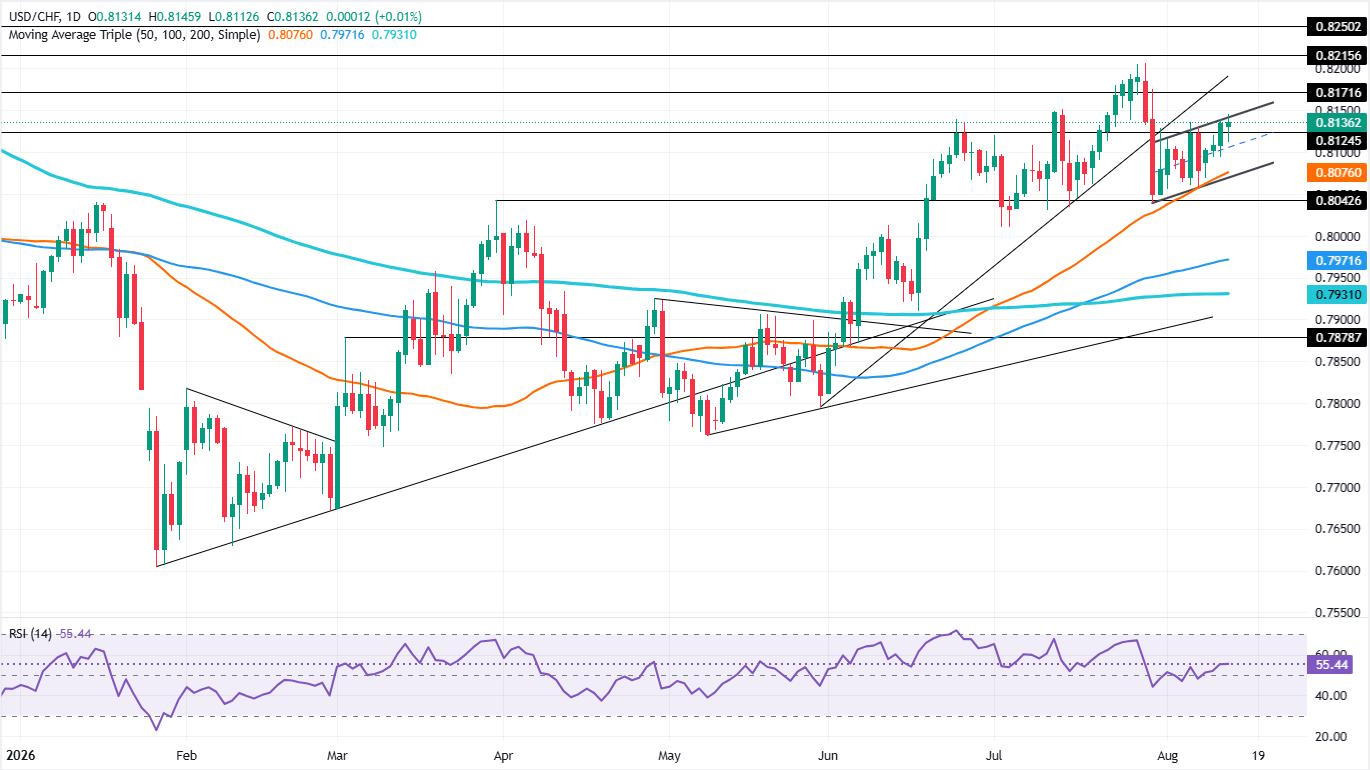
The USD/CHF pair trades near the top trendline of a bearish flag pattern on Thursday, holding steady at around 0.8134 after the release of softer inflation data on the producer side.
USD/CHF Price Forecast: Technical outlook
Price action shows that the bullish market structure of successive higher highs and higher lows remains intact, suggesting further upside. However, momentum flattened despite bullish conditions, as indicated by the Relative Strength Index (RSI). This suggests that buyers need to be cautious about a potential pullback if USD/CHF tumbles below 0.8000.
For a bullish continuation, the pair must clear the top trendline of the bearish flag near 0.8140/45 before launching an attack towards 0.8200. Once those levels are surpassed, the next stop is the June 19, 2025, daily high at 0.8215, followed by the June 4, 2025, peak at 0.8250.
Downwards, the first support is the August 12 low of the day at 0.8094. Once surpassed, it opens the door towards the 50-day Simple Moving Average (SMA) at 0.8076.
USD/CHF Price Chart – Daily
(This story was corrected on August 13 at 19:43 GMT to say that USD/CHF trades near 0.8134, not 0.8034.)
Swiss Franc FAQs
The Swiss Franc (CHF) is Switzerland’s official currency. It is among the top ten most traded currencies globally, reaching volumes that well exceed the size of the Swiss economy. Its value is determined by the broad market sentiment, the country’s economic health or action taken by the Swiss National Bank (SNB), among other factors. Between 2011 and 2015, the Swiss Franc was pegged to the Euro (EUR). The peg was abruptly removed, resulting in a more than 20% increase in the Franc’s value, causing a turmoil in markets. Even though the peg isn’t in force anymore, CHF fortunes tend to be highly correlated with the Euro ones due to the high dependency of the Swiss economy on the neighboring Eurozone.
The Swiss Franc (CHF) is considered a safe-haven asset, or a currency that investors tend to buy in times of market stress. This is due to the perceived status of Switzerland in the world: a stable economy, a strong export sector, big central bank reserves or a longstanding political stance towards neutrality in global conflicts make the country’s currency a good choice for investors fleeing from risks. Turbulent times are likely to strengthen CHF value against other currencies that are seen as more risky to invest in.
The Swiss National Bank (SNB) meets four times a year – once every quarter, less than other major central banks – to decide on monetary policy. The bank aims for an annual inflation rate of less than 2%. When inflation is above target or forecasted to be above target in the foreseeable future, the bank will attempt to tame price growth by raising its policy rate. Higher interest rates are generally positive for the Swiss Franc (CHF) as they lead to higher yields, making the country a more attractive place for investors. On the contrary, lower interest rates tend to weaken CHF.
Macroeconomic data releases in Switzerland are key to assessing the state of the economy and can impact the Swiss Franc’s (CHF) valuation. The Swiss economy is broadly stable, but any sudden change in economic growth, inflation, current account or the central bank’s currency reserves have the potential to trigger moves in CHF. Generally, high economic growth, low unemployment and high confidence are good for CHF. Conversely, if economic data points to weakening momentum, CHF is likely to depreciate.
As a small and open economy, Switzerland is heavily dependent on the health of the neighboring Eurozone economies. The broader European Union is Switzerland’s main economic partner and a key political ally, so macroeconomic and monetary policy stability in the Eurozone is essential for Switzerland and, thus, for the Swiss Franc (CHF). With such dependency, some models suggest that the correlation between the fortunes of the Euro (EUR) and the CHF is more than 90%, or close to perfect.
Author

Christian Borjon Valencia
FXStreet
Markets analyst, news editor, and trading instructor with over 14 years of experience across FX, commodities, US equity indices, and global macro markets.
















