US Dollar Index remains bid and targets 100.00 ahead of FOMC Minutes
- DXY extends the rally further and clinches fresh tops around 99.75.
- US yields accelerate the upside after Brainard’s comments on Tuesday.
- MBA Mortgage Applications, Fed’s Harker. FOMC Minutes next on tap.

The US Dollar Index (DXY), which gauges the greenback vs. a bundle of its main rival currencies, extend the upside momentum to fresh cycle tops around 99.75 on Wednesday.
US Dollar Index stronger on Fed speculation, looks to 100.00
The index advances for the fifth consecutive session and navigates in levels last seen nearly three years ago in the 99.70 region as market participants continue to digest the recent (and surprising) hawkish comments from FOMC’s L.Brainard on Wednesday, when she advocated for a faster reduction of the Fed’s balance sheet as well as a tighter rate path.
Brainard’s comments lifted US yields to levels last seen in Q1 2019 in the short end and the belly of the curve, while the long end climbed to new 33-month highs.
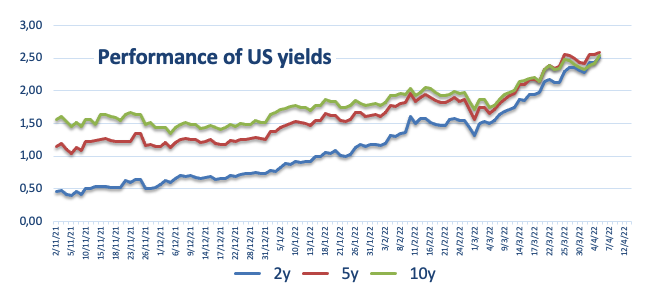
Extra wings to the buck come in the form of the prevailing uncertainty in the geopolitical landscape and the utter absence of progress in the Russia-Ukraine peace talks as well as the US-EU plans to impose extra sanctions against Moscow.
Later in the NA session, the usual weekly MBA Mortgage Applications are due seconded by the speech by Philly Fed P.Harker (2023 voter, hawkish), while the publication of the FOMC Minutes will close the daily calendar.
What to look for around USD
The dollar remains bid and gradually approaches the psychological 100.00 barrier. So far, the near-term price action in the greenback continues to be dictated by geopolitics, while the case for a stronger dollar remains well propped up by the current elevated inflation narrative, a potential more aggressive tightening stance from the Fed, higher US yields and the solid performance of the US economy.
Key events in the US this week: MBA Mortgage Applications, FOMC Minutes (Wednesday) – Initial Claims, Consumer Credit Change (Thursday) – Wholesale Inventories (Friday).
Eminent issues on the back boiler: Escalating geopolitical effervescence vs. Russia and China. Fed’s rate path this year. US-China trade conflict. Future of Biden’s Build Back Better plan.
US Dollar Index relevant levels
Now, the index is gaining 0.10% 99 57 and a break above 99.75 (2022 high April 6) would open the door to 100.00 (psychological level) and finally 100.55 (monthly high May 14 2020). On the other hand, the next support comes at 97.68 (weekly low March 30) seconded by 97.31 (55-day SMA) and then 96.74 (100-day SMA).
Author

Pablo Piovano
FXStreet
Born and bred in Argentina, Pablo has been carrying on with his passion for FX markets and trading since his first college years.
















