US Dollar Index loses upside traction, back to 96.20
- DXY gives away some gains near 96.20 on Tuesday.
- The Russia-Ukraine standoff remains in the centre of the debate.
- Producer Prices, NY Empire State Index, TIC Flows next on tap.

The US Dollar Index (DXY), which gauges the greenback vs. a bundle of its main competitors, seems to be taking a breather around the 96.20 area on turnaround Tuesday.
US Dollar Index looks to geopolitics
The index eases some ground and fades Monday’s uptick to multi-day highs in the 96.40/45 band. Indeed, rising geopolitical tensions stemming from the Russia-Ukraine conflict coupled with supportive Fedspeak lent extra legs to the dollar’s rebound at the beginning of the week.
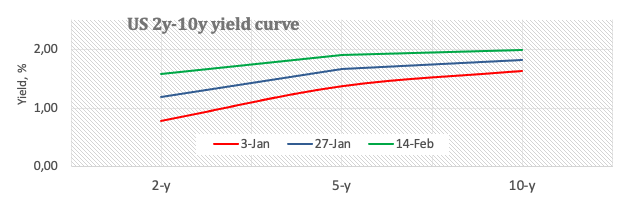
Higher yields, in the meantime, also followed another bout of hawkish rhetoric from St. Louis Fed J.Bullard, who reiterated his preference for a full percentage point of interest rate hikes already by July. On this, and according to CME Group’s FedWatch Tool, the probability of a 50 bps rate hike at the March 16 meeting is close to 60%, up from nearly 30% just a week ago.
In the US data space, January Producer Prices will take centre stage later in the NA session seconded by the NY Empire State Index and TIC Flows for the month of December.
What to look for around USD
The upside momentum in the greenback remains sustained by geopolitics, higher yields and prospects of Fed tightening as soon as in March. However, the extent and duration of this improvement in the dollar remains to be seen, as much of the current elevated inflation narrative was already priced in by market participants as well as the probability (bigger now) of a 50 bps rate hike by the Fed (instead of the more conventional 25 bps move). Looking at the longer run, and while the constructive outlook for the greenback appears well in place for the time being, recent hawkish messages from the BoE and the ECB carry the potential to undermine the expected move higher in the dollar in the next months.
Key events in the US this week: Producer Prices (Tuesday) – MBA Mortgage Applications, Retail Sales, Industrial Production, NAHB Index, FOMC Minutes (Wednesday) – Building Permits, Housing Starts, Initial Claims, Philly Fed Manufacturing Index (Thursday) – CB Leading Index, Existing Home Sales (Friday).
Eminent issues on the back boiler: Escalating geopolitical effervescence vs. Russia and China. Fed’s rate path this year. US-China trade conflict under the Biden administration. Debt ceiling issue.
US Dollar Index relevant levels
Now, the index is losing 0.07% at 96.22 and a break above 96.43 (weekly high Feb.14) would open the door to 97.44 (2022 high Jan.28) and finally 97.80 (high Jun.30 2020). On the flip side, the next down barrier emerges at 95.17 (weekly low Feb.10) followed by 95.13 (weekly low Feb.4) and then 94.62 (2022 low Jan.14).
Author

Pablo Piovano
FXStreet
Born and bred in Argentina, Pablo has been carrying on with his passion for FX markets and trading since his first college years.
















