Nothing Britain does moves the Pound against the Dollar
- GBP/USD trades near 1.3450 on a session range of 36 pips.
- Pound takes 0.17% out of the Dollar, the Australian Dollar 0.68%.
- Next Bank of England decision is 17 September, six weeks away.
The Pound Sterling (GBP) trades near 1.3450 against the US Dollar (USD) on Tuesday, higher by 0.11% inside a session range of 36 pips, the second sub-40-pip day cable has produced inside a week. The pair holds above the 1.3400 handle that capped it through late July and above the moving average band it spent most of the month beneath, though the three sessions since that break have covered an envelope of barely 80 pips.
That reclaim reads as a Sterling story until the cross rates are checked. The Pound is flat against the Euro at -0.02% and the Swiss Franc at +0.06%, behind the Australian Dollar by 0.45% and the New Zealand Dollar by 0.20%, which is the performance profile of a currency being carried rather than one going anywhere on its own.
The Dollar did the work
Tuesday was a Dollar day rather than a Pound day, and not even a uniform one. The Dollar lost 0.68% to the Australian Dollar and 0.45% to the New Zealand Dollar while taking 0.15% from the Canadian Dollar and 0.36% from the Yen, which is the signature of a risk-on session rather than broad Dollar weakness.
The Pound extracted 0.17% from the Dollar on the day, roughly a quarter of what the Australian Dollar managed. What captured the move were the high-beta commodity currencies, lifted by an equity melt-up and the prospect of the Strait of Hormuz reopening. The Pound is not one of them, and it had no domestic bid of its own to supply the difference.
The British side delivered and it did not matter
Domestic news flow over the past fortnight has been about as good as a Pound bull could order. The July flash services survey printed 51.8 against 49.4 expected, back above the expansion line after two months of contraction, with the composite at 52.1 against 49.7 and manufacturing output at a 22-month high.
The Bank of England then held the Bank Rate at 3.75% on 30 July with three members voting for a quarter-point rise to 4.00%, a hawkish minority that has widened at three consecutive meetings and came in one dissent above consensus. The Pound moved 0.08% on the announcement.
The Governor spent the press conference dismantling the hawkish read, telling the room directly not to conclude the Bank was edging toward a hike, and the two-year gilt yield fell seven basis points to around 4.38%. A survey beat of more than two points and the widest dissent bloc of the cycle together bought the currency less than a tenth of a percent.
The Committee's own reasoning explains why the domestic surveys carried so little. Its stated upside risk to inflation is the energy shock, which is being priced in the Persian Gulf rather than in Britain, and the Governor noted that headline inflation had already fallen faster than expected to 2.6%. On that framing, the Hormuz headline that lifted risk appetite on Tuesday is also the thing most likely to dismantle the hawkish minority before September.
Every catalyst this week is American
The British docket from here is close to empty. Wednesday's final July services reading is a revision to a flash that already beat by more than two points, the surveys that follow carry no rate implication, and the next Bank of England decision is September 17, with November and December behind it.
The American side carries three red-band releases in three days. A private payrolls estimate lands Wednesday at 12:15 GMT with a 70K consensus from 98K and the Institute for Supply Management (ISM) services index follows at 14:00 GMT, 54.5 expected from 54. Nonfarm Payrolls arrive Friday at 12:30 GMT, consensus 80K from 57K, with unemployment seen holding at 4.2% and average hourly earnings at 0.3% MoM and 3.5% YoY.
Tuesday's American prints already leaned soft, with June job openings at 7.36 million against a 7.4 million consensus and factory orders down 0.3% against a 0.2% gain expected. Futures pricing captured at the end of July put at least one Fed hike near 59% by September with nothing priced for a cut at any 2026 meeting, so Friday decides the Dollar leg and the Dollar leg decides the pair.
Levels and bias
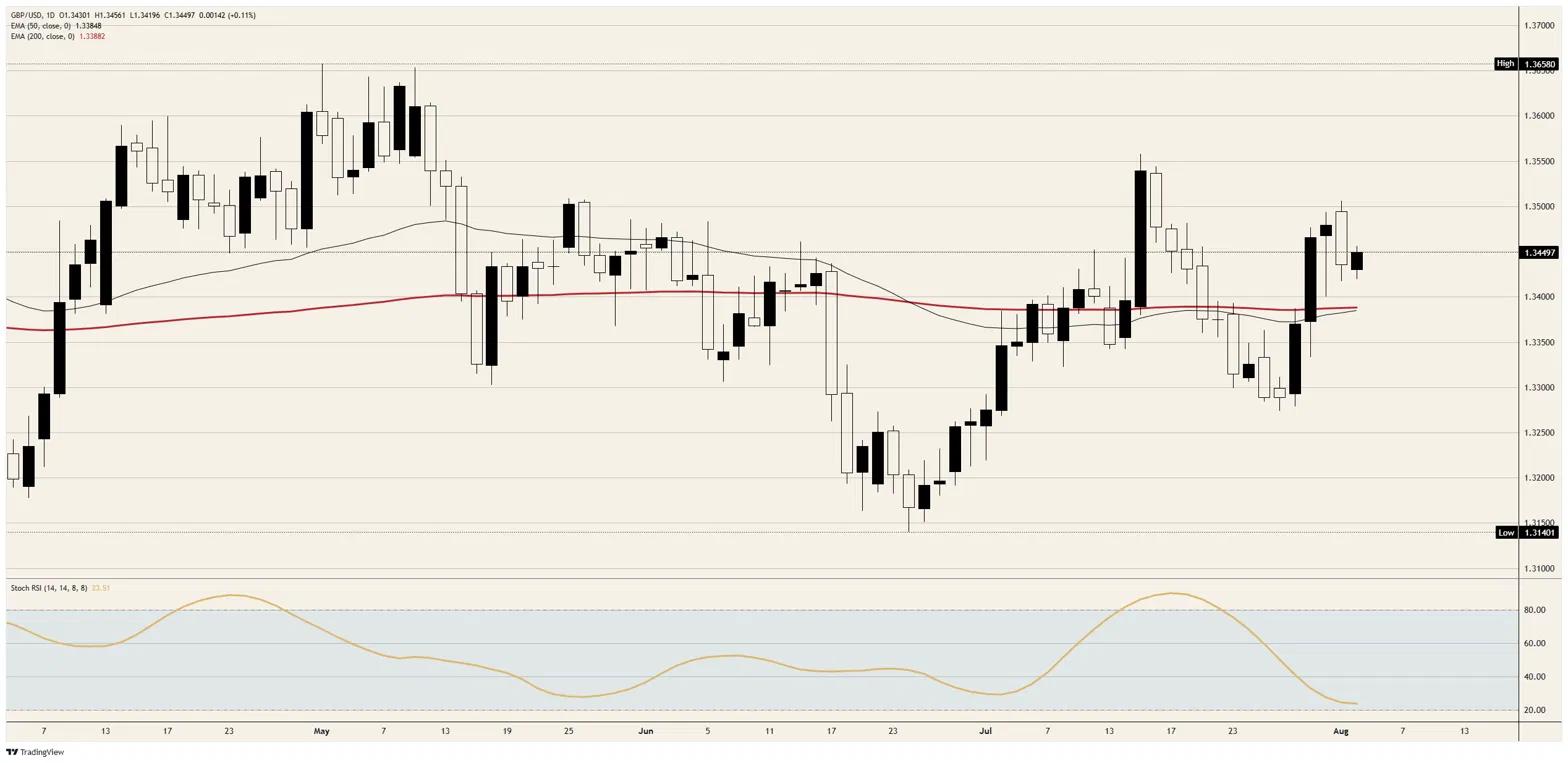
Upside: The three-session ceiling near 1.3500 is the first test, and the mid-July peak near 1.3550 is the level that would confirm the reclaim rather than merely register it. Above that, the May high near 1.3650 is the only structure left on the chart.
Downside: The 1.3400 handle is the line the whole rebound rests on, reinforced by the 50-day and 200-day Exponential Moving Averages (EMA) converged immediately beneath it. Losing that band reopens the late-July low just under 1.3280, with the summer base near 1.3150 the floor behind it.
Bias: Bullish while 1.3400 holds, objective 1.3550. The daily Stochastic Relative Strength Index (Stoch RSI) near 24 and still falling is the one argument against, since momentum kept declining through the rebound, while the 5-minute reading near 73 says nothing beyond intraday drift. Invalidation is a daily close back beneath 1.3400, which returns the pair to the range it spent July failing to leave. Size the position against Friday rather than against anything in Britain.
GBP/USD daily chart
Pound Sterling FAQs
The Pound Sterling (GBP) is the oldest currency in the world (886 AD) and the official currency of the United Kingdom. It is the fourth most traded unit for foreign exchange (FX) in the world, accounting for 12% of all transactions, averaging $630 billion a day, according to 2022 data. Its key trading pairs are GBP/USD, also known as ‘Cable’, which accounts for 11% of FX, GBP/JPY, or the ‘Dragon’ as it is known by traders (3%), and EUR/GBP (2%). The Pound Sterling is issued by the Bank of England (BoE).
The single most important factor influencing the value of the Pound Sterling is monetary policy decided by the Bank of England. The BoE bases its decisions on whether it has achieved its primary goal of “price stability” – a steady inflation rate of around 2%. Its primary tool for achieving this is the adjustment of interest rates. When inflation is too high, the BoE will try to rein it in by raising interest rates, making it more expensive for people and businesses to access credit. This is generally positive for GBP, as higher interest rates make the UK a more attractive place for global investors to park their money. When inflation falls too low it is a sign economic growth is slowing. In this scenario, the BoE will consider lowering interest rates to cheapen credit so businesses will borrow more to invest in growth-generating projects.
Data releases gauge the health of the economy and can impact the value of the Pound Sterling. Indicators such as GDP, Manufacturing and Services PMIs, and employment can all influence the direction of the GBP. A strong economy is good for Sterling. Not only does it attract more foreign investment but it may encourage the BoE to put up interest rates, which will directly strengthen GBP. Otherwise, if economic data is weak, the Pound Sterling is likely to fall.
Another significant data release for the Pound Sterling is the Trade Balance. This indicator measures the difference between what a country earns from its exports and what it spends on imports over a given period. If a country produces highly sought-after exports, its currency will benefit purely from the extra demand created from foreign buyers seeking to purchase these goods. Therefore, a positive net Trade Balance strengthens a currency and vice versa for a negative balance.
Author

Joshua Gibson
FXStreet
Joshua joins the FXStreet team as an Economics and Finance double major from Vancouver Island University with twelve years' experience as an independent trader focusing on technical analysis.

















