Canada Unemployment Rate set to hold at 6.5% as hiring recovers
- Canada's Unemployment Rate is expected to remain unchanged at 6.5% in October.
- The Canadian economy is expected to add 13.6K jobs after losing 68.3K in September.
- The employment report could influence expectations for further Bank of Canada interest rate hikes.
Statistics Canada will release its October Labour Force Survey on Friday at 13:30 GMT, with markets anticipating a modest recovery in employment following September's sharp decline. The Unemployment Rate will also be closely watched, as the latest figures could influence the Canadian Dollar (CAD). The report comes as the Canadian labour market continues to face uncertainty surrounding United States (US) tariffs, which have weighed on hiring prospects in trade-sensitive industries. Investors will closely monitor whether employment conditions are stabilizing after the economy shed nearly 110K jobs over August and September.
Royal Bank of Canada (RBC) notes that September's employment decline was largely concentrated in public-sector positions, particularly education and healthcare, rather than industries directly exposed to US tariffs. RBC also highlights early signs of improving hiring demand in October, suggesting that trade restrictions may have stalled the labour market's recovery without triggering a broader deterioration.
The employment figures take on particular importance after the Bank of Canada (BoC) raised its benchmark interest rate on October 28, marking its first increase in more than three years. Although the central bank has left the door open to additional monetary tightening, future decisions will depend on incoming economic growth and inflation data.
Against this backdrop, a stronger-than-expected employment report could reinforce expectations of further BoC interest rate hikes, particularly if accompanied by resilient wage growth. Conversely, another disappointing reading could raise concerns about the Canadian economy's ability to withstand ongoing trade tensions and encourage policymakers to adopt a more cautious approach.
What can we expect from Canada's Unemployment Rate and jobs report?
Consensus among analysts sees Canada's Unemployment Rate holding steady at 6.5% in October. Additionally, analysts expect the economy to add around 13.6K jobs, partially reversing the substantial 68.3K decline recorded in September.
RBC anticipates a slightly stronger increase of 15K jobs and a modest decline in the Unemployment Rate to 6.4%. The bank argues that the impact of US tariffs remains concentrated in directly affected sectors, while more than 80% of Canadian exports to the US continue to benefit from duty-free access under the United States-Mexico-Canada Agreement (USMCA).
Beyond the headline figures, market participants will pay particular attention to manufacturing employment, full-time positions, wage growth and the participation rate to assess whether the Canadian labour market is showing signs of stabilization.
When is Canada’s October Unemployment Rate released, and how could it affect USD/CAD?
Statistics Canada will publish its October employment report on Friday at 13:30 GMT. A stronger-than-expected reading could provide support to the Canadian Dollar, particularly if accompanied by a decline in unemployment and stronger wage growth, reinforcing expectations of further monetary tightening from the BoC.
Conversely, another disappointing employment report could weigh on the Loonie by reducing expectations of additional interest rate hikes, particularly if employment losses extend beyond sectors directly affected by US trade restrictions.
The simultaneous release of the US employment report could also amplify volatility in the USD/CAD pair, as investors assess the relative strength of the two labour markets and the implications for monetary policy.
USD/CAD trades with a positive bias around 1.4070 on Friday, supported by a firmer US Dollar (USD) amid cautious market sentiment ahead of the employment reports from both countries.
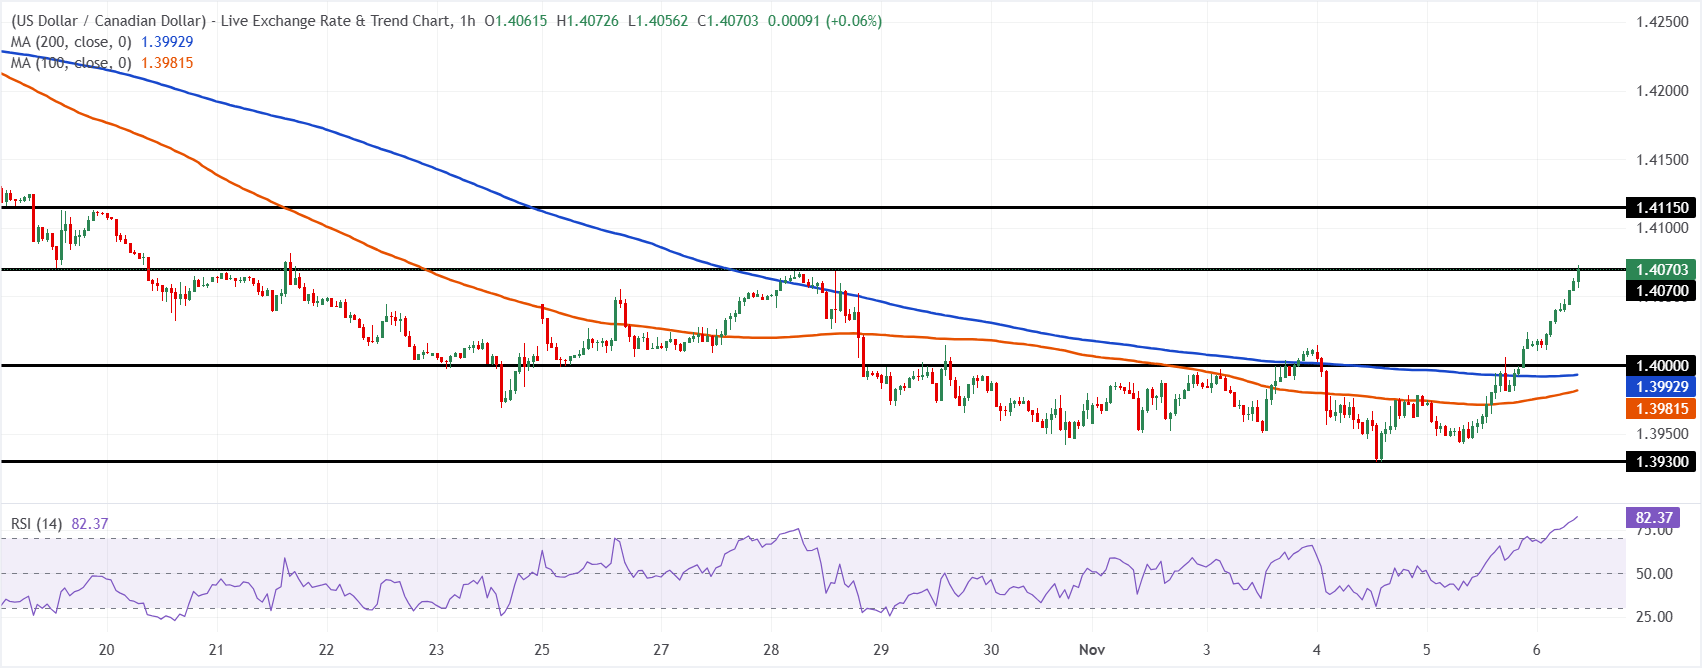
On the one-hour chart, USD/CAD holds a constructive near-term bias as price sits above the 100-period and 200-period Simple Moving Averages (SMAs) clustered just under 1.4000, while testing a horizontal pivot resistance at 1.4070. The Relative Strength Index (14) is deeply overbought near 82, hinting that upside momentum is strong but increasingly stretched as the pair presses higher.
On the topside, a clear breakout above 1.4070 would shift focus to the immediate resistance at 1.4115, where a horizontal barrier may cap further gains if buyers fail to extend the breakout. On the downside, the first layer of support is the psychological backing around 1.4000, followed by the 200-period SMA near 1.3993, with the 100-period SMA around 1.3981 and the 1.3930 horizontal level providing a deeper demand zone if a corrective pullback unfolds.
(The technical analysis of this story was written with the help of an AI tool. Know more.)
Economic Indicator
Net Change in Employment
The Net Change in Employment released by Statistics Canada is a measure of the change in the number of people in employment in Canada. Generally speaking, a rise in this indicator has positive implications for consumer spending and indicates economic growth. Therefore, a high reading is seen as bullish for the Canadian Dollar (CAD), while a low reading is seen as bearish.
Read more.Next release: Fri Nov 06, 2026 13:30
Frequency: Monthly
Consensus: 13.6K
Previous: -68.3K
Source: Statistics Canada
Canada’s labor market statistics tend to have a significant impact on the Canadian dollar, with the Employment Change figure carrying most of the weight. There is a significant correlation between the amount of people working and consumption, which impacts inflation and the Bank of Canada’s rate decisions, in turn moving the C$. Actual figures beating consensus tend to be CAD bullish, with currency markets usually reacting steadily and consistently in response to the publication.
Employment FAQs
Labor market conditions are a key element to assess the health of an economy and thus a key driver for currency valuation. High employment, or low unemployment, has positive implications for consumer spending and thus economic growth, boosting the value of the local currency. Moreover, a very tight labor market – a situation in which there is a shortage of workers to fill open positions – can also have implications on inflation levels and thus monetary policy as low labor supply and high demand leads to higher wages.
The pace at which salaries are growing in an economy is key for policymakers. High wage growth means that households have more money to spend, usually leading to price increases in consumer goods. In contrast to more volatile sources of inflation such as energy prices, wage growth is seen as a key component of underlying and persisting inflation as salary increases are unlikely to be undone. Central banks around the world pay close attention to wage growth data when deciding on monetary policy.
The weight that each central bank assigns to labor market conditions depends on its objectives. Some central banks explicitly have mandates related to the labor market beyond controlling inflation levels. The US Federal Reserve (Fed), for example, has the dual mandate of promoting maximum employment and stable prices. Meanwhile, the European Central Bank’s (ECB) sole mandate is to keep inflation under control. Still, and despite whatever mandates they have, labor market conditions are an important factor for policymakers given its significance as a gauge of the health of the economy and their direct relationship to inflation.
Author

FXStreet Team
FXStreet
Composed of a group of economic journalists and FX experts, the FXStreet content team produces and oversees all content published on FXStreet. It provides a purely journalistic approach to the Forex market.