Indian Rupee declines significantly due to oil price recovery, surging US yields
- The Indian Rupee declines further against the US Dollar due to multiple headwinds.
- A rebound in Oil prices and surging US Treasury Yields weighs on the Indian currency.
- US S&P Global PMI unexpectedly expands at a faster pace in September.
The Indian Rupee (INR) extends its losses against the US Dollar (USD) on Thursday. The USD/INR pair jumps to near 95.96 at the time of writing as the Indian currency comes under pressure, with Oil prices regaining ground and rising United States (US) Treasury Yields due to solid Federal Reserve (Fed) interest rate hike expectations.
As of writing, the MCX Crude Oil contract expiring on October 19 is up 1% at around Rs. 8,900 after recovering early losses. The Oil price bounced back after posting a fresh two-week low near Rs. 8,496. Meanwhile, 10-year US Treasury Yields have posted a fresh 19-year high at 5.14%.
Oil prices bounce back as Iran vows not to surrender to US
Oil prices draw support from Iranian President Masoud Pezeshkian’s speech at the United Nations (US) General Assembly on Wednesday, where he vowed that the Islamic Republic will not surrender to the United States (US).
“They have tested the strength and the steadfastness of Iran and they have learned that Iran cannot be made to surrender,” Iranian President Pezeshkian said.
The statement from the Iranian President came after US President Donald Trump said that Washington has mainly two options: either to make a deal with Iran or annihilate the nation, while pushing back hopes of a deal after Mid-term elections.
Higher Oil prices bode poorly for currencies from economies, such as India, which rely heavily on oil imports to meet their energy needs.
Global PMI surge reinforces Fed hawkish tone
Analysts at MUFG/BTMU highlight that the latest survey data have added to the hawkish policy backdrop, noting that “both the Services and Manufacturing PMI for September surged, which will encourage the Fed to maintain the current hawkish rhetoric.” They stress that the momentum is not confined to the US, with “the data stronger than expected in Europe as well.” In a sign of broad-based expansion, MUFG/BTMU point out that “the Global Composite PMI increased to 58.4 in September, the highest level since July 2021,” underscoring the strength of global activity that is feeding into firmer yields and ongoing support for the Dollar.
Strategists at Deutsche Bank underline how quickly market expectations have shifted, noting that “this hawkish repricing was clear over the last 24 hours,” with pricing for a Fed move in October jumping sharply. They highlight that the probability of an October hike “rose from 53% on Tuesday, to 69% by last night’s close,” underscoring the speed and intensity of the adjustment in rate expectations.
Surging US Treasury Yields due to hawish Fed narrative have also strengthened the US Dollar. At press time, the US Dollar Index (DXY), which gauges the Greenback’s value against six major currencies, trades firmly near the eight-week high of 101.23.
Technical Analysis: USD/INR inches closer to 96.00
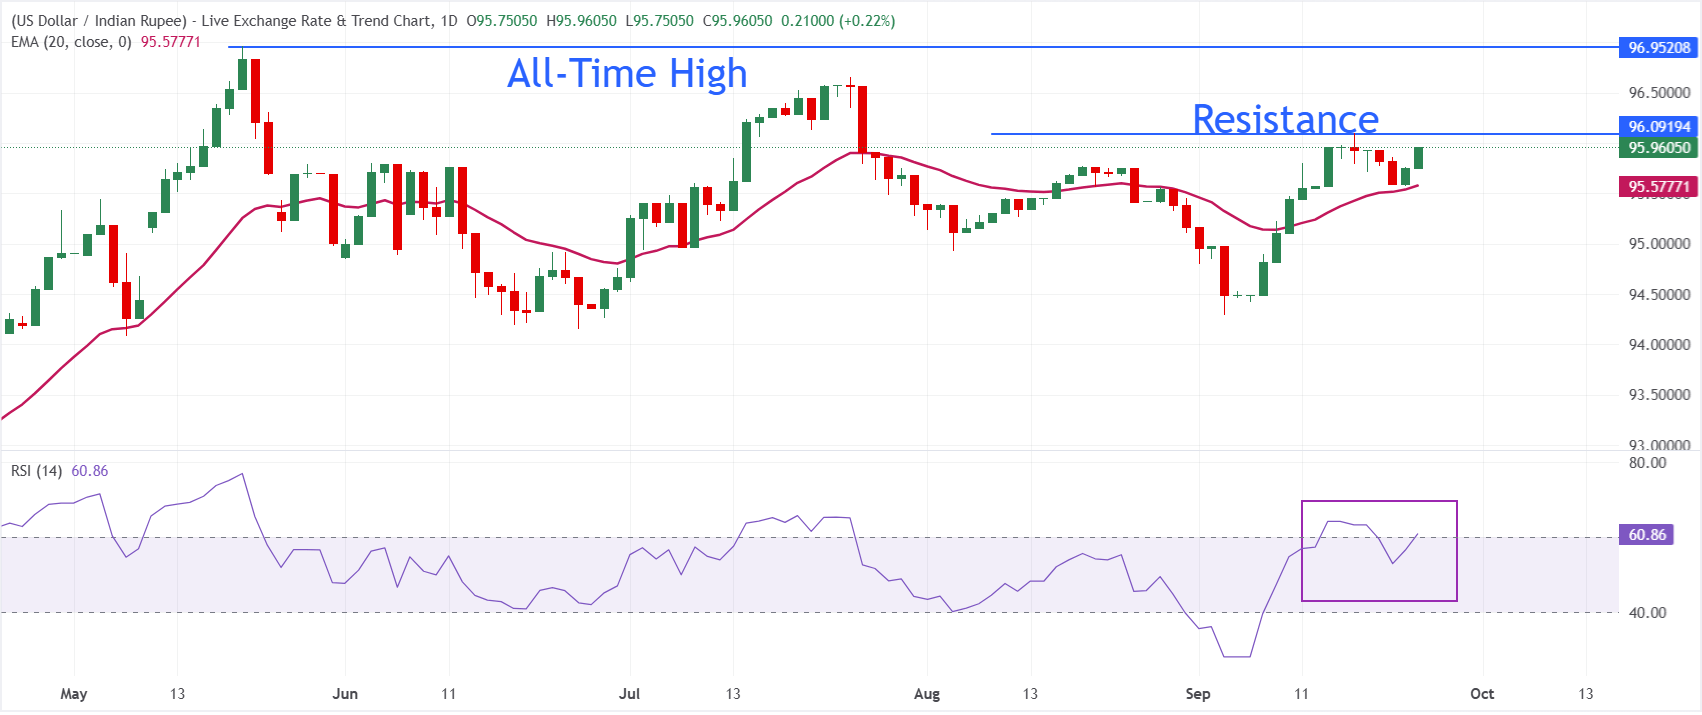
In the daily chart, USD/INR trades at 95.96. The pair holds above the 20-period exponential moving average (EMA) at 95.58, keeping the near-term bias bullish as price extends its recovery from last week’s lows. Momentum supports the constructive tone, with the Relative Strength Index (RSI) at 60.86, staying in positive territory but still shy of overbought conditions.
On the downside, immediate support is seen at the 20-period EMA at 95.58, which reinforces the bullish backdrop while it holds. Looking up, the immediate hurdle for the pair is the September 17 high at 96.10. The odds of the pair revisiting the all-time high near 97.00 would accelerate if it manages a decisive break above 96.10.
(The technical analysis of this story was written with the help of an AI tool. Know more.)
Indian economy FAQs
The Indian economy has averaged a growth rate of 6.13% between 2006 and 2023, which makes it one of the fastest growing in the world. India’s high growth has attracted a lot of foreign investment. This includes Foreign Direct Investment (FDI) into physical projects and Foreign Indirect Investment (FII) by foreign funds into Indian financial markets. The greater the level of investment, the higher the demand for the Rupee (INR). Fluctuations in Dollar-demand from Indian importers also impact INR.
India has to import a great deal of its Oil and gasoline so the price of Oil can have a direct impact on the Rupee. Oil is mostly traded in US Dollars (USD) on international markets so if the price of Oil rises, aggregate demand for USD increases and Indian importers have to sell more Rupees to meet that demand, which is depreciative for the Rupee.
Inflation has a complex effect on the Rupee. Ultimately it indicates an increase in money supply which reduces the Rupee’s overall value. Yet if it rises above the Reserve Bank of India’s (RBI) 4% target, the RBI will raise interest rates to bring it down by reducing credit. Higher interest rates, especially real rates (the difference between interest rates and inflation) strengthen the Rupee. They make India a more profitable place for international investors to park their money. A fall in inflation can be supportive of the Rupee. At the same time lower interest rates can have a depreciatory effect on the Rupee.
India has run a trade deficit for most of its recent history, indicating its imports outweigh its exports. Since the majority of international trade takes place in US Dollars, there are times – due to seasonal demand or order glut – where the high volume of imports leads to significant US Dollar- demand. During these periods the Rupee can weaken as it is heavily sold to meet the demand for Dollars. When markets experience increased volatility, the demand for US Dollars can also shoot up with a similarly negative effect on the Rupee.
Author

Sagar Dua
FXStreet
Sagar Dua is associated with the financial markets from his college days. Along with pursuing post-graduation in Commerce in 2014, he started his markets training with chart analysis.

















