Indian Rupee hits fresh 10-day low amid boiling oil prices
- The Indian Rupee faces intense selling pressure as oil prices continue to soar.
- Oil prices extend their rally as US-Iran tensions remain intact.
- The RBI seems to be failing to counter excessive downside moves in the Indian currency.
The Indian Rupee (INR) extends its losing run against the US Dollar (USD) for the third trading day on Thursday. The USD/INR pair posts a fresh 10-day high at 95.47 as the ongoing rally in oil prices continues to batter the Indian currency.
In the opening session, the MCX Crude Oil contract expiring on September 21 trades 0.5% higher, closer to its over three-month high of Rs. 9,189.
Currencies from economies, such as India, which rely heavily on oil imports to meet their energy needs, tend to underperform in a high-oil-price environment.
Oil rally extends as conflict risks keep market tight
According to TD Securities, crude prices continue to rally as the conflict backdrop shows “seemingly no end to conflict in sight,” with “another round of escalation and an apparent preference for limited attacks and economic squeeze as opposed to deal-making” keeping the energy market on “a continued tightening trajectory.” The bank notes that “while the level of market deficit in crude has eased amid a stabilization of higher dark flow volumes, the market remains tight overall,” reinforcing the view that “the path of least resistance remains to the upside for crude oil even as prices reach triple digits again.”
RBI remains active to counter excessive volatility in INR
The Reserve Bank of India (RBI) continues to intervene in spot and Non-Deliverable Forward (NDF) markets to support the Indian currency against one-way excessive depreciating moves.
"The RBI has maintained its intervention, including a fairly forceful presence at one point yesterday. However, that support has so far provided only limited relief."
Strong foreign flows received by the Indian central bank through the Foreign Currency Non-Resident (FCNR) (B) window indicate the RBI has significant liquidity to support the Indian currency.
Societe Generale’s EM strategists highlight that the Reserve Bank of India has materially strengthened its external buffers, noting that “the RBI disclosed earlier this month that it had raised $136.38bn through its FX mobilisation schemes, including the FCNR(B) window launched in early June, significantly bolstering reserve buffers and intervention capacity.” The bank argues that this sizeable build-up in reserves enhances the RBI’s ability to manage currency volatility and underpins its more constructive stance on the Rupee.
US inflation data awaited
This week, the major trigger for global markets is the United States (US) Consumer Price Index (CPI) for August, which will be released on Friday.
According to TD Securities, the upcoming August CPI report should show that underlying price pressures remain contained, with the bank expecting that "underlying inflation stayed under control, with core likely rising 0.19% m/m (2.3% y/y)." Strategists there highlight that "the services segment should be the main driver, while core goods prices likely acted as a drag by posting a modest m/m drop." In contrast, they anticipate that "headline CPI will likely be a stronger 0.37% m/m (3.4% y/y) due to rising energy prices and a slight pickup in food inflation."
Technical Analysis: USD/INR jumps higher to near 95.50
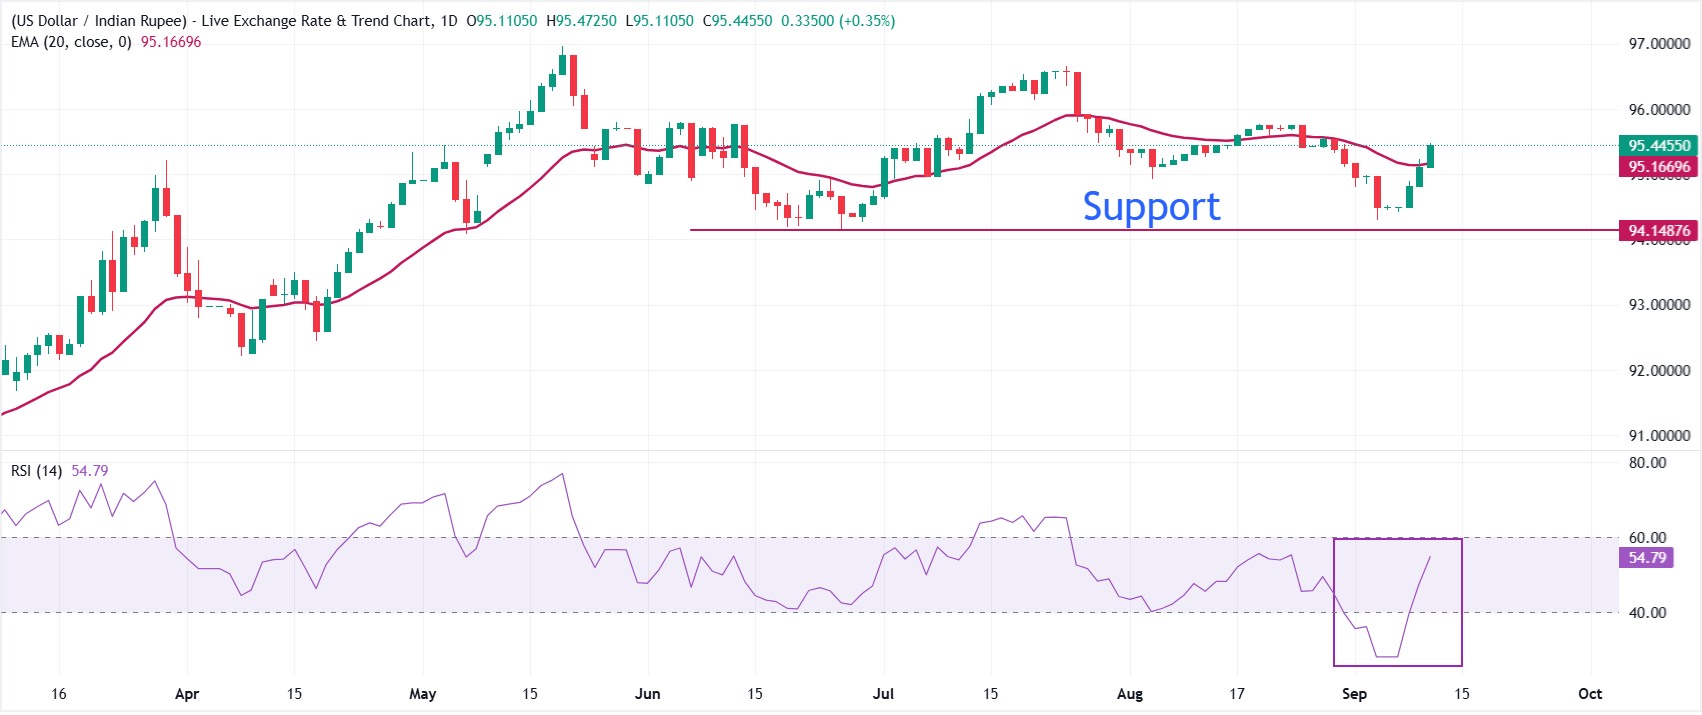
In the daily chart, USD/INR trades at 95.47. The pair quickly returns above the 20-period exponential moving average (EMA) at 95.14 after last week's decline, which turns the near-term bias broadly neutral.
A V-shaped recovery in the Relative Strength Index (RSI) into the 40.00-60.00 zone suggests strong demand at lower levels.
On the downside, the June low at 94.15 is the key support level. Looking up, the pair is expected to find a hurdle near 96.00.
(The technical analysis of this story was written with the help of an AI tool. Know more.)
Indian economy FAQs
The Indian economy has averaged a growth rate of 6.13% between 2006 and 2023, which makes it one of the fastest growing in the world. India’s high growth has attracted a lot of foreign investment. This includes Foreign Direct Investment (FDI) into physical projects and Foreign Indirect Investment (FII) by foreign funds into Indian financial markets. The greater the level of investment, the higher the demand for the Rupee (INR). Fluctuations in Dollar-demand from Indian importers also impact INR.
India has to import a great deal of its Oil and gasoline so the price of Oil can have a direct impact on the Rupee. Oil is mostly traded in US Dollars (USD) on international markets so if the price of Oil rises, aggregate demand for USD increases and Indian importers have to sell more Rupees to meet that demand, which is depreciative for the Rupee.
Inflation has a complex effect on the Rupee. Ultimately it indicates an increase in money supply which reduces the Rupee’s overall value. Yet if it rises above the Reserve Bank of India’s (RBI) 4% target, the RBI will raise interest rates to bring it down by reducing credit. Higher interest rates, especially real rates (the difference between interest rates and inflation) strengthen the Rupee. They make India a more profitable place for international investors to park their money. A fall in inflation can be supportive of the Rupee. At the same time lower interest rates can have a depreciatory effect on the Rupee.
India has run a trade deficit for most of its recent history, indicating its imports outweigh its exports. Since the majority of international trade takes place in US Dollars, there are times – due to seasonal demand or order glut – where the high volume of imports leads to significant US Dollar- demand. During these periods the Rupee can weaken as it is heavily sold to meet the demand for Dollars. When markets experience increased volatility, the demand for US Dollars can also shoot up with a similarly negative effect on the Rupee.
Author

Sagar Dua
FXStreet
Sagar Dua is associated with the financial markets from his college days. Along with pursuing post-graduation in Commerce in 2014, he started his markets training with chart analysis.

















