Higher yields stop paying the Dollar Index
- DXY trades just beneath 99.00, its weakest level since May.
- Yields fully retrace Wednesday's decline while the Dollar retraces none.
- Gold above $4,550 and Bitcoin up more than 20% on the week.

The Dollar Index trades just beneath 99.00 and unchanged on the session, with the entire day fitting inside 35 pips between the 98.50 area and a high that stopped a shade short of the handle. That leaves the index at its weakest since May, at the end of a week in which US long-end yields went up rather than down.
A currency whose government bonds are repricing to higher yields is supposed to attract capital rather than repel it, and for most of this cycle the Dollar Index has traded exactly that way. This week broke the arrangement in both directions. The index fell hard on the day the Treasury tried to force yields lower, then took none of it back when the market forced them straight up again.
Both branches of the fiscal trade sell the Dollar
Wednesday's announcement doubling liquidity-support buybacks in longer-dated coupons, from 2 billion Dollars an operation to at least 4 billion, knocked nine basis points off the thirty-year and took the Dollar Index down close to a point in a single session. By Thursday the bond move had fully reversed, with the thirty-year back above 5.25% and the ten-year above 4.70%. The currency reversed nothing.
Read the two sessions together and the driver names itself. A yield decline engineered by the issuer does not reward the currency, because it is an admission that the natural clearing level sits higher. A yield increase driven by 40 trillion Dollars of federal debt, a deficit tracking past 2 trillion Dollars and a wave of corporate borrowing for artificial intelligence (AI) infrastructure does not reward it either. Both branches price the same risk premium.
Rate expectations are not carrying the weight either, with futures putting September hike odds near a third against a peak above 80% in late July. The Dollar Index lost ground through that entire repricing and has kept losing it since, while the front end moved a fraction of what the long end did this week. A currency that ignores both the level of yields and the path of policy is being priced on something else.
The growth print that bought 35 pips
The preliminary August composite Purchasing Managers Index (PMI) printed 56 against a 54.5 prior, the strongest reading on the series since April 2022, with services at 56.8 against a 54 consensus and the sharpest expansion in that sector since December 2024. Manufacturing missed at 53.2 against 53.9, with goods output at a 13-month low, but services carry roughly three quarters of the economy. That is a domestic growth surprise of the kind that normally reprices the front end and lifts the currency with it.
What it bought instead was a run into the 99.00 handle that the index could not hold. A currency that cannot keep a bid on the strongest domestic activity reading in more than four years is no longer trading its own economy. It is trading who is willing to fund it, and at what price.
Everything that is not the Dollar is bid
Gold trades above $4,550 and at its highest since early June, back through its 200-day moving average. Bitcoin is on track for a weekly gain of more than 20%. Long-end Treasury yields sit at or near their highest in almost two decades. Those three moves share one reading, and it is not a story about the American growth cycle.
The Fed chair's Jackson Hole keynote on Friday is where that reading gets tested. A committee that has held five consecutive times, carries three dissenters wanting a quarter point and has watched market rates do part of its work has every incentive to sound hawkish. Hawkish talk that lifts yields without lifting the Dollar would confirm this week's message rather than reverse it.
Next week does the repricing
July Personal Consumption Expenditures (PCE) prices land Wednesday at 12:30 GMT, with core expected at 0.2% MoM against a 0.1% prior and 3.3% YoY unchanged, alongside preliminary second-quarter Gross Domestic Product (GDP) at 1.5%, personal spending at 0.2% and July durable goods at 0.7%. August consumer confidence prints Tuesday at 14:00 GMT.
The Jackson Hole symposium runs August 27-29, and Friday packs the rest of the week into a single minute. At 14:00 GMT the Fed chair speaks, the preliminary nonfarm payrolls benchmark revision lands and final August Michigan sentiment prints, with one-year inflation expectations running at 4.3% into it. A benchmark revision that subtracts materially from the payrolls base would do more to this currency than anything said from the podium.
Dollar Index technicals
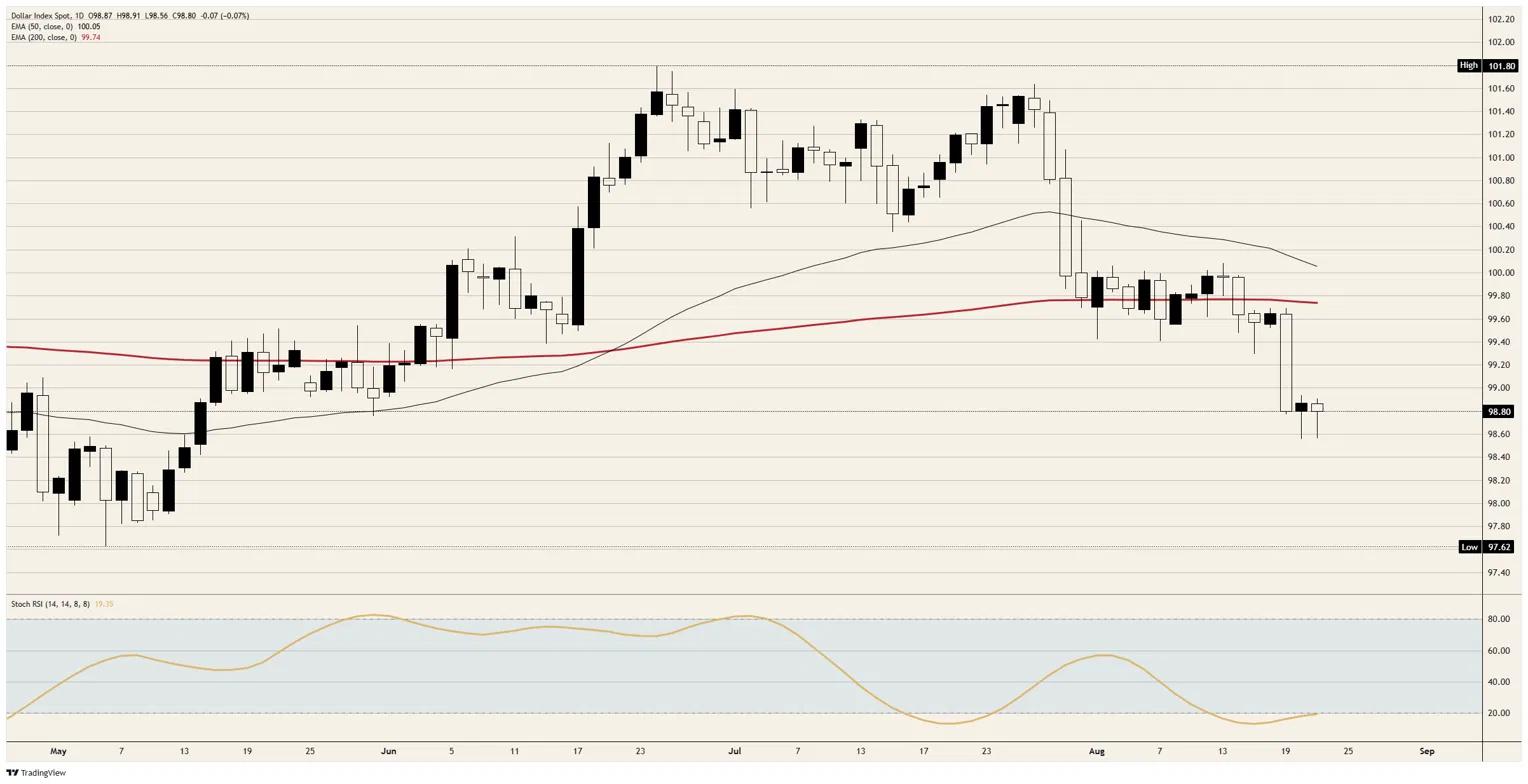
Resistance: The 99.00 handle capped the session high and is the first line back. Above it sit 99.50 and then the moving-average band, the 200-day Exponential Moving Average (EMA) just beneath 99.75 and a declining 50-day at the 100.00 handle, with the late-June peak just above 101.75 the ceiling of the year.
Support: The 98.50 area held the session low, with 98.00 beneath it and the May trough just above 97.50 as the floor of the range.
Bias: Bearish beneath the moving-average band. The 50-day is rolling over toward a 200-day that price has already lost, which is the setup for a bearish crossover rather than a base, and the daily Stochastic Relative Strength Index (Stoch RSI) beneath 20 has produced no bounce across two sessions. Objectives the 98.50 area then 98.00. Invalidation on a daily close back above 99.75.
DXY daily chart
US Dollar FAQs
The US Dollar (USD) is the official currency of the United States of America, and the ‘de facto’ currency of a significant number of other countries where it is found in circulation alongside local notes. It is the most heavily traded currency in the world, accounting for over 88% of all global foreign exchange turnover, or an average of $6.6 trillion in transactions per day, according to data from 2022. Following the second world war, the USD took over from the British Pound as the world’s reserve currency. For most of its history, the US Dollar was backed by Gold, until the Bretton Woods Agreement in 1971 when the Gold Standard went away.
The most important single factor impacting on the value of the US Dollar is monetary policy, which is shaped by the Federal Reserve (Fed). The Fed has two mandates: to achieve price stability (control inflation) and foster full employment. Its primary tool to achieve these two goals is by adjusting interest rates. When prices are rising too quickly and inflation is above the Fed’s 2% target, the Fed will raise rates, which helps the USD value. When inflation falls below 2% or the Unemployment Rate is too high, the Fed may lower interest rates, which weighs on the Greenback.
In extreme situations, the Federal Reserve can also print more Dollars and enact quantitative easing (QE). QE is the process by which the Fed substantially increases the flow of credit in a stuck financial system. It is a non-standard policy measure used when credit has dried up because banks will not lend to each other (out of the fear of counterparty default). It is a last resort when simply lowering interest rates is unlikely to achieve the necessary result. It was the Fed’s weapon of choice to combat the credit crunch that occurred during the Great Financial Crisis in 2008. It involves the Fed printing more Dollars and using them to buy US government bonds predominantly from financial institutions. QE usually leads to a weaker US Dollar.
Quantitative tightening (QT) is the reverse process whereby the Federal Reserve stops buying bonds from financial institutions and does not reinvest the principal from the bonds it holds maturing in new purchases. It is usually positive for the US Dollar.
Author
Joshua Gibson
FXStreet
Joshua joins the FXStreet team as an Economics and Finance double major from Vancouver Island University with twelve years' experience as an independent trader focusing on technical analysis.

















