Fed sticks to hawkish rhetoric, according to FXS Fed Sentiment Index
Following the first policy meeting of the year, the Federal Reserve (Fed) announced that it left the policy rate unchanged at 4.25%-4.5% in a widely anticipated decision. In its policy statement, the Fed acknowledged that inflation data has been stagnant in recent months. Additionally, the central bank removed earlier language suggesting inflation had "made progress" toward its 2% target, instead stating that the pace of price increases "remains elevated."
In the post meeting press conference, Chairman Jerome Powell reiterated that they don't need to be in a hurry to make adjustment to monetary policy, citing elevated uncertainty because of potentially significant changes to economic policies under the Trump administration.
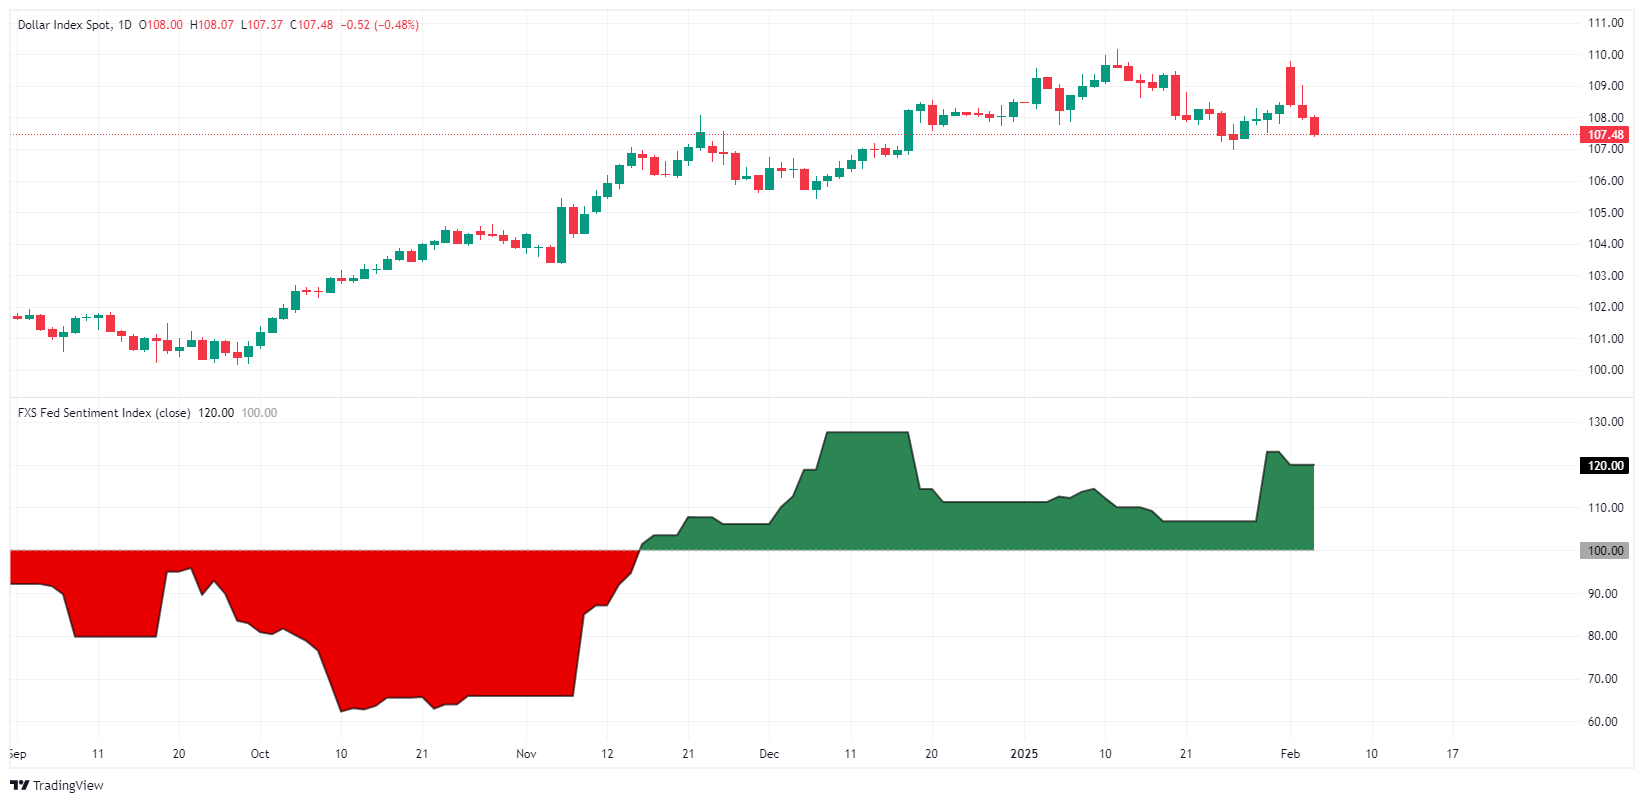
FXStreet (FXS) Fed Sentiment Index rose above 120 from around 107 before the event, suggesting that the Fed adopted a more hawkish tone after the January meeting.
Comments from Fed policymakers on the policy outlook confirmed the hawkish rhetoric, with the FXS Fed Sentiment Index edging only slightly lower to 120.
Fed Vice Chairman Philip Jefferson said late Tuesday that they were facing uncertainty around government policies, adding that the strong economy would allow them to adopt a cautious approach to further policy-easing. Similarly, "the Fed can take its time to look at data and policy changes," San Francisco Fed President Mary Daly. Finally, Chicago Fed President Austan Goolsbee noted that fiscal decisions impacting prices or employment will require careful consideration, arguing that they should slow the pace of rate cuts due to uncertainties.
Fed FAQs
Monetary policy in the US is shaped by the Federal Reserve (Fed). The Fed has two mandates: to achieve price stability and foster full employment. Its primary tool to achieve these goals is by adjusting interest rates. When prices are rising too quickly and inflation is above the Fed’s 2% target, it raises interest rates, increasing borrowing costs throughout the economy. This results in a stronger US Dollar (USD) as it makes the US a more attractive place for international investors to park their money. When inflation falls below 2% or the Unemployment Rate is too high, the Fed may lower interest rates to encourage borrowing, which weighs on the Greenback.
The Federal Reserve (Fed) holds eight policy meetings a year, where the Federal Open Market Committee (FOMC) assesses economic conditions and makes monetary policy decisions. The FOMC is attended by twelve Fed officials – the seven members of the Board of Governors, the president of the Federal Reserve Bank of New York, and four of the remaining eleven regional Reserve Bank presidents, who serve one-year terms on a rotating basis.
In extreme situations, the Federal Reserve may resort to a policy named Quantitative Easing (QE). QE is the process by which the Fed substantially increases the flow of credit in a stuck financial system. It is a non-standard policy measure used during crises or when inflation is extremely low. It was the Fed’s weapon of choice during the Great Financial Crisis in 2008. It involves the Fed printing more Dollars and using them to buy high grade bonds from financial institutions. QE usually weakens the US Dollar.
Quantitative tightening (QT) is the reverse process of QE, whereby the Federal Reserve stops buying bonds from financial institutions and does not reinvest the principal from the bonds it holds maturing, to purchase new bonds. It is usually positive for the value of the US Dollar.
Author

Eren Sengezer
FXStreet
As an economist at heart, Eren Sengezer specializes in the assessment of the short-term and long-term impacts of macroeconomic data, central bank policies and political developments on financial assets.

















