British Pound slides after the Bank of England stays put
- GBP/USD falls to 1.3336, its lowest since July, as the Bank of England holds.
- Three of the nine policymakers voted to raise Bank Rate to 4%.
- Markets price 74% odds of a November hike and four inside a year.
GBP/USD trades near 1.3350 on Thursday after a session low at 1.3336, its weakest since the end of July, and it has been under its 200-day average since Wednesday. The Bank of England (BoE) left Bank Rate at 3.75%, with three of its nine members voting for an increase to 4% and none voting for a cut. That is a committee leaning towards an increase, and Sterling fell anyway.
The vote leaned one way and the minutes leaned the other
UK consumer price inflation reached 3.1% in August, a five-month high and the first reading above 3% since March, with motor fuel a large part of it. The committee said inflation is likely to rise further over coming quarters, and the Bank's own short-term forecast has it above 4% in early 2027. Three members wanted to act on that immediately rather than wait. Committee member Mann, one of the three, pointed at the Bank's own forecast rather than the current number and argued that raising now is the better route.
Governor Andrew Bailey put the other side of it in the same document. Indirect energy pass-through has been weaker than the Bank expected, evidence of second-round effects is very limited, domestic inflationary pressure continues to ease and the labour market is soft. The same meeting also voted to slow the Bank's gilt sales to GBP 20 billion a year. A committee about to raise rates does not usually publish that list.
Sterling is priced to out-yield the Dollar and fell regardless
The market puts 74% odds on a quarter-point increase at the November 5 meeting and takes Bank Rate to 4.18% by the end of the year, with the December 17 meeting almost fully priced for the move if November passes without one. Twelve months out it prices four increases and a rate of 4.71%. The same exercise for the Federal Reserve ends at 4.60%, so the market expects Sterling to pay more than the Dollar a year from now and is selling it at the same time. At the end of this year the two paths are 4.18% and 4.21%, which is the same number.
The explanation is in the second half of that pricing rather than the first. A currency is paid for increases that arrive, and the case for these rests on a fuel price the Bank has already described as passing through more weakly than it expected. Both central banks are raising rates into the same oil shock. Only one of them has a labour market its own committee calls soft, and it is not the United States.
Timing works against the Pound as well. The Bank does not meet again until November 5, which is 48 days away, so there is no scheduled word from its own central bank between now and then. The 74% has to survive seven weeks of data on its own, and the first instalment lands on Friday. The Federal Reserve meets first, on October 28.
What is left this week and what lands next
UK retail sales for August arrive at 06:00 GMT on Friday, forecast at -0.2% on the month after -0.5% in July, which would be a second consecutive fall in volumes. Stripped of fuel the forecast is the same -0.2%, after -0.9%. The annual figures are forecast higher, at 1.9% against 1.6%, which is the shape of a consumer buying the same volume at a higher price. The American half of the pair gets Fed Governor Bowman at 07:30 GMT and August industrial output at 13:15 GMT, where the forecast is a tenth of a point better than July.
Next week the two economies are measured against each other on the same morning. The UK flash purchasing surveys land at 08:30 GMT on Wednesday, with the composite reading at 52.5 last time and manufacturing at 51.7. The American versions follow at 13:45 GMT from a composite of 56. GfK consumer confidence for September is out at 23:01 GMT on Thursday, last at -14, and US durable goods orders and the Michigan sentiment survey close the week on Friday. That survey carries the household inflation expectations the Federal Reserve watches, last at 4.6% for the year ahead.
Levels and bias
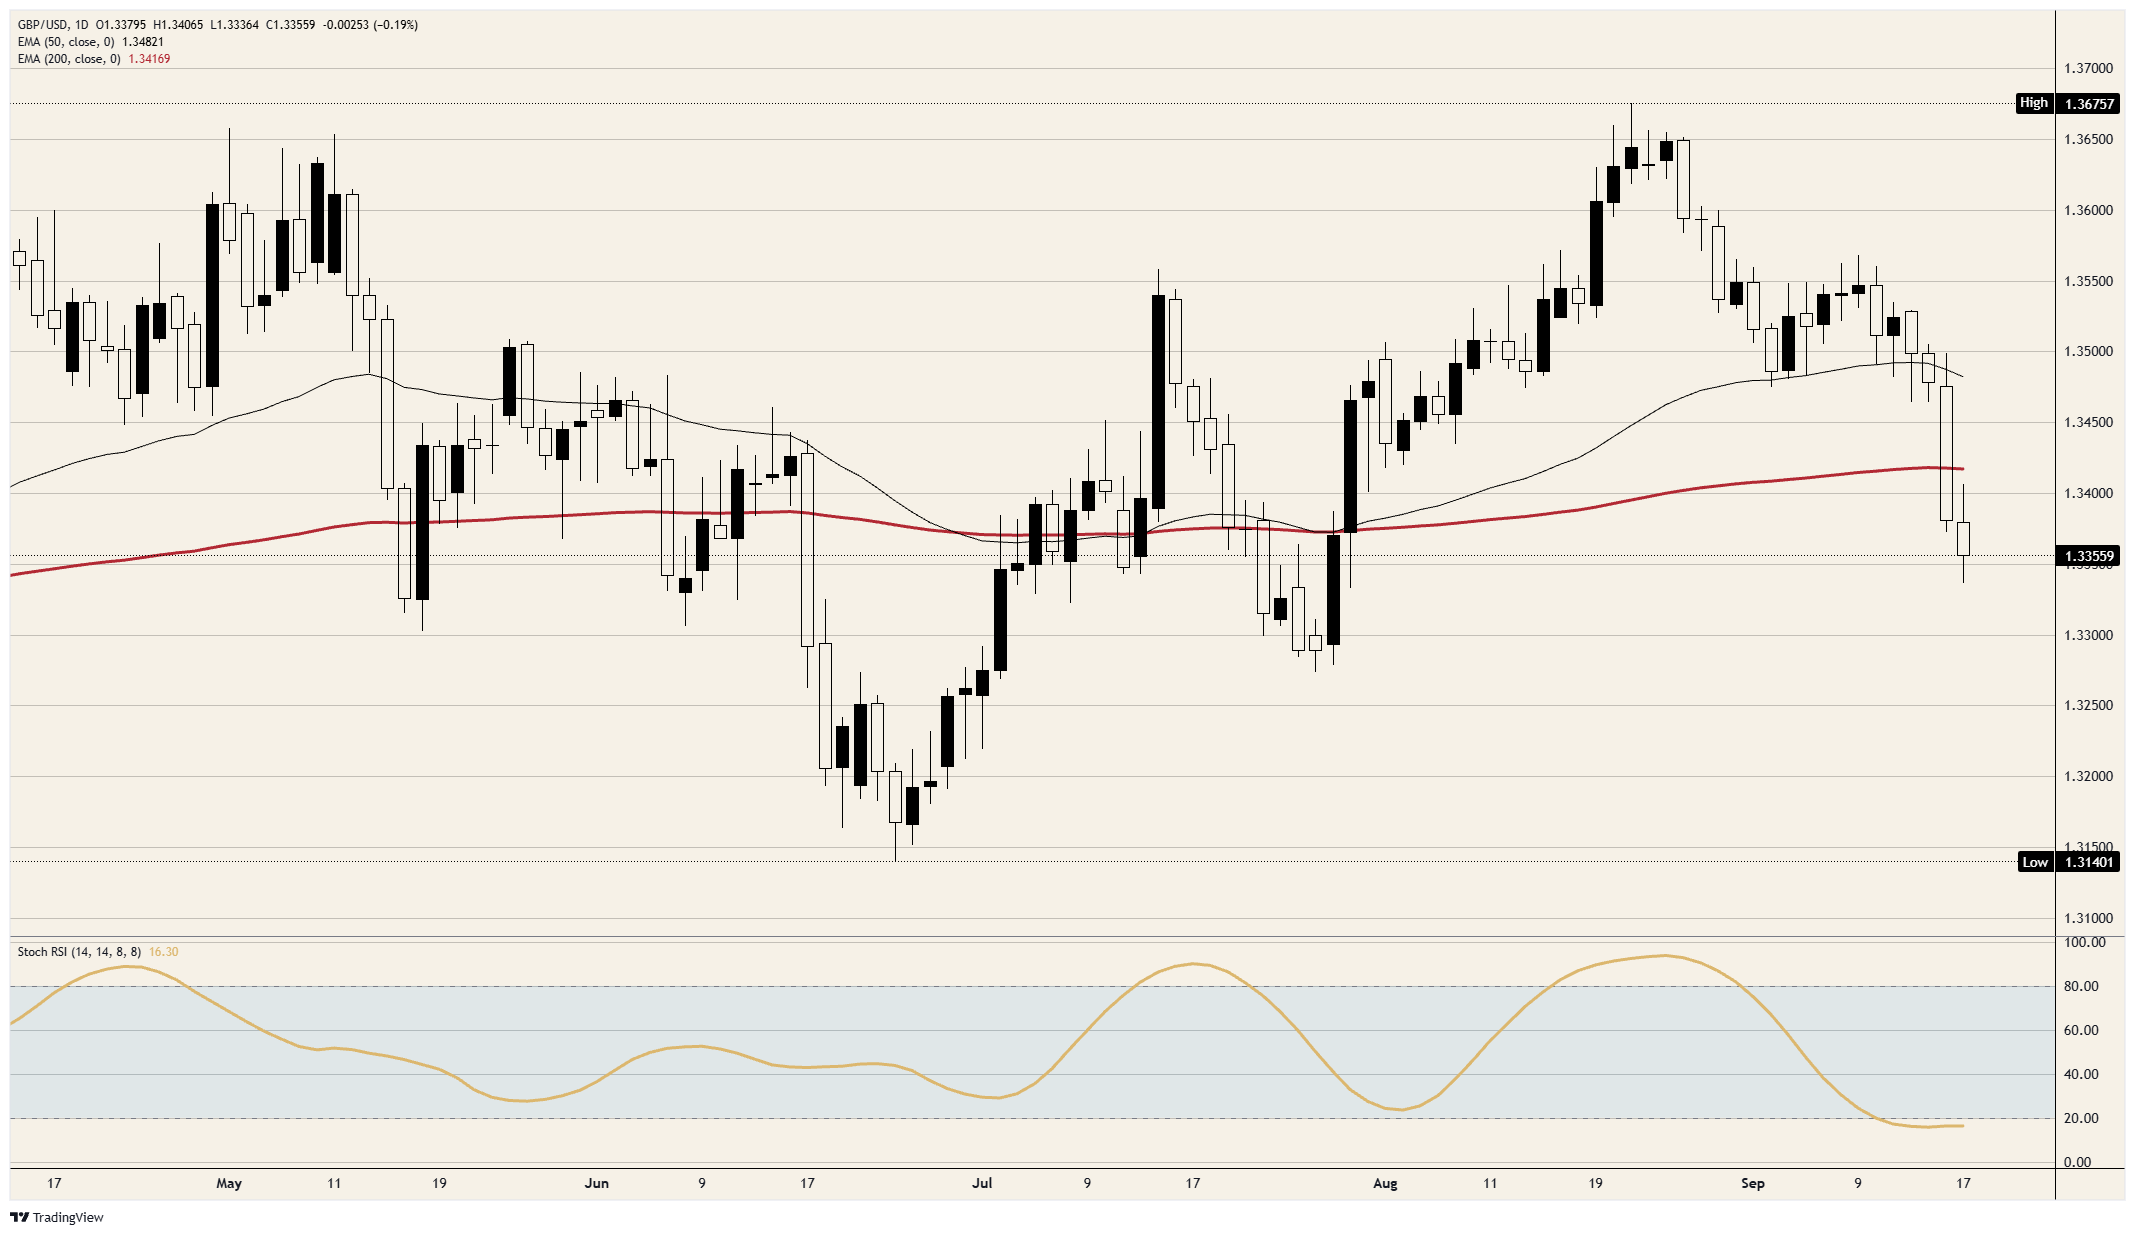
Resistance: 1.3400 held the session high at 1.3407, and the 200-day average runs just above it at 1.3417. Beyond that, 1.3500 is where Wednesday's fall started.
Support: The session low at 1.3336 is the first floor, and beneath it 1.3300 is a level the pair has not traded under since late July.
Bias: Lower while 1.3417 caps. The objectives are 1.3300 and then the late-July low near 1.3270. The daily Stochastic Relative Strength Index (Stoch RSI), a momentum gauge, is near 16 and flat, which is oversold without being a turn. A daily close above 1.3417 ends the case.
GBP/USD daily chart
Pound Sterling FAQs
The Pound Sterling (GBP) is the oldest currency in the world (886 AD) and the official currency of the United Kingdom. It is the fourth most traded unit for foreign exchange (FX) in the world, accounting for 12% of all transactions, averaging $630 billion a day, according to 2022 data. Its key trading pairs are GBP/USD, also known as ‘Cable’, which accounts for 11% of FX, GBP/JPY, or the ‘Dragon’ as it is known by traders (3%), and EUR/GBP (2%). The Pound Sterling is issued by the Bank of England (BoE).
The single most important factor influencing the value of the Pound Sterling is monetary policy decided by the Bank of England. The BoE bases its decisions on whether it has achieved its primary goal of “price stability” – a steady inflation rate of around 2%. Its primary tool for achieving this is the adjustment of interest rates. When inflation is too high, the BoE will try to rein it in by raising interest rates, making it more expensive for people and businesses to access credit. This is generally positive for GBP, as higher interest rates make the UK a more attractive place for global investors to park their money. When inflation falls too low it is a sign economic growth is slowing. In this scenario, the BoE will consider lowering interest rates to cheapen credit so businesses will borrow more to invest in growth-generating projects.
Data releases gauge the health of the economy and can impact the value of the Pound Sterling. Indicators such as GDP, Manufacturing and Services PMIs, and employment can all influence the direction of the GBP. A strong economy is good for Sterling. Not only does it attract more foreign investment but it may encourage the BoE to put up interest rates, which will directly strengthen GBP. Otherwise, if economic data is weak, the Pound Sterling is likely to fall.
Another significant data release for the Pound Sterling is the Trade Balance. This indicator measures the difference between what a country earns from its exports and what it spends on imports over a given period. If a country produces highly sought-after exports, its currency will benefit purely from the extra demand created from foreign buyers seeking to purchase these goods. Therefore, a positive net Trade Balance strengthens a currency and vice versa for a negative balance.
Author

Joshua Gibson
FXStreet
Joshua joins the FXStreet team as an Economics and Finance double major from Vancouver Island University with twelve years' experience as an independent trader focusing on technical analysis.